Heterodoxy: Pearl is reviving Bitcoin
 Core Viewpoint

 Bitcoin has proven that useless computation can be turned into currency. Pearl bets that useful computation can be turned into harder currency. This article argues the possibility of "AI currency" from three clues: computational cost, security boundaries, and monetary foundations.
Author: @brezshares, Investor at No Limit Holdings
Compiled by: ChainCatcher
The reason No Limit Holdings has long been heavily invested in Pearl is that we believe it has the potential to become the next Bitcoin. Here are the reasons…
Bitcoin is a religion. It has scriptures, prophets, disciples, a virgin birth, and the most devout followers in the financial world.
The orthodox doctrine holds "wasting computational power" as one of the most sacred tenets—it's not just an unfortunate side effect of proof of work, but a necessary condition for hard currency.
This is wrong.
Although I was once a disciple of Satoshi Nakamoto, I have now become a heretic. A harder currency can exist: let useful AI computations be both objective and expensive enough to be hard to fake, while also cheap enough to verify—just like Bitcoin's work, but without wasting computational power. This will give rise to a new religion and present a rare opportunity for a "second virgin birth."
In Christianity, the Passover miracle does not view Christ's suffering, death, resurrection, and ascension as independent events, but as a continuous act of redemption.
Pearl (@prlnet) has made me start thinking about Bitcoin in the same way.
Wasting computational power, diminishing security budgets, Bitcoin miners migrating to AI, and the rise of "useful proof of work" seem to be several independent stories.
I increasingly feel that they are different chapters in the same book. That book is called "Pearl."
Original Sin
"Bitcoin is wasting computational power."
That's how our conversation began. For the next hour, we discussed whether we could redesign proof of work so that the computations used to secure the network are not just burned but also useful elsewhere.
In other words: any solution to a SHA-256 hash has no meaning and is not used anywhere except to secure Bitcoin. Essentially, it is wasteful and unrecoverable. Currently, the total network hashrate is close to 1,000 EH/s, consuming about 175 TWh of electricity annually, which is deliberately "wasted" just to protect the Bitcoin network—roughly equivalent to the total electricity consumption of a medium-sized country like Sweden or Poland in a year.
This waste is intentional. Its sunk cost is key to preventing malicious miners from controlling the network at a very low cost. But what if we could replace SHA-256 with another algorithm? A more useful algorithm—where the cost of attacking the network remains high, but the computation itself has value as an independent product.
"Useful proof of work"—we whispered this term together.
This concept is elegant and powerful. His project is a new layer 1 PoW network designed to have miners compete around AI reasoning rather than solving a meaningless hash puzzle. In other words: reconstruct the economic framework of Bitcoin, but replace useless computations with genuinely needed AI computations.
The problem is that "useful" computations are much more complicated than SHA-256. They also need to be expensive enough to be difficult to complete, but the answers must also be objective and cheap to verify for everyone else. Bitcoin perfectly achieves this asymmetry: mining is brutally expensive, but verification is almost free. Yet "useful proof of work" (PoUW) has never achieved both at the same time.
Bittensor: False Prophet
I am deeply attracted to "useful proof of work." This narrative is simply impeccable. When you dig down this line, the first thing you encounter is Bittensor (@opentensor)—it has long tried to become that "AI version of Bitcoin": a scarce native token, miners providing AI-related resources, and validators judging outputs, with emissions flowing to those deemed valuable by the network.
In theory, it sounds good. The problem lies in the words "deemed valuable."
The kind of useless computation in Bitcoin has a simple beauty: no one needs to argue whether this hash is useful enough. Miners do not need committees, scorecards, or economic votes to decide who does best. The answer either meets the target value or it does not.
Bittensor inevitably introduces more subjective judgments. As the network continuously improves its value measurement and emission distribution methods, its incentive system is also evolving substantively. For an AI coordination network, this is entirely reasonable. I just don't think this is the way to mint currency.
The subjectivity of Bittensor's consensus mechanism (named Yuma) also leaves a historical record of collusion within the network—the reason is straightforward: validators are incentivized to cooperate in voting to determine "usefulness." For an asset that wants to become a trusted currency, this is a veto point.
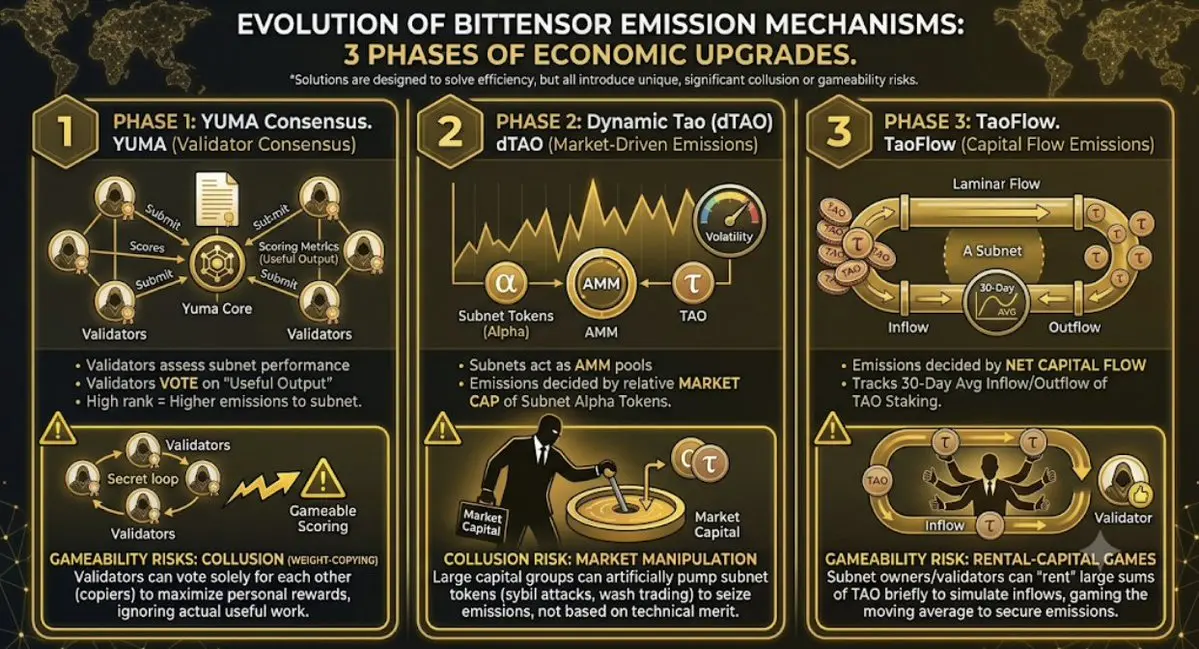
The real challenge is: how to make useful computations behave like Bitcoin's computations.
Bitcoin's proof of work possesses four "currency" qualities
Computations must be expensive and objective. The winning block cannot carry any subjective scoring.
Computations must be cheap to verify. A laptop should be able to reject an dishonest large-scale computing provider.
Consensus cannot decide what "useful" means. Once you need it, you introduce oracles, voting, or governance.
Currency rules must be solidified. Upgradability is useful for software, but predictability is essential for currency.
Resurrection
When He finally revealed the name of that AI PoW creation, these traps were swirling in my mind. It is called Pearl.
This rhetoric sounds almost suspiciously obvious: fork Bitcoin, replace SHA-256 with matrix multiplication, allowing the same GPU computation to produce both AI results and proof of work. What really caught my attention was not the "AI mining" part—since Bittensor, people have been selling useful mining. What caught my attention was its verification construct:
Pearl's core research demonstrates how to transform arbitrary matrix multiplication into proof of work, with proof overhead that can be asymptotically negligible—provided that a new computational hardness assumption around "low-rank noisy matrix multiplication" is introduced. The engineering implementation packages the winning work into a compact zero-knowledge block opening proof, so that ordinary nodes do not have to rerun an H100-level computing task to verify a block.
Once again, in plain language: Pearl has found a way to make AI computations verifiable as cheaply and quickly as Bitcoin computations.
That is the key.
What is matrix multiplication?
Large language models (LLMs) are built on artificial neural networks. Most of these neural networks use the Transformer architecture (popularized by the landmark paper "Attention is All You Need" from 2017). Transformers process data through layers of nodes, weights, and mathematical functions, forming the backbone of modern large models like GPT and Claude.
Transformers carry a digital grid known as "activation values" through layers of learned weight matrices. Each layer repeatedly multiplies the activation values by the weights, transforms the results, and passes them forward. The arithmetic primitive supporting this massive computation is matrix multiplication, abbreviated as MatMul. GPUs are essentially huge matrix multiplication machines, and it is these algorithms that make AI possible. Every modern LLM, image model, and AI entity ultimately spends vast computational budgets pushing matrices through these kernels (kernels are core pieces of code that run on GPUs, telling them how to operate and initiate).
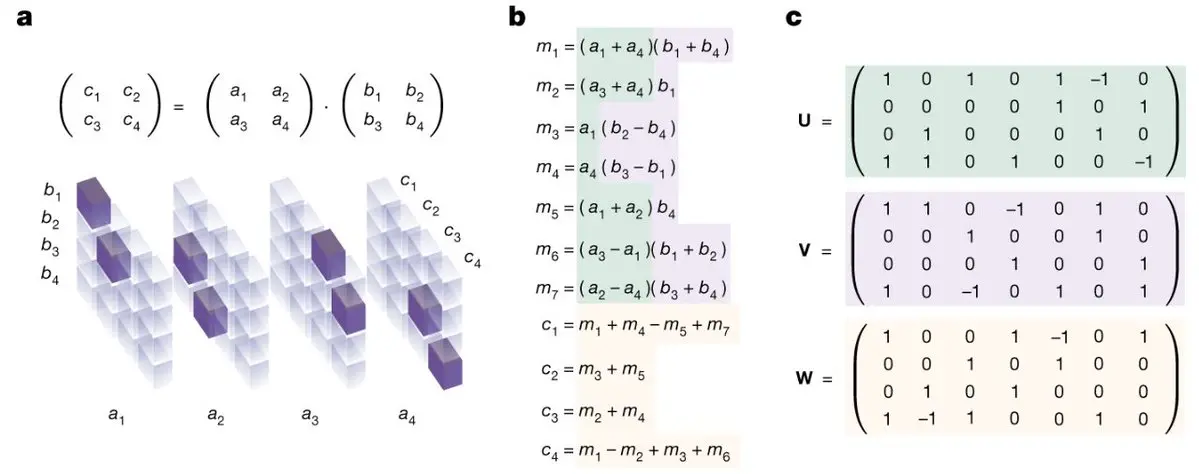
MatMul shares many similarities with SHA-256: it requires a lot of computational power to solve quickly, the solutions are not subjective, and they cannot be faked or guessed (you cannot predict what the function of the next block will be). But there is a stark difference: SHA-256 has no practical use outside of protecting the Bitcoin network, while matrix multiplication is precisely what drives the computational power of AI. From this, we can infer: we should fork Bitcoin and replace SHA-256 in the proof of work mechanism with MatMul. This way, this new "MatMul Bitcoin" can be decentralized and secure like Bitcoin, and the same computation invested in network security can also be useful for AI applications outside the network.
What Pearl has created is exactly this.
So how does it work in practice?
Pearl can be understood as: before the GPU starts computing, it first attaches a tamper-proof lottery ticket to this AI task. First, miners cryptographically seal the matrices to be multiplied, making them impossible to swap out afterward. Then the network adds a small and unpredictable mathematical "watermark" derived from the latest chain state. The matrix multiplication executed by the GPU is almost identical to what the AI workload would require, but each run is unique and cannot be pre-computed.
During the multiplication process, the GPU leaves behind an "operation record." If any part of this work happens to meet Pearl's difficulty target, the miner has found a block. The key is that Pearl's watermark can be stripped away afterward at an extremely low mathematical cost, preserving the originally useful AI results. This is Pearl's significant innovation: making MatMul as cheaply verifiable as SHA-256.
To be more technical: Pearl commits to the input matrices using BLAKE3, derives pseudo-random low-rank noise from the chain state, executes noise-perturbed block MatMul, and records a mining record—once it hits the difficulty predicate, this record can be proven.
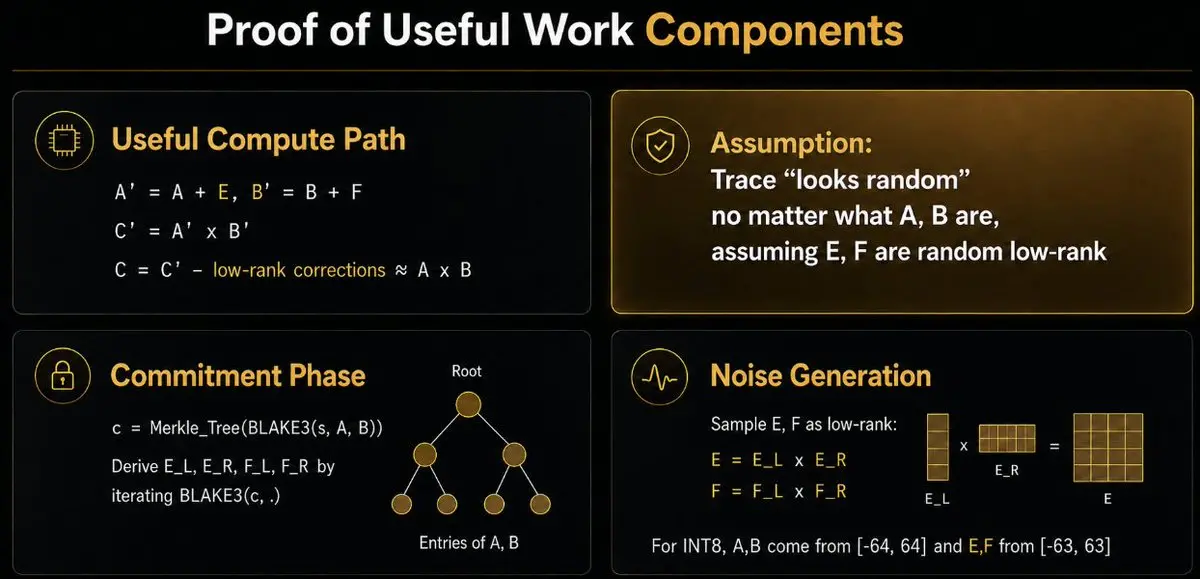
Some might say: wait, to prove that the miner really executed the promised computation, you have to reveal the rows and columns of the matrix, which is still re-computation and might leak proprietary model weights.
Pearl solves the second problem with ZK-SNARK block opening proofs. The prover must demonstrate that they possess private matrix data consistent with the commitment and that the winning blocks meet the mining predicate, while the network only sees a compact certificate. This final recursive proof is less than 60KB.
In theory, this also makes it possible for closed-source labs to participate: the protocol does not require labs to disclose their weights just for participating in mining.
High manufacturing costs, low verification costs, objective consensus, predictable rules—these are precisely the Bitcoin-like characteristics that all previous "useful work" designs have failed to solve simultaneously.
The Meme of "Useful Work"
An important criticism of Pearl is technically correct, but in my view, it completely misses its economic design.
The underlying protocol does not explicitly prove that a particular matrix multiplication comes from a paid inference client. Miners can feed the protocol synthetic matrices and still complete valid Proof of Useful Work (PoUW) and earn Pearl rewards.
In fact, an empirical paper published this summer measured the early Pearl network and found that the mainstream mining software at the time produced verifiable MatMul but did not generate external inference outputs.
However, what this criticism fails to realize is: this is precisely the point.
If PoW consensus has to ask, "Is this inference really useful?", you are back in the subjective world we want to escape from. You would need a subjective judgment, a vote, a validator score, or some semantic definition of "usefulness"—and these things can be manipulated, colluded, or changed arbitrarily.
Therefore, Pearl takes a game-theoretic approach to mining. Pearl still verifies what it can objectively validate: expensive MatMul; then it simply lets the market spontaneously enforce "useful work" rather than explicitly checking.
A pure 1:1 miner (i.e., a "non-useful" miner) must pay the full GPU cost to earn PRL. A "duplex" miner (both mining and providing useful inference externally) has already received payment for the AI workload from clients and only needs to absorb Pearl's incremental costs. As competition intensifies and the difficulty of the Pearl network increases, full-cost miners will become marginal producers, ultimately being pushed out by the useful miners who have "already paid most of the electricity costs."
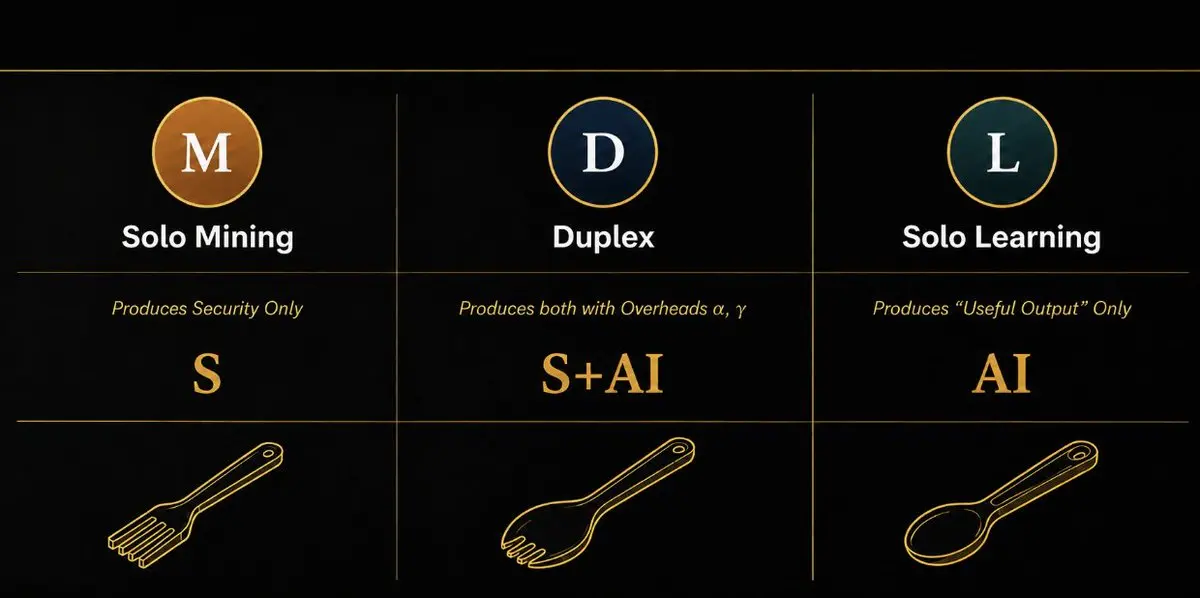
In other words, once there are enough useful miners participating in the network, non-useful miners can no longer profit from mining Pearl, and thus have no incentive to continue mining.
In this way, Pearl is very much like Bitcoin. The network does not actually care what constitutes useful work or what counts as useful work—its mechanism is that economic reality will force useful work to be done by miners. This design significantly reduces the collusion risk for Pearl miners, making Pearl a trustless and fair network like Bitcoin.
So the question is not "Does Pearl today force the generation of useful work?"—it does not. The question is: Can the costs be low enough for useful miners to become the structurally lowest-cost producers?
The Key to the Whole Game is Cost
Once you view Pearl this way, the project becomes much easier to understand. Forget the philosophical debates about PoUW. Only one thing matters: incremental costs, which are the additional costs and delays incurred after connecting to Pearl's 2:1 kernel.
The data currently disclosed by Pearl shows that when running Llama 70B on four H200s, the end-to-end cost is +5.08%; when running DeepSeek V3.2 on eight H200s, it is +3.9% (compared to the original inference engine). The current production path uses integer W7A7 quantization; native floating-point support is still under development.
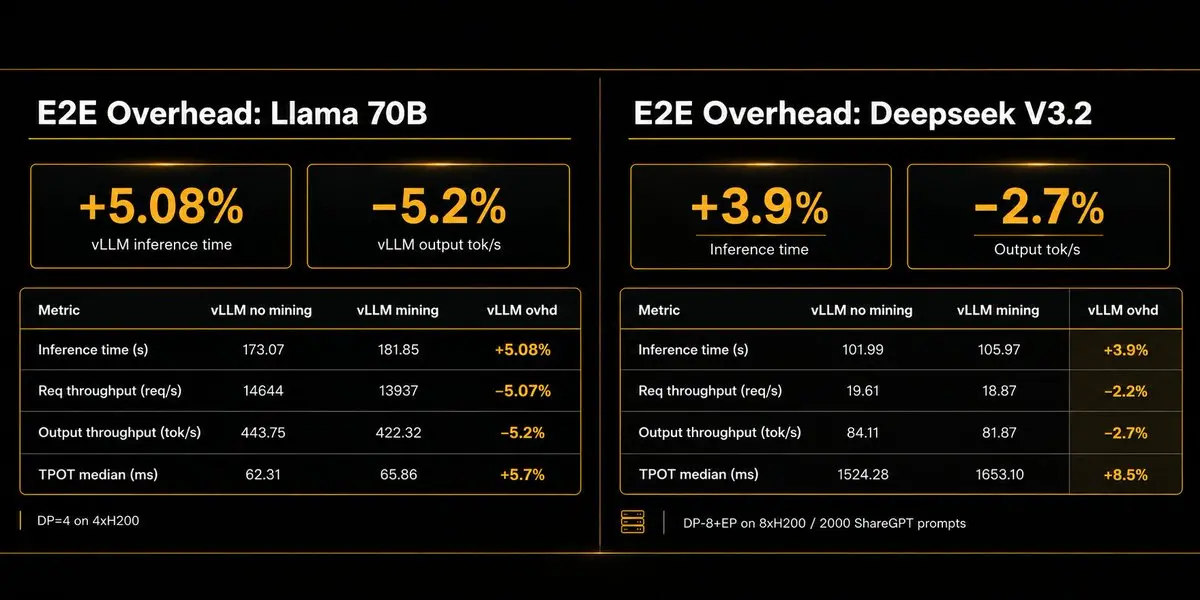
Bitcoin's hash power will grow as long as "block rewards > mining costs"; while Pearl's hash power will grow as long as "block rewards > AI inference income lost due to adopting Pearl (i.e., costs)."
5% is not "free." In the highly volatile cryptocurrency market, 5% sounds like rounding error; but for a group of inference machines with thin margins, this is real money. However, it has already fallen within the range where "block reward subsidies could potentially compensate service providers," and the clear goal of the roadmap is to push this number toward zero.
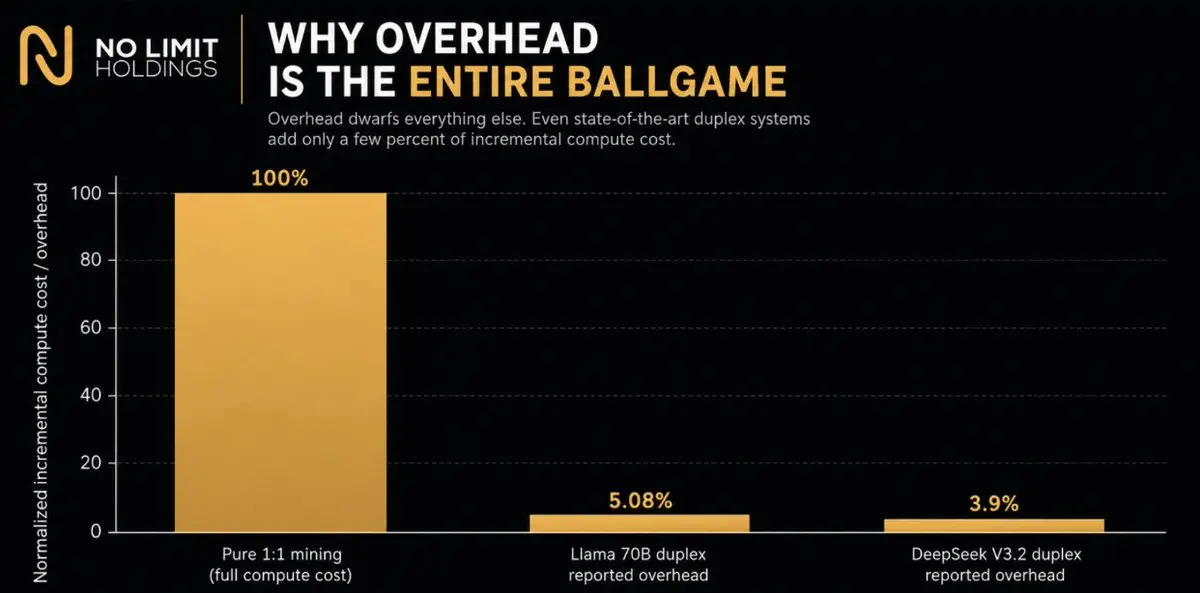
When costs drop to 0%, the situation becomes obvious: If two inference service providers with identical conditions sell the same tokens at the same price, and one can additionally earn PRL without a noticeable drop in throughput, then the one not mining is voluntarily leaving money on the table. Competition will force adoption.
In reality, Pearl does not need to achieve mathematically zero costs for this to start happening. It only needs: PRL subsidies, after deducting integration friction and risk, to still be worth more than the lost throughput and engineering costs (i.e., costs).
The Chess Master Problem
Everything I just said has an obvious problem.
If Pearl successfully drives mining costs toward 0%, are we also driving the cost of attacking Pearl toward 0%? An attacker could rent a bunch of GPUs to attack the network while selling the useful inference produced by those GPUs. Have we just invented a blockchain that "pays you to attack it"?
This sounds compelling. But it is also wrong.
Rafael Pass (@PassRafael), an MIT PhD, Cornell University professor, and core advisor at Pearl Research Labs, used a chess analogy in his landmark paper "The Economics of Proof-of-Useful-Work" to explain why.
Imagine I play a game of chess against two chess masters. In one game I play white, and in the other, I play black. If I really play both games myself, I would obviously be checkmated (my skill level cannot compare to that of the masters).
Clearly, I need to change my strategy. A strange thought occurs to me… what if I play both games simultaneously? This way, I wait for Master A to make a move, then replicate that move for Master B; no matter how B responds, I take that move back to play against A. And so on. In each master's view, they are playing against me; but in reality, it is the two masters playing against each other through me.
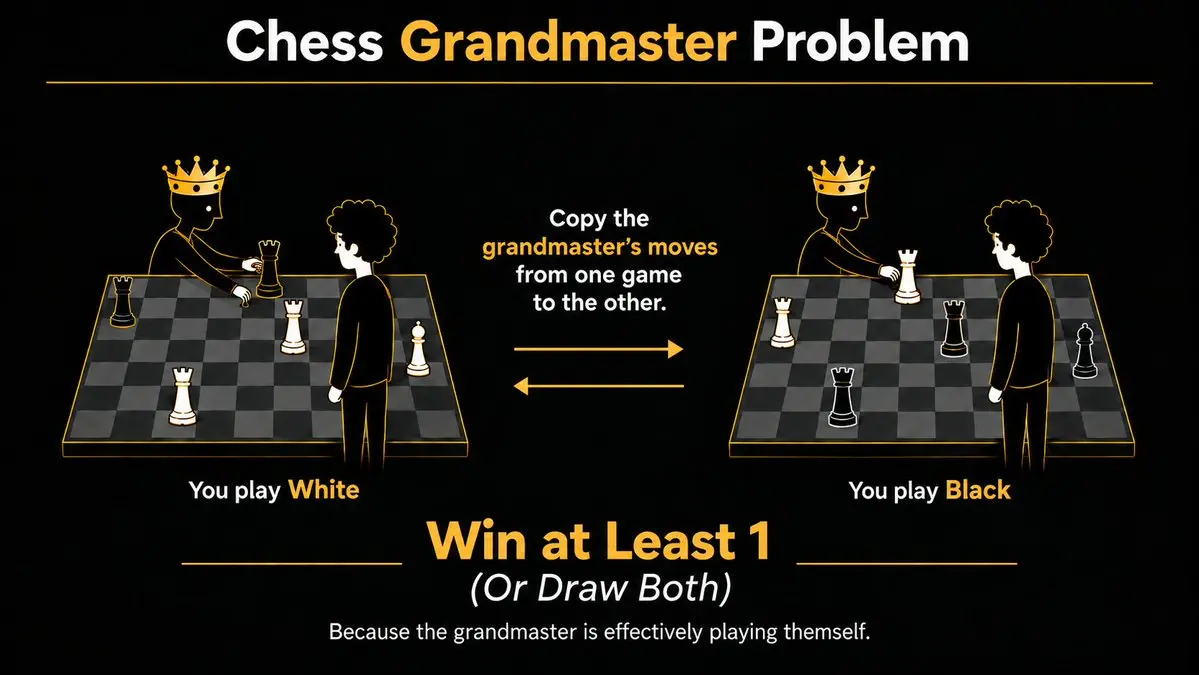
If A wins, I lose one game and win the other; if they draw, I draw both. In any case, by tying the two games together, I ensure that I do not lose at least—despite the fact that the chance of me achieving this in any single game is almost zero.
The mistake people make when analyzing the inference business and Pearl mining is treating them as two separate businesses. You cannot view them this way. They are a joint economic system.
Assume a GPU worth $1.00 produces an inference task. Before Pearl, service providers needed about $1.00 in inference income to cover the computing cost. Now assume the same task can also earn $0.20 in PRL. Then a duplex service provider (selling inference and mining Pearl) can sell the inference for $0.80 while also earning $0.20 in PRL, thus breaking even on the $1.00 computing cost:
Competition will not allow it to earn $1.20 forever; rather, it will push that $0.20 PRL subsidy into the price of inference.
Thus, the equilibrium starts to look like this:
$0.80 inference + $0.20 PRL = $1.00 computing cost
Now imagine an attacker appears.
The attacker faces the same GPU economic calculations as others. While attacking Pearl, he can still sell the useful inference produced by those GPUs for $0.80.
So at first glance, this attack seems almost free:
He spends $1.00 on computing. Sells inference for $0.80.
And normally, he could expect another $0.20 in PRL.
That last $0.20 is precisely the source of security.
A successful 51% attack is not normal mining. What the attacker is trying to disrupt is precisely the network that should be paying him. He cannot safely assume that the PRL earned during the attack will still be worth the price before the attack.
So, subtract the PRL rewards from the attacker's recovery calculations:
$1.00 computing cost - $0.80 inference income = $0.20 attack cost
That $0.20 is the security budget.
Now scale this example up:
Imagine the entire Pearl network represents 100 units of computing power.
Each unit has an operating cost of $1.00 and earns:
$0.80 from inference
$0.20 from PRL
Therefore, across the entire network, Pearl needs to pay:
100 × $0.20 = $20 in block reward subsidies.
The attacker needs to control half the network to break the honest majority assumption, so he needs 50 units of computing power.
These 50 units will cost $50 to operate, but he can sell the useful inference and recover $40:
$50 computing - $40 inference income = $10 net attack cost
What is that $10?
It is exactly half of the network's $20 Pearl reward budget.
Pass proves: The cost of attacking Pearl is exactly the same as the cost of attacking Bitcoin, which is:
Attack cost = Block subsidy ÷ 2
This is a subtle but extremely important point: The marginal technical cost of layering Pearl mining on top of inference can approach zero, but the economic cost of acquiring Pearl's security will not approach zero. Subsidies will be competed away elsewhere in the system—in this case, being competed into cheaper inference prices.
This is also where "Proof of Useful Work" becomes truly interesting. If block rewards are competed into inference prices, Pearl is not just attaching a token to an existing computing power market; it is changing the cost curve of the computing power market itself. Pass elaborates further on this in the "Duplexia Framework."
The Gospel
Pass named the equilibrium evolution underlying the chess example.
Bitconia: Pearl behaves like ordinary Proof of Work. Miners compete because of block rewards. Useful inference is economically separate.
Fortessia: Duplex service providers begin to replace pure miners. The same AI workloads are completed, but a larger portion is simultaneously protecting the chain. Security increases without a proportional increase in the computing power that would otherwise be wasted. (Pearl is currently here.)
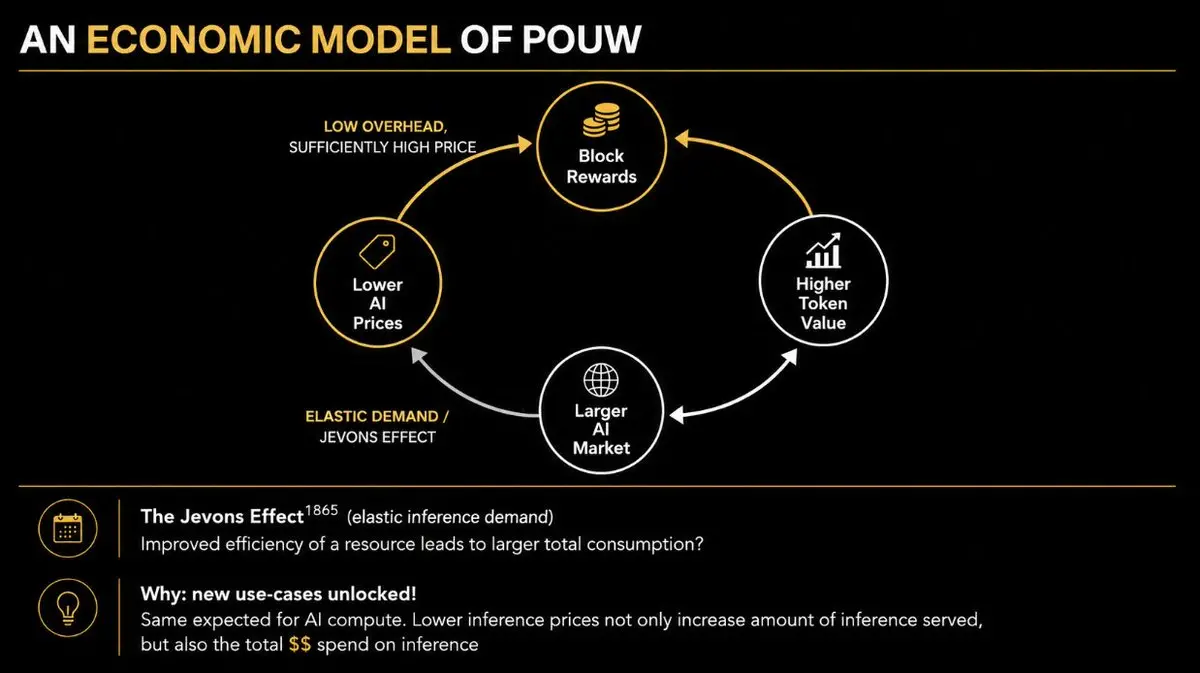
Duplexia: Token subsidies for inference economics have become substantial enough that service providers can lower actual inference prices while maintaining economic viability. Lower prices stimulate more inference demand, leading to more duplex computing power, which in turn enhances security.
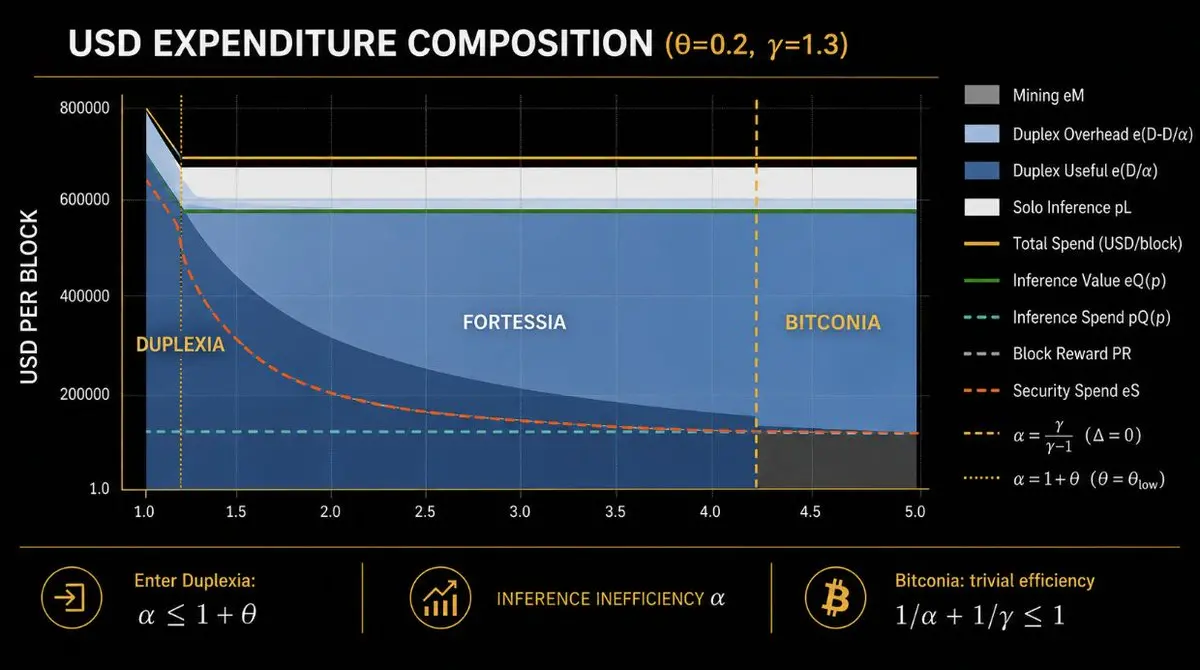
Block rewards can subsidize useful work, reshape inference prices, while continuously breaking the link between economic security and reward budgets. In other words, AI labs adopting Pearl could significantly accelerate AI demand, thereby initiating a flywheel effect through the Jevons Paradox.
Miracles Require Evidence
In May of this year, Together AI (@togethercompute) launched a Pearl-powered Gemma interface with discounts exceeding 25%—the clear reason being that they are mining Pearl with a 2:1 kernel integration. Together has indicated plans to expand its Pearl-powered product lineup and may pass some of the emissions directly to customers.
Read that again. The reason you can buy cheaper inference today is that the GPUs generating those tokens are simultaneously mining Pearl.
Pearl itself is also operating a production-grade inference platform compatible with OpenAI on distributed Pearl GPU computing power. This platform currently offers open-source weight models, billed in standard prepaid dollar amounts. Today, AI goes in, PRL comes out. The ultimate bullish scenario is this cycle closing: PRL goes in, AI comes out.
I would say Pearl has already stepped into Fortessia. Commercial duplex work already exists. What has yet to happen is the more challenging task: duplex work becoming the dominant marginal producer across the entire network.
Pearl Token Economics
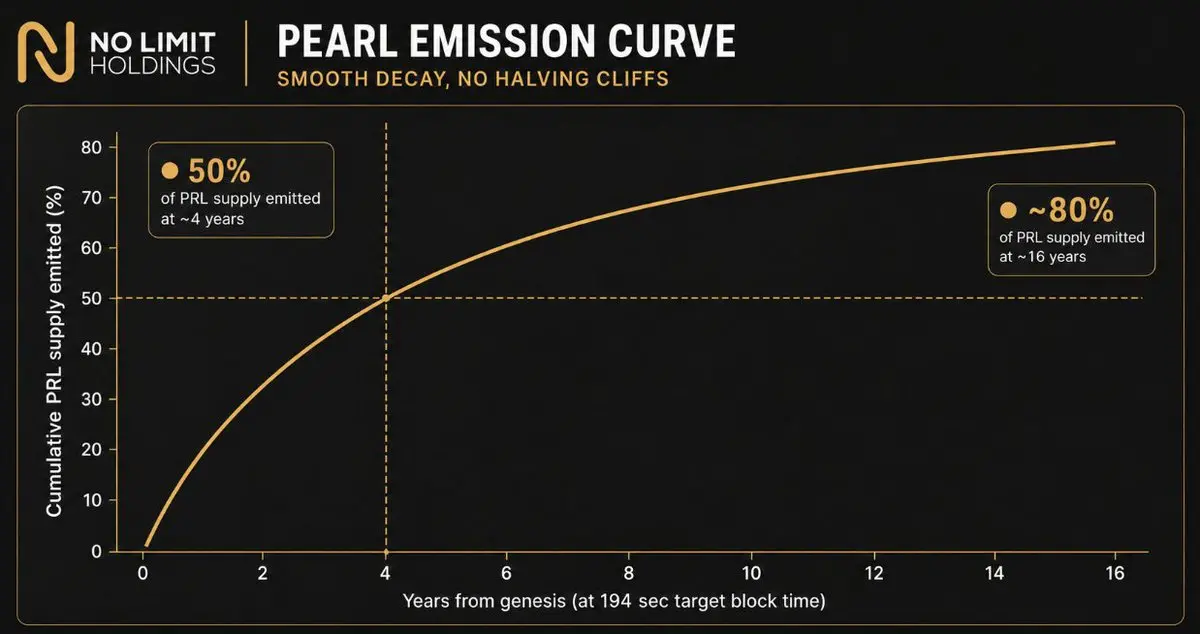
Pearl is a fork of Bitcoin. The supply has been redefined (cap of 2.1 billion vs. 21 million), and the fixed four-year halving has been changed to a smoothly decaying emission curve per block. Aside from these mainly cosmetic changes, the token economics should be very familiar to you.
About half of all PRL is planned to be issued before block 650,226 (approximately four years based on the target block time), after which the issuance will continue to decline, leaving a long limited tail.
The Virgin Mary’s Conception and the Defense of "Solidification"
Solidification is crucial for "monetization." Given our existing understanding of future-oriented design and the benefits of upgradability (just look at the tensions arising from Bitcoin's lack of quantum resistance today), this may sound counterintuitive; but for crypto assets as a store of value, solidification is paramount.
Historically, solidification has spared Bitcoin from being captured by special interests and from unpredictable mutations. It has also minimized bug risks, establishing a narrow and predictable foundation that allows institutions to build financial infrastructure under the premise that rules will not change beneath their feet. For example, the current war around Ethereum's emissions is a prime case.
Most importantly, solidification creates the robustness of currency: it makes the supply cap and issuance rules permanent, mathematically indisputable, without requiring continuous trust in core developers. This prevents future political interests, mining cartels, or corporate wills from altering the rules. The enormous coordination costs required to change a solidified network ensure its resistance to state-level coercion or regulatory capture.
If we truly want to create a decentralized, AI-supported currency, solidification is essential.
I believe Bittensor has permanently lost its qualification to be "AI currency" at this point. It could be an AI coordination layer, incentive network, or smart contract platform, with value still flowing to $TAO. But a currency asset that changes in response to political and market pressures is not hard currency.
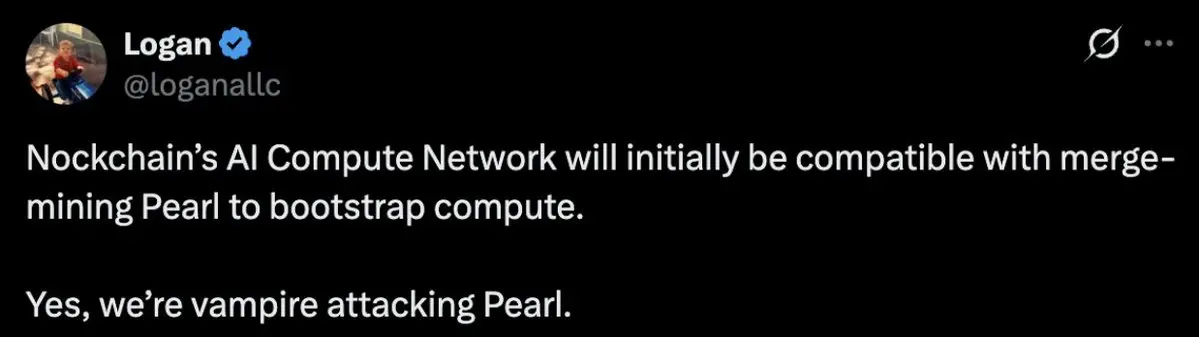
Other competitors turning to MatMul for "useful work proofs" also cannot simply become AI currency. For example, a PoW chain named Nockchain (@nockchain) uses ZK proofs to validate different PoW puzzles and recently announced a shift to MatMul puzzles for its miners. Its newly established "National Compute Company" aims to position Nock as a tokenized version of computing power, a type of AI currency.
But you can't just wake up one morning and declare yourself to be AI currency. So, the 126,000 blocks before the shift (over 50% of the token supply) are not AI currency, but those after the shift are? What is the difference from an asset that has built its currency identity on AI work from the genesis block? The answer should be obvious.
With Pearl, institutions can build on the assumption that the currency core will not mutate beneath their feet.
Fairly speaking, Pearl has not yet solidified. It is a chain only a few months old, with planned floating-point upgrades, still evolving server integrations, a future market concept, and other active protocol work. To say it has already solidified is premature.
But Pearl has a deterministic issuance schedule and a framework that could ultimately converge to a narrow, stable currency core. The condition is: as key AI compatibility issues are resolved, the pace of upgrades must slow down. If Pearl becomes a permanently governed scientific project, my argument for "AI currency" would not hold.
The Passion of Bitcoin
Economic singularities also have Hawking radiation. The most ironic aspect of studying Pearl is that you will eventually realize what it takes to solve Bitcoin's long-term security budget problem.
When all 21 million BTC are mined and block subsidies cease, Bitcoin's network fees will be far from sufficient to incentivize continued block production. Of course, it is estimated that the last Bitcoin will not be mined until 2140, so this issue seems far off. But that is a false hope. The same pressures will actually arise with each halving; Bitcoin has repeatedly escaped this throughout its history—because rising prices continually reinvest capital into mining.
Today, fees account for only about 0.7% of miner income. Miners rely heavily on block rewards for subsidies. The table shows that, with BTC prices unchanged, as subsequent halvings lead to a decrease in block subsidies, miners' profitability will face immense pressure.
In other words, miners' sustainability entirely depends on Bitcoin prices perpetually rising. Optimistically, this is a virtuous cycle: higher BTC prices attract more miners to join the network, generating more computing power, thus bringing more economic security to the network.
In a competitive mining market, expected mining revenues will ultimately be competed down to near the production costs of marginal miners. When Bitcoin prices rise, the dollar value of block rewards increases, attracting more computing power until difficulty and competition compress these excess profits. Historically, this has shown a correlation between BTC prices and computing power.
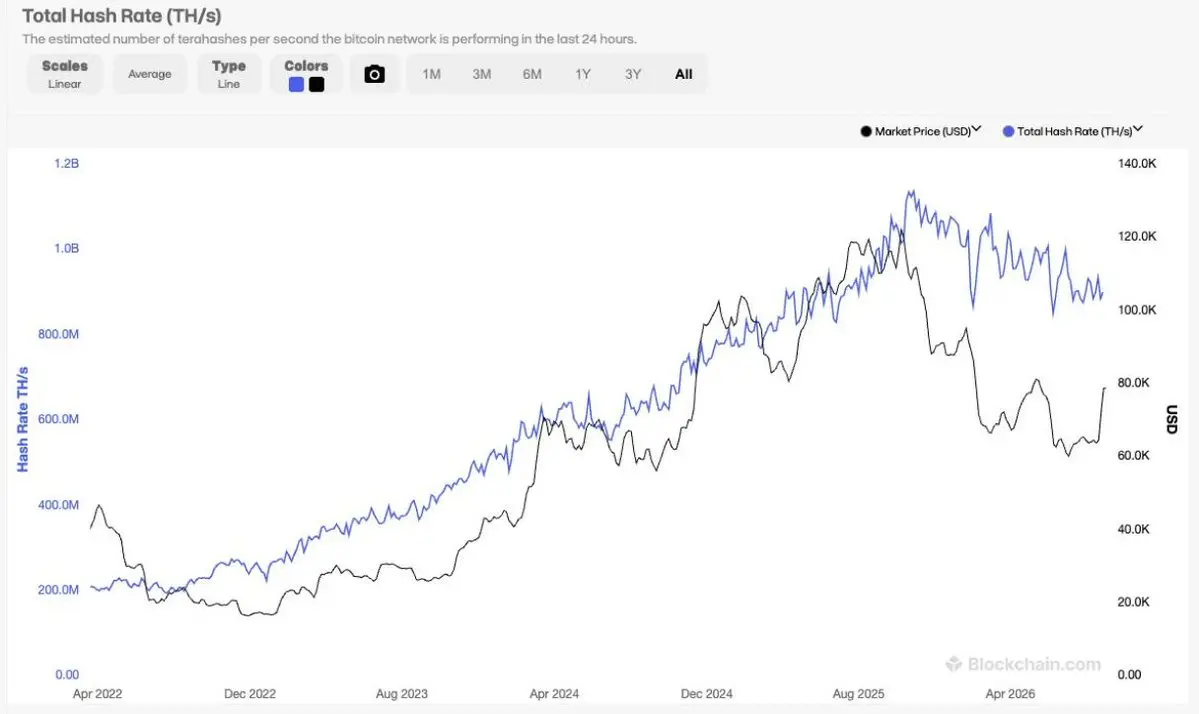
However, Bitcoin's computing power is currently in a long-term decline.
The rise of AI has created another outlet for trapped energy… AI computing power. Miners are increasingly shifting from mining Bitcoin to providing AI workloads. In practical terms, this means they are shutting down ASICs, filling their data centers with GPUs, and then renting those GPUs to AI companies. Bitcoin miners are becoming landlords. The most notable example is actually the former Ethereum miner CoreWeave—it shifted to AI after "The Merge," but this trend extends far beyond just them.
Among publicly listed Bitcoin mining companies (IREN, Core Scientific, Applied Digital, TeraWulf, HIVE, Bitdeer, Riot, Cipher, Cleanspark, MARA, etc.), by 2028, AI workloads are expected to contribute over 70% of their revenue, while in 2024, this proportion is less than 2%.
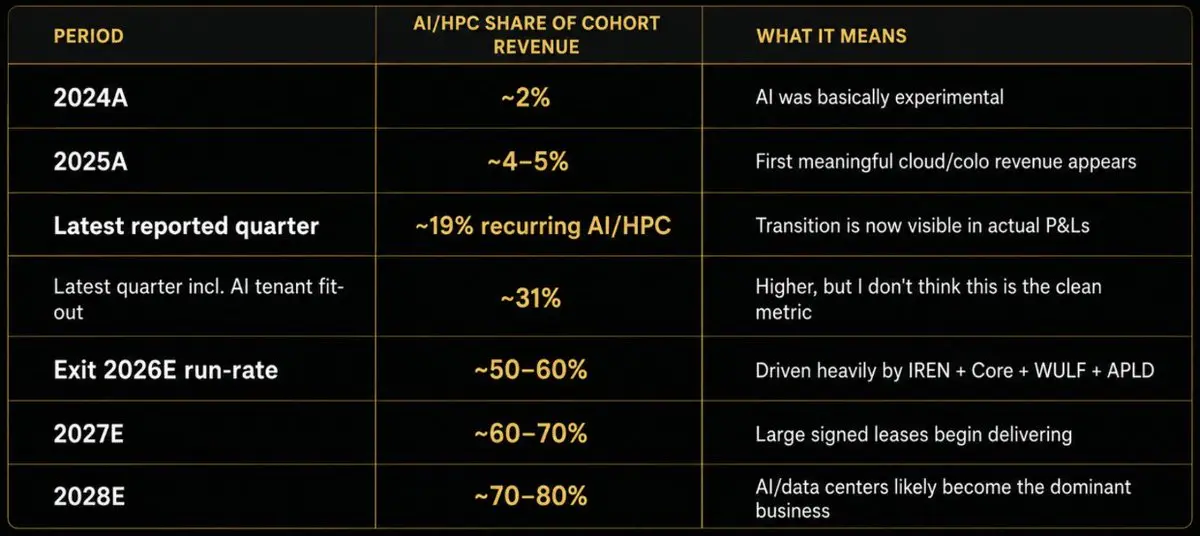
The evidence is in their public disclosures. In 2025, IREN generated only $16.4 million in AI cloud revenue out of a total revenue of $501 million; Core generated $65.4 million in hosting revenue out of $319 million total revenue; HIVE generated about $10 million in HPC revenue out of $115 million total revenue; TeraWulf generated $16.9 million in HPC revenue out of $168.5 million total revenue.
Large traditional mining companies also had essentially 0% AI revenue in 2025: MARA $907.1 million, CleanSpark $766.3 million, Riot $647.4 million, Cipher $223.9 million, all from Bitcoin mining and adjacent traditional businesses, not AI.
By this year (2026), significant differentiation has already emerged. From the revenue structure, Core and TeraWulf are no longer truly Bitcoin mining companies. Core reported that HPC hosting accounted for 77% of its revenue in the first half of 2026, reaching 83% in the second quarter; TeraWulf reported that 71% of its revenue in the second quarter came from HPC leases.
IREN is even more dramatic. The company’s current goal is to achieve over $4 billion in AI cloud ARR by the end of 2026, with about 85% of that goal already contracted as of July.
Considering the overwhelming backlog of signed AI contracts (over $135 billion), this transformation will be fully completed by 2028.
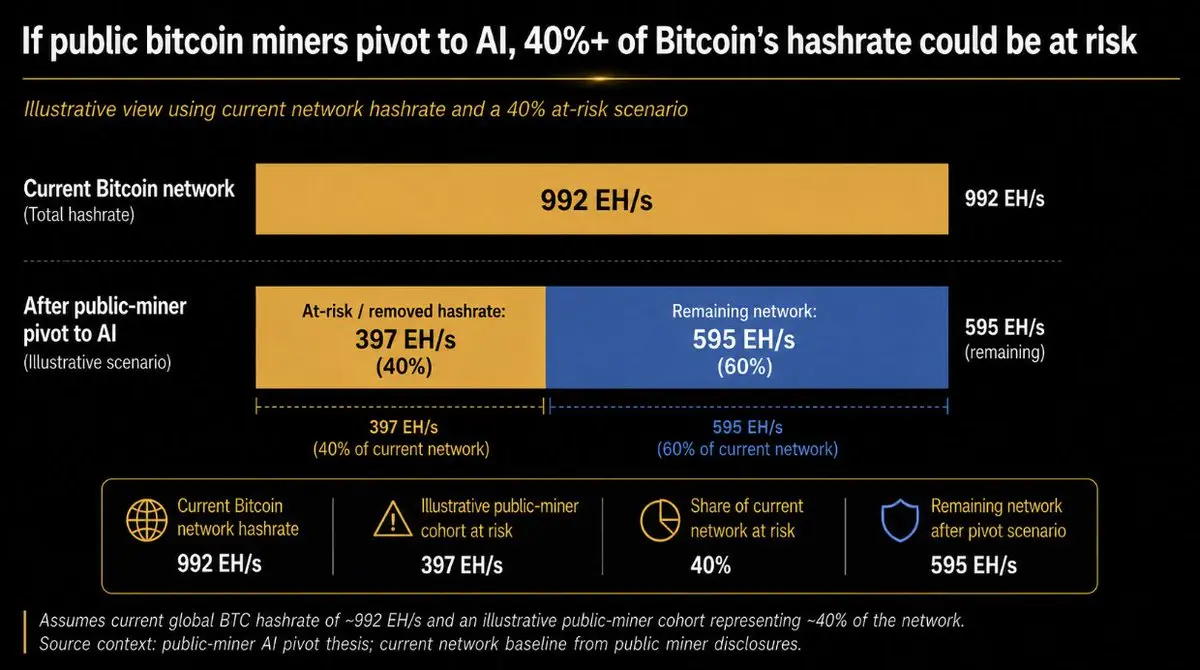
If all publicly listed Bitcoin mining companies continue the trend of shifting to AI, Bitcoin will lose nearly 40% of its current computing power.
This will distort the previously strong incentive mechanism of the Bitcoin network. In the past, when the price of Bitcoin fell, miners would exit due to unprofitability, leading to a decrease in hash rate, which would subsequently adjust the mining difficulty until it became profitable again, resulting in a recovery of hash rate and a rise in Bitcoin price.
This time, the situation is different: even if the price of Bitcoin rises, these miners cannot easily return to the network—because they have become landlords holding long-term leases (usually over 10 years) for AI tenants. Therefore, I expect that even if the price of Bitcoin rises, its hash rate will stagnate or even decline. This is why I say that Bitcoin's hash rate is in a long-term decline: the shift of miners to AI is sticky.
These trends illustrate the structural differences of the Pearl 2:1 model. The main economic benefit for Pearl miners comes from providing AI services, while PRL is merely incremental. If mining expenses approach zero, a customer who has already paid for GPU and electricity for inference services has almost no economic reason to stop producing Pearl work, even if PRL emissions become less valuable. Turning off Pearl does not substantially save anything.
Bitcoin does not have this luxury. Its miners exist because Bitcoin pays them to exist. When rewards no longer cover machine and electricity costs, the machines shut down. The useful hash rate of Pearl can remain online because there are already people needing that computation. This means that protecting Pearl's physical hash rate may be much stickier than Bitcoin's dedicated mining rigs.
Ascension
The trillion-dollar question is: how much should this thing be worth? In my view, Pearl's market opportunity is extremely vast, and its Total Addressable Market (TAM) is even larger than Bitcoin's. Let me elaborate.
Today, Bitcoin's hash rate is about 920 EH/s, while Pearl is at 24 EH/s. This cannot be directly compared because the underlying working algorithms are different—it’s like comparing horsepower and kilowatts. To correctly compare Bitcoin's hash rate with Pearl's hash rate, we need to delve deeper and compare the implied power consumption of all hardware protecting their respective networks.
With Bitcoin's overall network power intensity at about 18.3 J/TH (based on current ASIC hardware), 920 EH/s translates to about 16.8 GW of continuous load, or approximately 147 TWh per year. For Pearl, we can map the 24 EH/s network to about 320,000 GPU equivalents, with a GPU chip power consumption of 112 MW; then, applying a 1.55x increase to cover host systems, cooling, networking, and data center expenses, we arrive at about 174 MW at the meter, or approximately 1.5 TWh per year.
Under these assumptions, Pearl's current power footprint is only about 1% of Bitcoin's.
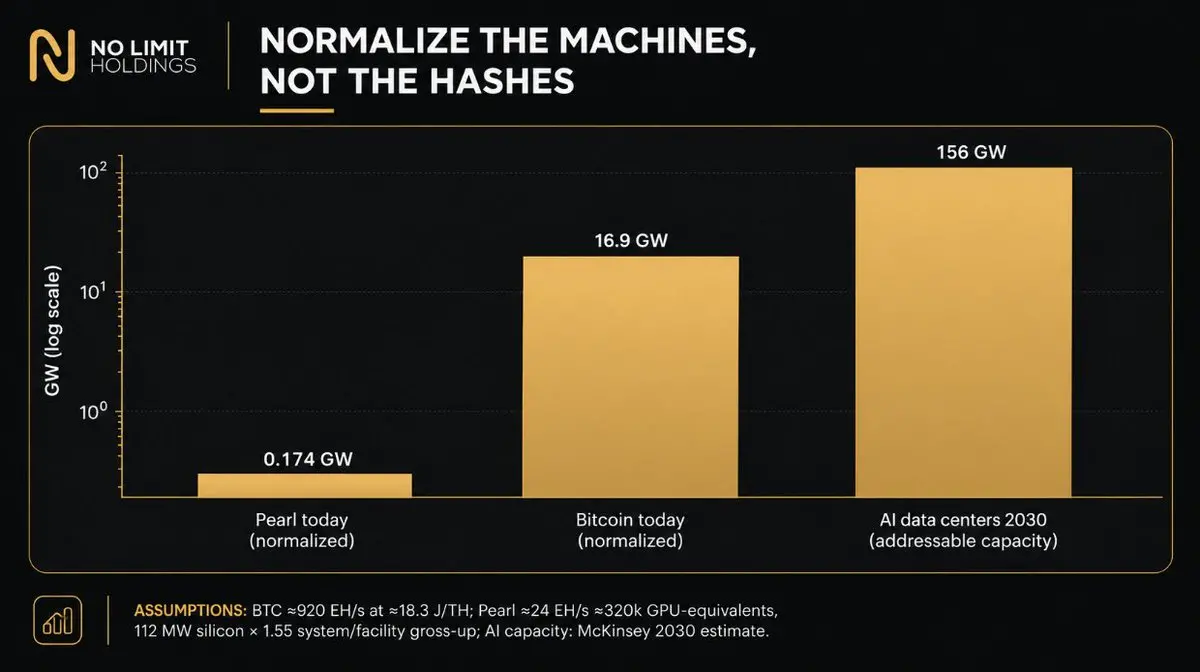
A historical reconstruction of Bitcoin's power shows that around 2014-2015, its footprint was about 0.17 GW—that was about five to six years after its inception. Pearl reached that level in just four months, 18 times faster. This illustrates the advantage of inheriting an existing infrastructure footprint without having to build from scratch.
Speaking of infrastructure footprint, from this point on, the numbers start to heavily favor Pearl. Just as Bitcoin's security TAM is based on the installed capacity of ASICs and the associated power consumption, Pearl's security TAM is based on the global installed capacity of GPUs and the power consumption that comes with it.
McKinsey predicts that by 2030, AI-related data center capacity will reach about 156 GW. This power pool will be more than nine times Bitcoin's current power footprint. If expenses are low enough, Pearl can recruit existing machine stock without having to subsidize a dedicated hardware setup from scratch.
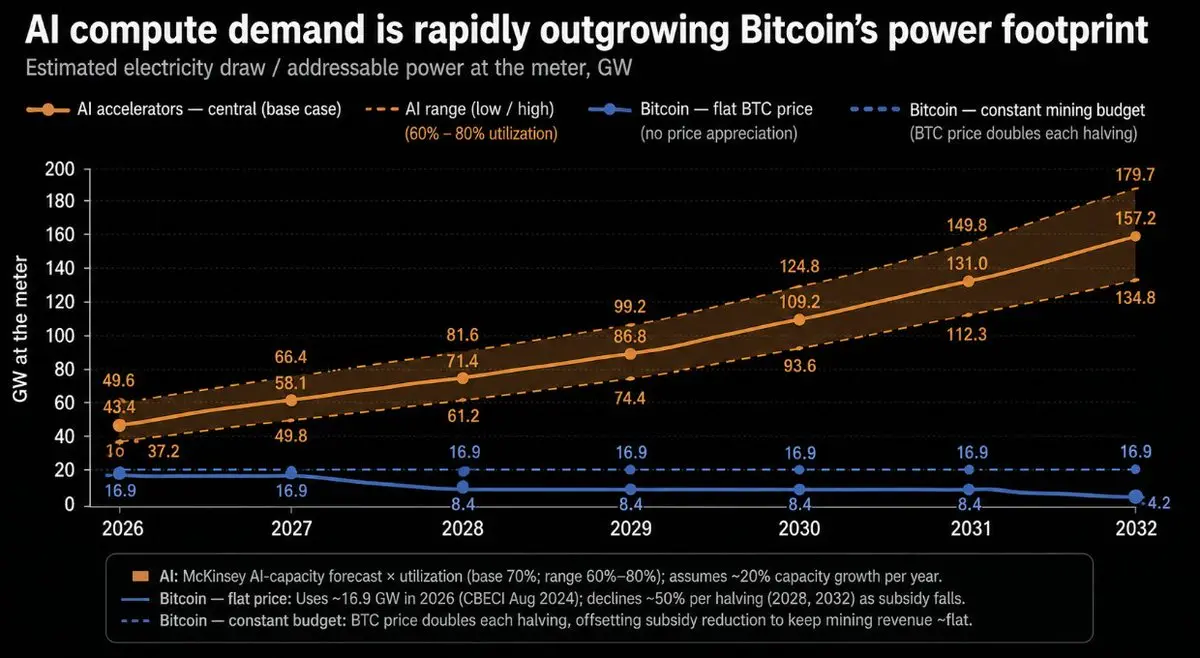
It is evident that the power pool available to protect Pearl's network is much larger than Bitcoin's.
"Bitcoin Singularity" and so on, up to this point.
Decentralized crypto assets can only have one. Why would you use a chain with second-rate security for value storage?
You would only want to use the most secure one. And Bitcoin's economic black hole is evaporating.
From another perspective, it’s ASIC capital expenditure vs. AI capital expenditure. Would you prefer to hold a decentralized currency protected by ASIC capital expenditure, or one protected by AI capital expenditure? (By the way, the latter is the largest capital expenditure construction in human history.)
Since 2013, based on the revenue history of Bitmain, it can be estimated that Bitcoin ASIC cumulative capital expenditure is about $34.5 billion. Meanwhile, Goldman Sachs currently estimates that by the end of 2026, global AI cumulative investment will reach $1.8 trillion—of which about $1 trillion will be in 2026 alone.
This is a gap of over 50 times. The scale of AI deployment each year is approaching 30 times the total historical ASIC capital expenditure of Bitcoin.
Data center capital expenditure is expected to reach $3 trillion to $6.7 trillion by 2030.
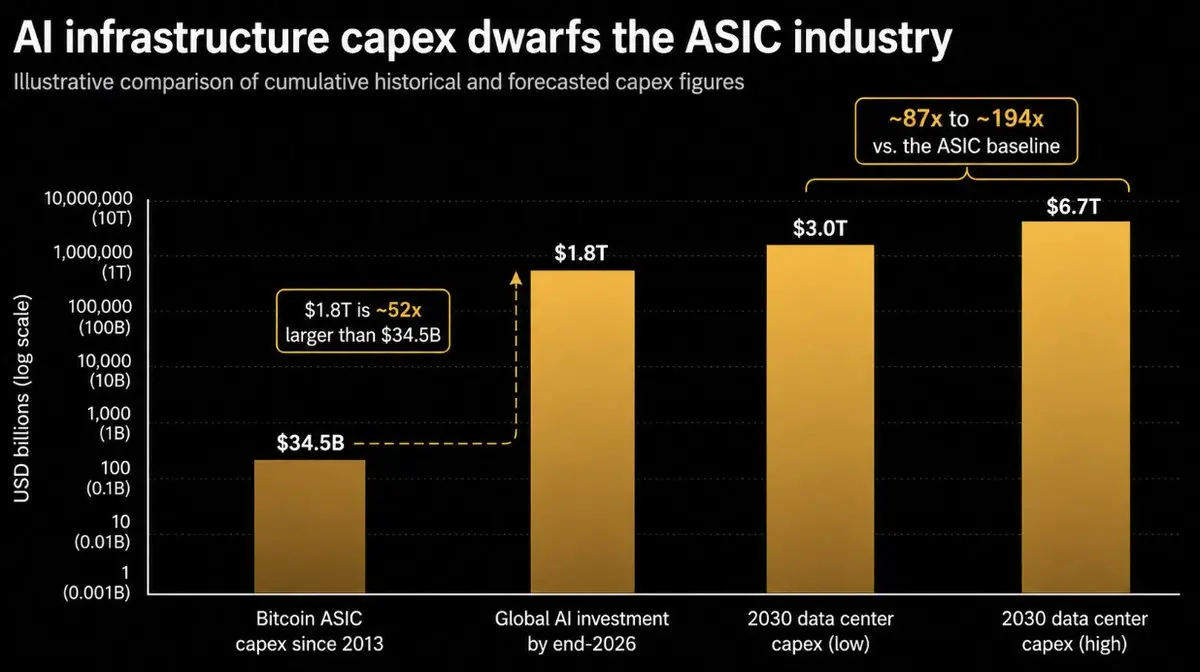
This further widens the forward-looking capital expenditure gap to nearly 200 times. So, can Pearl be 200 times more secure than Bitcoin?
Unfortunately, it’s not that simple. 100% of Bitcoin ASIC capital expenditure is used to protect the network because that hardware has no other use besides mining Bitcoin. However, AI capital expenditure will clearly not be 100% used for mining Pearl, but the TAM itself says it all: Pearl only needs to attract 0.5% of the recently forecasted AI capital expenditure to surpass the total Bitcoin ASIC capital expenditure.
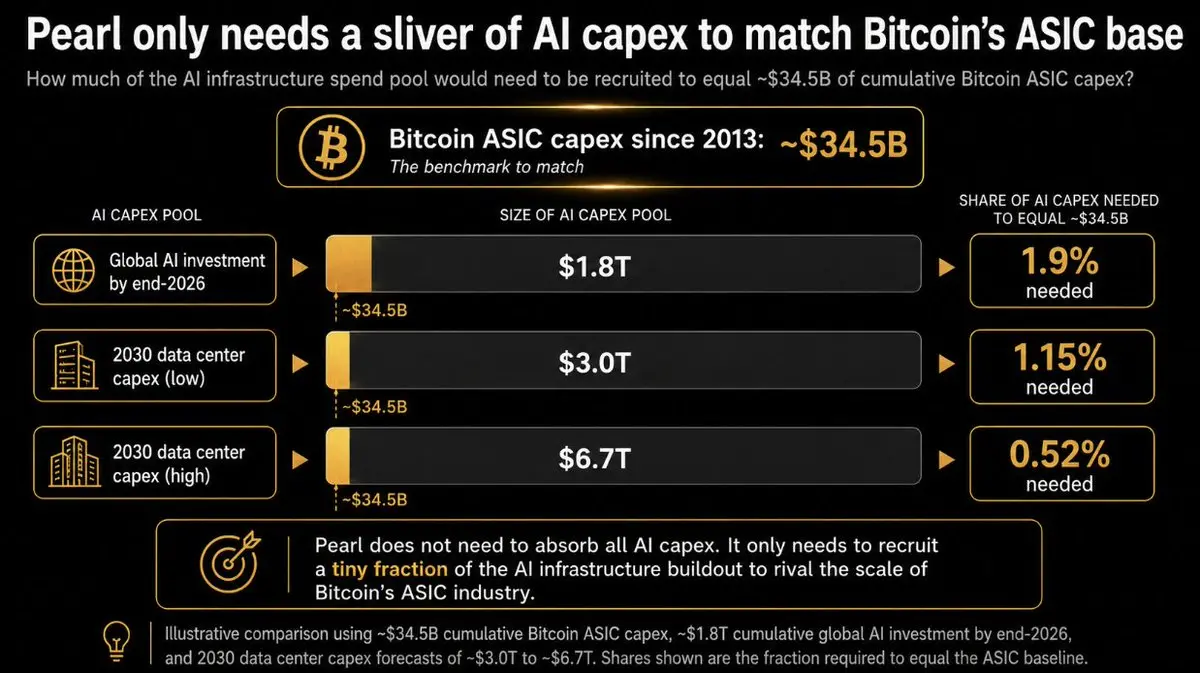
This is quite lethal for Bitcoin. I don’t have a crystal ball, but in a world where Pearl has more hash rate, more power consumption, and more capital expenditure to protect it, what will happen to Bitcoin? That would be a true "seeing God" moment for maximalists.
If Pearl successfully achieves its mission of being a "decentralized AI-backed currency," the investment opportunities within it are self-evident. It will replace Bitcoin and become the hardest currency ever created by humanity.
Financialization of Hash Rate
Pearl's ambition is to become financialized hash rate. Currently, AI goes in, and Pearl comes out. But Pearl's long-term goal is to deeply embed itself in the AI economy, making the reverse also valid: Pearl goes in, and AI work comes out. This closes the loop.
Pearl's white paper clearly describes a future market: it can match supply and demand for hash rate and ultimately settle hash rate contracts natively. In that world, Pearl is not just a mining reward; it becomes the monetary foundation of hash rate.
This is important because it creates endogenous demand for Pearl. Inference service providers mine PRL; AI clients acquire or spend PRL; this token connects heterogeneous hash rate pools into a financial unit. Pearl as "AI currency" is no longer a meme but becomes a real market structure.
Revelation
So, how much should Pearl be worth? There are two related valuation methods.
Store of Value (SoV) currency premium (i.e., "AI Bitcoin")
Hash rate monetary foundation
SoV (Store of Value)
The clearest bullish logic is: Pearl, as another proof-of-work/value storage reserve asset, begins to gain a currency premium. You don’t need it to replace Bitcoin to achieve exaggerated returns from the current base (though it could potentially do so). The race for a new SoV has begun; institutional allocators are increasingly diversifying away from Bitcoin in search of alternative value storage assets.
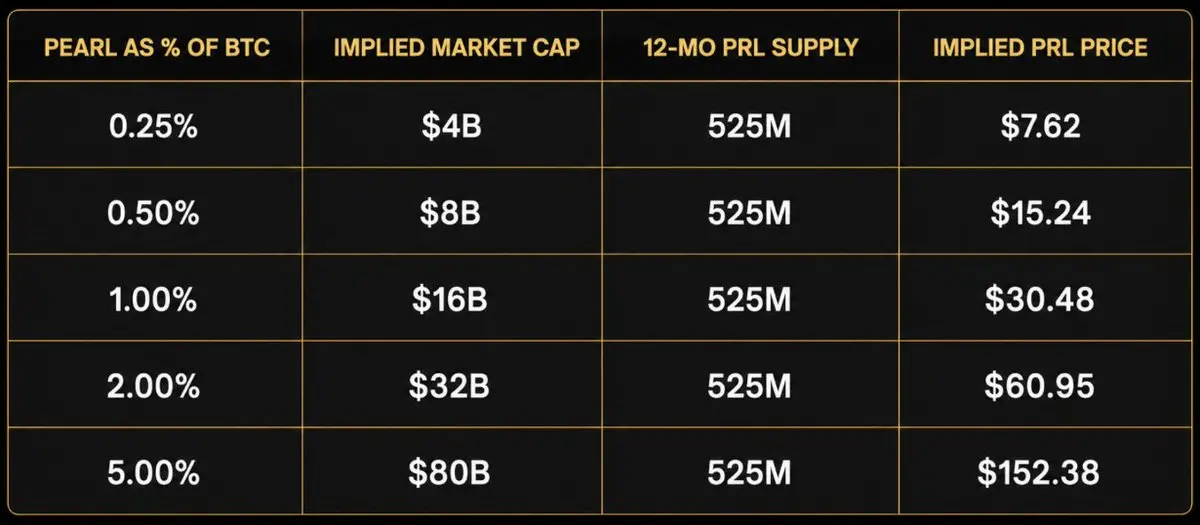
Zcash ($ZEC) is a ready reference because it demonstrates how quickly an alternative SoV asset can transition from "interesting niche" to a significant proportion of Bitcoin's monetary value when the market finds a differentiated narrative. ZEC has risen as a promising alternative to Bitcoin due to privacy and quantum resistance factors; as of late August 2026, ZEC's market cap is about $13-14 billion, while Bitcoin's is about $1.56 trillion—about 1% of Bitcoin. Pearl's current market cap is only about $70-80 million, and it is entirely possible for it to follow a similar trajectory. If Pearl reaches 1% of Bitcoin's market cap, that corresponds to a fully diluted valuation of about $16 billion, or $7.61 each, which is 30 times the current price.
However, Pearl is still an infant PoW blockchain. Currently, less than 15% of the total supply has been mined. Therefore, for medium to short-term investments, the fully diluted valuation is the wrong denominator for valuation. Assuming about 525 million coins in circulation at Pearl's one-year mark (about 25% of the maximum supply), if Pearl reaches 1% of Bitcoin's market cap in its first year, that actually means $30.50 each—117 times the current price.
If Pearl succeeds, it should be able to become one of the top ten crypto assets.
Hash Rate Monetary Foundation
S&P Global predicts that revenue from AI inference infrastructure alone will grow from $101 billion in 2025 to $532 billion by 2030.
If Pearl deeply embeds itself in the inference economy, then a considerable proportion of this hash rate should ultimately be priced, collateralized, prepaid, or settled in PRL. The key question is: how much PRL monetary foundation is needed to support a certain scale of hash rate activity? And how much will that make Pearl worth?
Fortunately, we have a simple formula:
Required PRL monetary foundation = Annual hash rate GMV priced in PRL ÷ Token circulation velocity
The key variable is the token circulation velocity. Can we accurately estimate it?
In the case of Pearl, the circulation velocity equals the holding days of the hash rate inventory.
For example, if the AI economy settles $25 billion in computing power business annually in PRL, how many days of future computing power expenditure does the ecosystem hope to stockpile in PRL form at any given point?
The formula is the same:
PRL monetary base = Annual computing power GMV × Average inventory days ÷ 365
In other words:
Circulation speed = 365 ÷ Average inventory days
A circulation speed of 20 times means the market holds about 18 days of computing power expenditure in PRL; 10 times is about 37 days; 5 times is about 73 days; 2 times is about six months; 1 time means the market holds an entire year's computing demand as monetary inventory.
So, what circulation speed should be used to value Pearl? We can first look at a few analogous markets.
Starbucks is a massive closed-loop stored value economy. In fiscal year 2025, about $15.2 billion in stored value cards and member balances were redeemed, while the average stored value/member liability was about $1.74 billion. This means an annual turnover of about 8.8 times, or that at any point in the system, there is about 42 days of purchasing power parked.
Airline miles are at the other extreme. Delta Airlines had an average deferred revenue liability of about $9 billion in SkyMiles in 2025, while the miles redeemed that year were about $4.46 billion, implying a turnover of only about 0.5 times, close to two years of stored purchasing power. Delta itself has stated that historically, most newly issued miles are redeemed within two years.
In the middle of this range, we can also look at BTC and ETH—they both provide guaranteed accommodation and native settlement for block space within their respective networks. Both have similar circulation speeds, with Glassnode reporting daily speeds of 0.0100 and 0.0103, roughly translating to an annual turnover of 3.7 times (about 100 days of inventory).
This creates a fairly broad but economically reasonable range for Pearl.
At one extreme, PRL is essentially a payment channel: customers buy PRL five minutes before initiating a reasoning request, spend it, and the service provider sells it immediately upon receipt. The circulation speed could be very high.
At the other extreme, PRL becomes more like "computing power inventory": reasoning service providers keep it as working capital, customers prepay for future workloads, service providers use it as collateral, enterprises hold it according to contractual computing power needs, and large AI companies directly retain the portion of PRL they naturally produce. At this point, the circulation speed would collapse to 1–5 times.
Ultimately, the line between "computing power inventory" and "currency" will begin to blur.
Computing Power Forward Curve
Another variable that will affect how much computing power inventory people want to hold is the forward curve of computing power itself.
This market barely existed a year ago and has now begun to financialize. Silicon Data (@Silicon_Data) now publishes standardized GPU forward curves up to 36 months; Ornn (@OrnnExchange) publishes spot indices and forward quotes based on transactions; Kalshi has launched a market-implied computing power forward curve covering H100, H200, B200, and other accelerated hardware.
Currently, most standardized curves are in a flat to backwardation state. Silicon Data's July curve shows that the 36-month prices for B200, H100, and A100 are about 8–15% lower than spot prices, reflecting market expectations that supply growth and hardware updates will lower unit computing power costs over time. Kalshi (@Kalshi) also shows that B200 computing power is in backwardation, while the older Hopper curve is noticeably flatter.
Such data should push Pearl towards a higher circulation speed.
For example: If I expect computing power to be cheaper in six months, why would I want to stockpile six months of future computing purchasing power today? I would rather hold onto dollars to earn returns and buy PRL when I actually need computing power.
But this lacks nuance. We need to flip the curve over.
Travis Good (@IridiumEagle) from Ambient (@ambient_xyz) recently shared a great chart pointing out that long-term contract computing power prices are in contango, while spot prices continue to be soft.
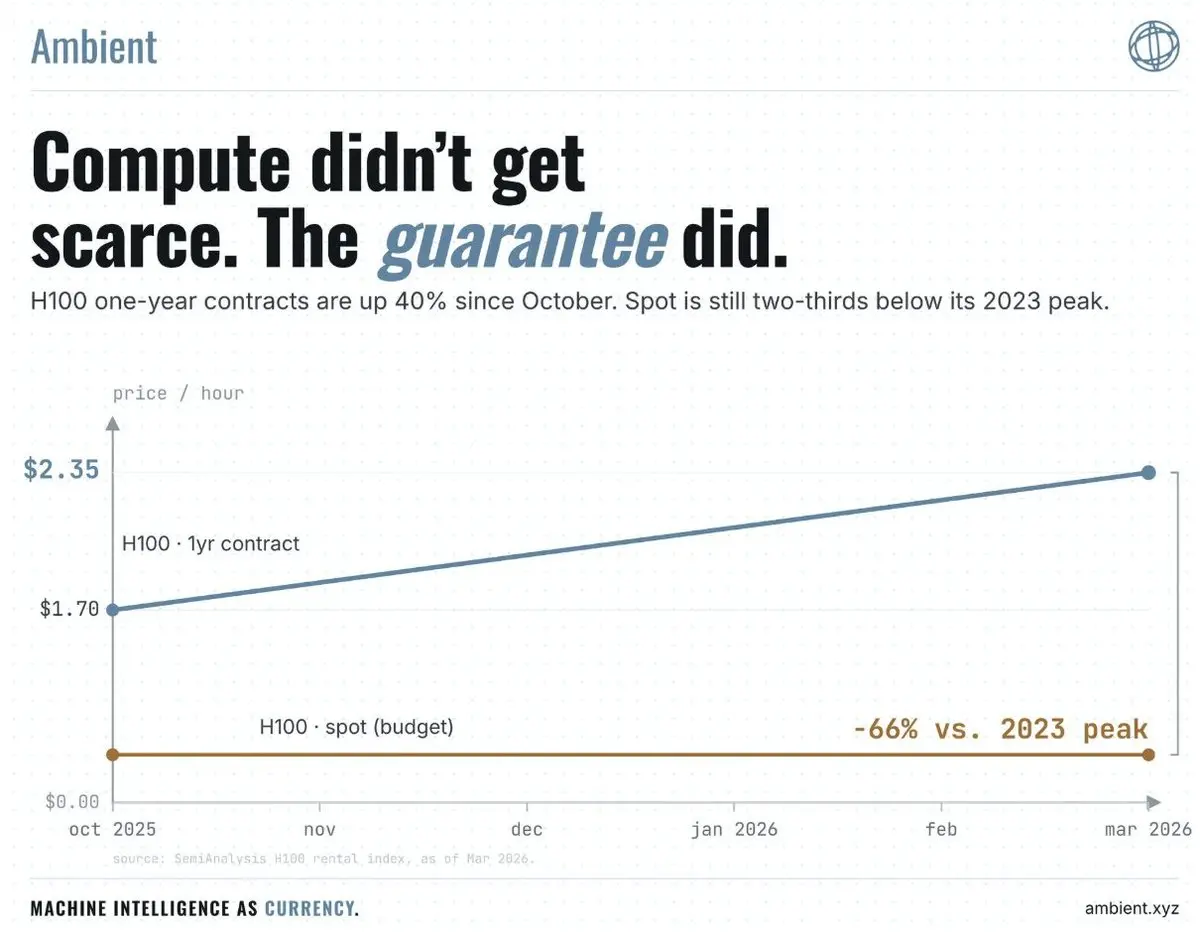
The "guaranteed computing power acquisition" market may enter a sustained contango due to power scarcity, reasoning demand outpacing GPU supply, or large manufacturers beginning to consume every newly added accelerator card, preventing them from reaching the spot market at all. If future computing power is expected to be significantly more expensive than today, then locking in future purchasing power suddenly becomes valuable. Buyers should be willing to lock in prices, prepay for computing power, reserve capacity, or hold any asset that gives them reliable future access rights.
A contango computing power curve will enhance the value of "holding PRL to lock in future purchasing power."
This should lower the circulation speed of PRL.
Thus, the forward curve becomes one of the most important variables determining how much PRL users want to hold.
Bitconia → Fortessia → Duplexia is also a circulation speed curve
This is where the Pass framework becomes relevant again.
In the Bitconia phase, almost everyone is essentially an independent miner. Miners purchase GPUs and power to produce PRL.
PRL is something miners produce specifically to monetize, and there is almost no structural reason to hold onto it. Useful work is negligible, computing power settlement is negligible, and the circulation speed should be extremely high.
As Pearl enters Fortessia, useful reasoning service providers begin to enter the network. This fundamentally changes balance sheet behavior.
A useful miner like Together AI does not rely on PRL to pay GPU bills—its reasoning customers have already paid for the underlying computing power. PRL becomes incremental revenue generated alongside normal business operations.
Such miners do not need to sell every Pearl they mine.
As useful miners increase their share of network computing power, the reflexive selling pressure of "mine and run" should decrease accordingly. At the same time, this type of business naturally has future computing liabilities: contracted customers, reserved clusters, forward capacity needs, and working capital needs. PRL begins to become an asset worth holding rather than an asset that must be immediately exchanged for fiat currency.
Circulation speed decreases.
By the time we reach Duplexia, the relationship is completely reversed. AI companies are no longer just casually mining a bit of Pearl; Pearl is becoming part of the commercial pipeline of the computing power economy itself.
Service providers earn it, customers spend it, the market settles with it, contracts can be priced in it, service providers hold it to meet future obligations, and customers hold it to meet future workloads.
This means that the circulation speed of Pearl should not be treated as a static assumption. As Pearl moves towards success, the circulation speed itself should decrease.
The same process that drives adoption and raises computing power GMV should also raise the amount of PRL the ecosystem is willing to stockpile against that GMV.
Therefore, as Pearl transitions from Bitconia to Duplexia, it may simultaneously gain two valuation multipliers:
More computing power settled in PRL × The turnover of each dollar of PRL becomes slower.
This is why the monetary base can grow much faster than the computing power GMV itself.
A schematic Pearl maturity curve:
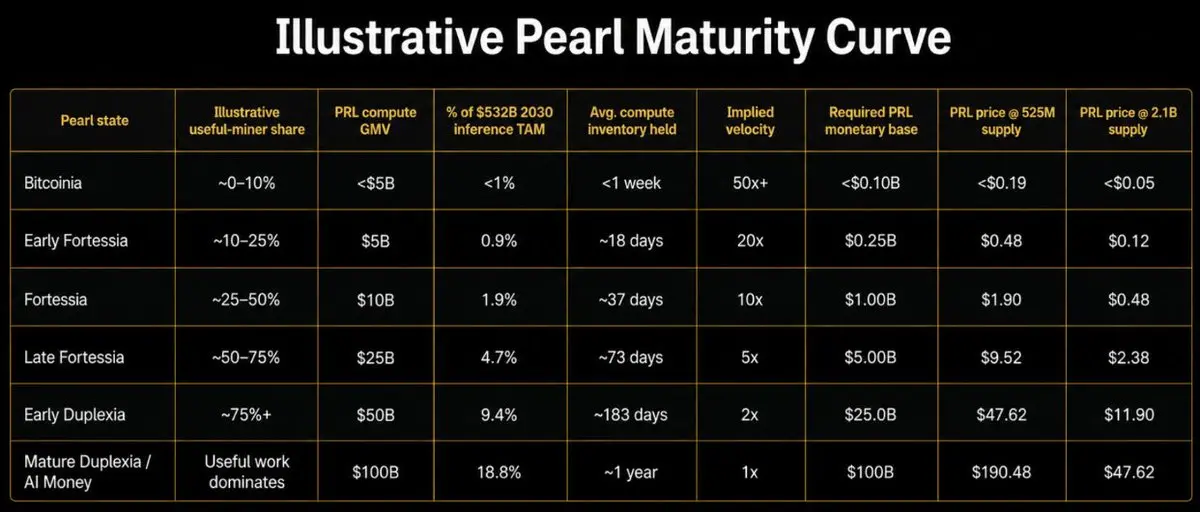
You can see how dramatic the valuation changes can be when GMV growth and circulation speed decline occur simultaneously.
For example, moving from an annual computing power GMV of $10 billion with a circulation speed of 10 times to $50 billion with a circulation speed of 2 times: the underlying computing activity only grows 5 times, but the required monetary base jumps from $1 billion to $25 billion—25 times.
We can also break down the two variables to see the complete sensitivity range:
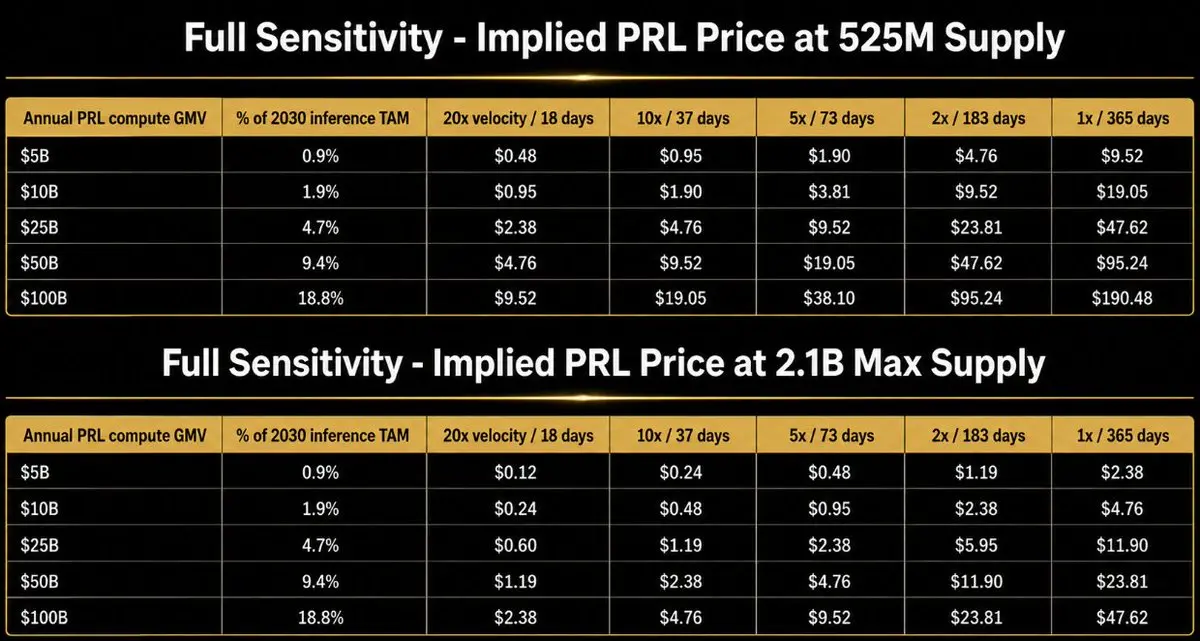
If Pearl is just providing another payment channel for tens of billions of dollars in spot reasoning, then this computing power valuation is not particularly exciting. At $5 billion GMV and a circulation speed of 20 times, it only supports about $250 million in monetary base, which translates to about $0.48 per unit.
If Pearl enters Fortessia and begins to support hundreds of billions of dollars in computing power while service providers hold several months of PRL inventory, the numbers move into the $5–25 billion monetary base range, translating to about $10–50 per unit based on a one-year supply denominator.
And if Duplexia really happens: useful miners dominate, PRL settles a significant proportion of the global reasoning economy, enterprises hold six to twelve months of computing purchasing power, and service providers increasingly treat PRL as working capital or reserve assets—then we enter a monetary base of over $50–100 billion, corresponding to a target price of over $190.
At low circulation speeds, the two frameworks begin to converge. If AI companies are willing to hold PRL for a year or longer because it is seen as durable future purchasing power, collateral, and reserve assets, then this behavior itself is a monetary premium.
That is Duplexia.
The Final Temptation
Pearl has already completed the hardest part: the low-overhead 2:1 kernel. This is a significant innovation that only Pearl possesses, giving it a real chance for widespread adoption.
But the work is not finished.
Today, Pearl's PoUW consensus still runs on the W7A7 integer quantization scheme. You can think of it as only performing matrix multiplication on integers. This works, but the cutting-edge of AI hardware is increasingly optimized around low-precision floating points. Floating-point numbers support decimal places and are more precise than integers, while cutting-edge large models rely on floating points.
The goal of Pearl's next hard fork is to support the most advanced low-precision workloads without forcing them down the existing integer adaptation path.
This is Pearl's crucible. Pearl cannot demand that the AI industry freeze itself in a numerical format that happens to be convenient for Pearl. Pearl must pursue the AI technology stack rather than the other way around.
Fortunately, the team already has a draft proposal for native floating-point PoUW. Pearl Improvement Proposal No. 3 (PIP-3) replaces the current INT protocol with an FP protocol built around FP8 quantization. This change is not easy, and its successful execution is a prerequisite for meaningful adoption by major manufacturers and new cloud vendors.
If this step is successful, the next bottleneck will be integration.
Once the floating-point integration is online, Pearl needs to conquer closed-source adoption. Currently, to "Pearl-ify" a model and perform 2:1 operations on it, Pearl Research needs to be deeply involved to quantize the model into their specific INT format. This has limited the adoption scope to open-source labs—clearly, no closed-source lab would allow Pearl Research to enter their models to assist with quantization. Once the floating-point is online, "Pearl-ifying" will become a universally applicable plug-and-play kernel that any lab can integrate on their own, no longer requiring assistance from the Pearl team. Open-source inference has brought Pearl to Fortessia, while integration with closed-source giants will elevate Pearl to the throne.
One reason I take this technical roadmap seriously is the team behind it. Pearl was founded by Omri Weinstein (@WeinsteinOmri), Ilan Komargodski (@komargodski), and Idan Sugerman, whose backgrounds span academic cryptography, Nvidia (@nvidia), VAST Data, machine learning, and zero-knowledge systems. Rafael Pass—one of the top academic cryptographers researching PoUW economics—has also been directly involved in this project. Despite the team's high transparency, Pearl itself is fairly launched, with no VC token allocations and no investors hanging over it.
The adoption of Pearl is not predetermined
The argument for Pearl does not require everything to go smoothly, but it does require that a few things do not go catastrophically wrong. Here are the key risks on the adoption path:
Costs do not continue to decline. A 5% reduction is already impressive, but 5% is not zero. If Pearl's floating-point protocol cannot keep up with FP8, FP4, new NVIDIA architectures, new quantization schemes, and the next winning inference kernel, problems will continue to accumulate. If enabling Pearl mining significantly degrades core products, AI companies will not care how clever this mechanism is. PRL subsidies must always be worth more than the lost throughput, engineering burden, and operational risks.
Useful miners have never managed to become marginal producers. Together AI has proven one extremely important thing: real customer inference can mine Pearl. This kills the argument that "useful mining is just theoretical," but it does not prove that useful miners will dominate the network. The entire natural selection argument hinges on the idea that useful miners ultimately have lower actual costs than synthetic miners. If this never happens, Pearl becomes much less interesting.
Pearl has never solidified. The protocol has not yet solidified. In fact, there have already been five activated mainnet consensus changes between the genesis and August 11. Most notably, the recent soft fork supporting mixture of experts (MoE) proof took effect at block 71,935 but subsequently led to miners exploiting vulnerabilities to forge computing power and win disproportionate block rewards. Fortunately, the issue was discovered, and the MoE upgrade was temporarily disabled at block 91,630, 41 days later. Other protocol changes include the rank penalty soft fork activated at block 96,251 and the subsequent salt noise seed hard fork at block 99,000. Pearl needs to use this period to break things, fix them, complete the architecture, and ultimately earn the qualification for solidification.
Come "Pearl-ify" with me
Bitcoin has proven that useless computation can become currency.
Pearl is betting that useful computation can become harder currency.
If costs approach zero, useful AI service providers will become structurally dominant miners because someone has already paid for the computing power. Block rewards become subsidies for inference. Lower inference prices create more demand, more demand creates more duplex computing power, and more duplex computing power makes Pearl harder—ultimately, the assets produced by these machines will become the means to purchase the assets produced by these machines.
AI produces currency. Currency purchases AI. The loop closes.
By then, Pearl will be the currency of computing power.
And if this currency network, protected by global AI infrastructure, ultimately proves harder to attack than that protected by warehouses full of single-purpose ASICs, then Michael Saylor may indeed be right.
There is no second best.
He just might have chosen the wrong one.
Come "Pearl-ify" with me.
Acknowledgments
Many thanks to Pearl Research Labs (@prlnet) for their feedback and guidance during the writing of this study. Their academic insights have shaped this article into what it is today.
Also, thanks to @tulipking—my dear friend and confidant—whose suggestions and feedback profoundly influenced the tone and style of this article.
Disclaimer
The views expressed in this article are solely those of the author and are for informational purposes only. They do not constitute investment, legal, tax, or other professional advice and should not be relied upon as the basis for any investment decision. Specific companies, protocols, tokens, or sectors mentioned in the text are for illustrative purposes only and do not constitute an offer or solicitation to buy or sell any securities, tokens, or other assets. The author is an investor in No Limit Holdings, a venture capital firm that invests in blockchain and digital asset-related businesses; No Limit Holdings and/or its affiliates may hold positions in certain companies, protocols, tokens, or sectors discussed in this article or have other economic interests in them.
 Risk warning

Popular articles