Not investment, but collecting monthly rent: Binance's $100 million stake in another account of Circle
 Core Viewpoint

 Circle used $100 million in equity to secure a priority position on Binance's shelf—this position requires a renewal fee every month.
Author: Gu Yu, ChainCatcher
On the evening of September 22, Circle submitted an 8-K filing to the SEC revealing a significant transaction: Binance purchased 1,237,011 shares of Class A common stock from Circle at a price of $80.84 per share, totaling $100 million, with the transaction completed on September 17. The same document also disclosed that both parties signed a new five-year commercial agreement to replace the old agreements from November 2024 and August 2025—Binance will promote USDC on its platform, while Circle will pay Binance monthly incentive fees based on the amount of USDC held.
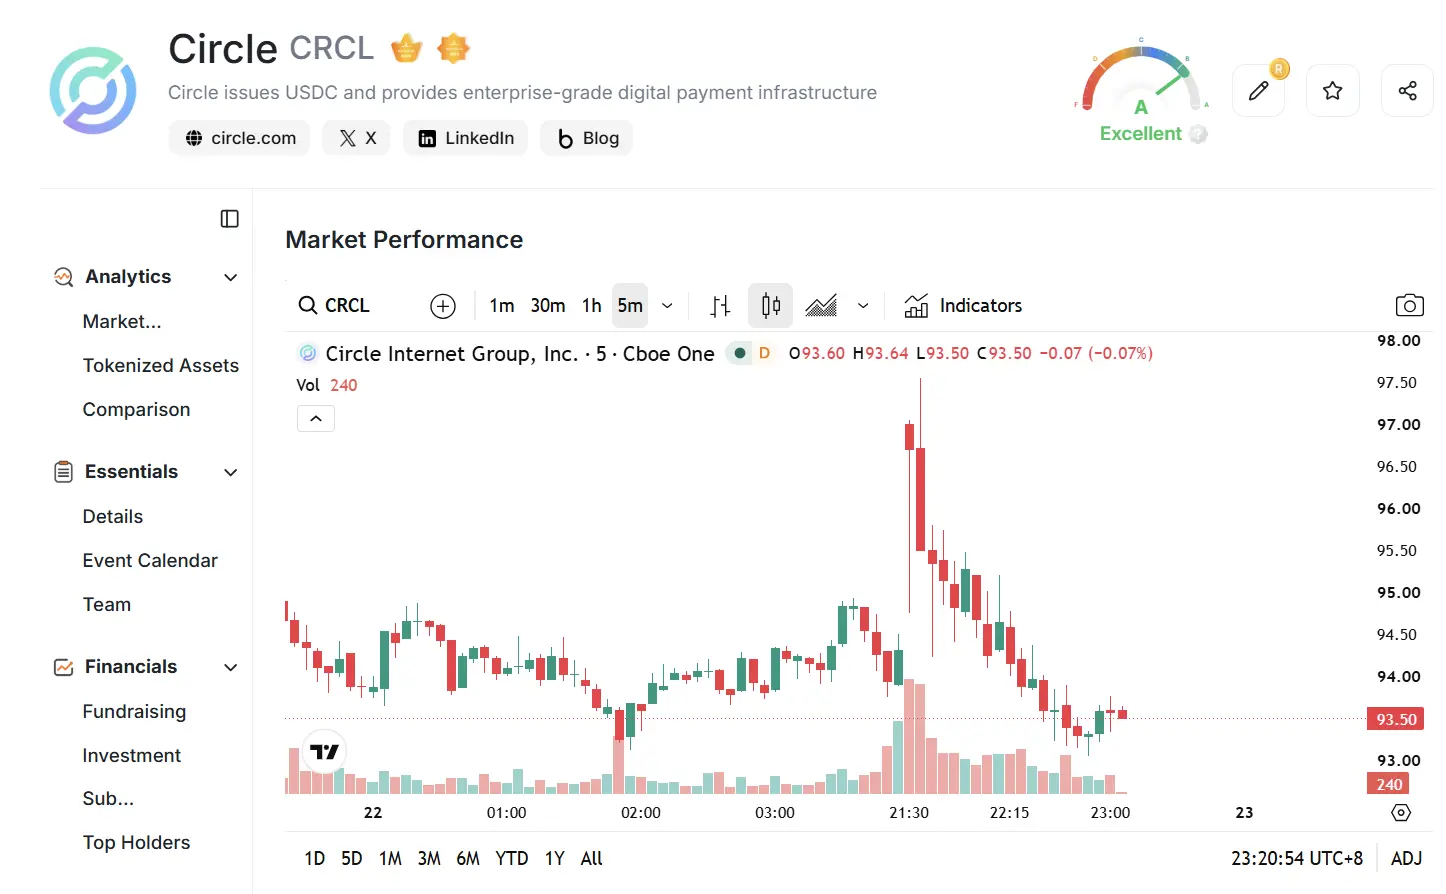
However, the market's initial reaction was not positive. On the day the news was disclosed, CRCL briefly surged before falling to $93, down about 1% from the previous day's closing price.
The lukewarm response is understandable. Because this is not a $100 million transaction; it is a transaction about "shelf space."
Discount, Lock-Up, Conditional: An Unusual Equity
The terms of this investment emphasize "long-term" in almost every aspect.
Based on the closing price of CRCL at $85.09 on September 17, the price of $80.84 represents a discount of about 5%; if measured against the closing price of $94.49 on September 21, the discount expands to about 14%. Binance has committed not to sell, transfer, pledge, or hedge these shares for up to two years after the closing, with exceptions only for transfers to related parties, board-approved acquisitions, or legal compulsory disposals; during the lock-up period, voting rights belong to Binance.
In other words, what Binance has acquired is an equity stake that essentially means "as long as the cooperation continues, it cannot leave"—if the relevant commercial arrangements are terminated early as per the agreement, the transfer restrictions will also be lifted. The equity serves as collateral for the commercial agreement, not as an independent investment.
The real focus is on the agreement itself. According to the 8-K, the monthly incentive fees paid by Circle to Binance are based on "the amount of USDC held through Circle's modular smart contract wallet infrastructure services," with the fee rate undisclosed. This aligns with the structure of the agreement from August 2025; in the original agreement from November 2024, Circle had paid Binance approximately $60.3 million as a one-time upfront fee. Circle's 2025 annual report disclosed that distribution costs related to Binance increased by $152.1 million that year.
In 22 months, the same pair of partners has rewritten their agreement three times. The distribution price of stablecoins is being repeatedly re-priced.
Who is Paying Whom
The public narrative places Binance's investment at the forefront, but the direction of the cash flow is the opposite.
From an accounting perspective, Binance is a shareholder; from a cash flow perspective, Binance is the payee. Circle pays Binance promotional fees while making Binance its shareholder. This structure has precedent with Coinbase—being a co-founder of USDC, Coinbase has consistently taken half of the interest on USDC reserves.
The numbers further illustrate the weight of distribution costs. Circle's total revenue and reserve income in the second quarter was $701 million, a year-on-year increase of 7%; distribution and transaction costs were $410.4 million, of which $324.6 million flowed to Coinbase. The revenue after deducting distribution costs (RLDC) was $289 million, with a profit margin of 41.2%. During the same period, the reserve return rate dropped to 3.5%, a year-on-year decrease of 66 basis points.
This means Circle's profit formula is extremely fragile: Revenue = Volume × Reserve Yield - Distribution Costs. Volume growth can be offset by declining interest rates or consumed by channel splits. Compass Point gave Circle a neutral rating when it first covered the company in June 2025, citing its highly concentrated distribution partners in crypto-native institutions—now this list has added another exchange, which is also a shareholder.
Binance has its own calculations. The exchange launched BUSD with Paxos in 2019, once pushing its market cap to $20 billion, but was halted from issuing by the New York State Department of Financial Services in February 2023, subsequently turning to Hong Kong's First Digital's FDUSD—whose circulation has now shrunk to about $350 million. The failure of its own stablecoin route has made "promoting someone else's dollar" a realistic choice.
The Position of USDC: Second Place, But the Foundation is Hardening
In terms of scale, USDC remains in second place: USDT's circulation is about $183 billion, while USDC is around $75 billion, together accounting for about 85% of the approximately $300 billion stablecoin market. However, the structure is changing—ARK Invest's Director of Digital Asset Research, Lorenzo Valente, released a grouped chart on September 9 showing that there were once four stablecoins with a market cap over $10 billion, but now only Tether and Circle remain, with the third place hovering around $6 billion.
On Ethereum, the share gap between USDC and USDT has narrowed from 34.2 percentage points in November 2024 to 17.8 percentage points in September 2026—USDT grew by 22% during the same period, while USDC grew by 83%. In 2025, USDC's adjusted on-chain transaction volume first exceeded USDT, at $18.3 trillion to $13.3 trillion; in the second quarter, this figure reached $14.8 trillion, a year-on-year increase of 151%.
More critically, retention is key. By the end of the second quarter, USDC held on Circle's own platform reached $12.4 billion, a year-on-year increase of 106%, with the average daily weighted share rising from 7.4% in the same period last year to 19.5%. The more USDC stays within the scenarios controlled by Circle, the more the distribution bargaining power shifts towards Circle. This is also why Binance's agreement is based on "the USDC balance in Circle's wallet infrastructure"—Circle is using fee design to guide the increment to its own territory.
And new increments are coming from the other side. Tokenization of stocks is the steepest curve this year: On September 10, Nasdaq announced plans to invest $100 million in Kraken's parent company Payward to jointly promote tokenized stock infrastructure; on September 21, the European Central Bank launched Pontes to support the settlement of wholesale tokenized asset transactions in central bank currency.
For USDC, this is a new demand locked in by regulations. Crypto KOL Kuai Dong commented: "Currently, Binance's US stock business must use USDC for trading and redemption due to compliance, which stimulates the demand for people to first obtain the stablecoin USDC before buying and selling US stocks. Although Binance offers one-click matching, such as allowing orders with stablecoin USDT or platform token BNB, the final trading path must still convert to stablecoin USDC before matching with US stocks on the platform."
In other words, every transaction of tokenized stocks creates a mandatory exchange demand for USDC. USDT and BNB are merely entry currencies on this path, ultimately needing to pass through the USDC gate. When stocks begin to go on-chain, USDC is no longer just a medium of exchange but becomes the default pricing layer of this new pipeline.
The product side is also ramping up. On September 16, Circle's Layer 1 public chain Arc launched its public mainnet, with gas fees paid in USDC, and founding validators include BlackRock, Visa, Mastercard, DTCC, Intercontinental Exchange, and Standard Chartered Bank; on July 10, the Office of the Comptroller of the Currency (OCC) finally approved Circle's national trust bank charter.
"Relying on USDC, Arc, and the infrastructure to reshape cross-border value transfer, Circle has already entered the ranks of the most credible issuers globally," said Binance Co-CEO Richard Teng. "Our $100 million investment and five-year commitment represent a long-term belief." Jeremy Allaire's wording was even more straightforward: "We see a tremendous opportunity—leveraging USDC to expand dollar access and reach new emerging markets."
Emerging markets are the true target of this agreement. The moat of USDT lies precisely there: cross-border transfers on low-fee networks, contract margins, and dollar savings in countries with depreciating local currencies. Circle paying a trading platform with the most emerging market users is equivalent to directly launching an attack on Tether's home ground.
Divergence and Timing: Who is Buying, Why Now for Binance
This investment has been repeatedly interpreted, partly because Circle's shareholder list has been highly topical over the past six months.
Duan Yongping is the most contrasting figure. On July 29, 2025, he clearly stated on Xueqiu: "I don't understand things without cash flow and have no interest in stablecoins." Nine months later, his managed H&H International Investment disclosed its first position in Circle in the Q1 13F filing: 200,000 shares at an average price of $95.41, about $19.08 million, accounting for 0.095% of its approximately $20 billion portfolio. In the same quarter, Dan Bin's Dongfang Hongyuan Overseas Fund also established a position of about 31,700 shares for the first time; on May 5, Dan Bin wrote on Weibo, "Due to a researcher's strong recommendation, I laid out a bit in Circle," and on that day, CRCL briefly surged over 16%.
ARK Invest's rhythm has been more coherent. Its ARK Venture Fund invested in Circle as early as May 2024, continuously increasing its holdings after the IPO, with a peak of about 4.51 million shares; on March 24, CRCL plummeted about 20% in a single day, and ARK's three ETFs collectively bought 161,513 shares; on July 23, when the stock price fell below $64 and breached all major moving averages, they bought another 220,012 shares. Of course, ARK also reduces its positions—on September 14, it sold a total of 142,350 shares from ARKK and ARKW.
Divergence has always existed. SoftBank Group completely liquidated its entire 95,659 shares of Circle (about $10.8 million) in its Q1 13F, publicly stating it wanted to concentrate funds on AI; on the other hand, the California State Teachers' Retirement System (CalSTRS) increased its holdings in Circle by 3,456.8% in Q2. By mid-May, the number of institutions declaring holdings in Circle had reached 485, with 353 increasing their positions and 192 reducing them in that quarter; on September 8, Jeremy Allaire reduced his holdings by 56,200 shares under the 10b5-1 plan, cashing out about $5.5 million.
The divergence of chips is reflected in the stock price: the IPO price in June 2025 was $31, the opening price on the first day was $69, the peak was $298.99, the low on February 5, 2026, was $49.90, and it returned to $94.49 on September 21------still down about 34% over the past 12 months, while the S&P 500 rose 16.5% during the same period. The target average price given by 26 institutions is $104.31, with a high of $243 and a low of $37, showing a divergence that is almost absurd.
Binance entered precisely at the deepest point of divergence. On September 15, the Senate failed to pass a motion to end debate on the CLARITY Act with a vote of 49 to 50, causing CRCL to drop about 11% that day; the next day, the Arc mainnet went live, and the market responded with "sell the news," dropping over 7%; on September 17, the transaction was completed------acquiring a five-year entry at a 5% discount, with an unrealized gain of about $16.9 million as of September 21, but it could not be realized during the lock-up period. On the same day, the SEC also announced a five-year, conditional stock tokenization "innovation exemption."
The motivation is not difficult to read. This exchange announced in July this year that its registered users had reached 323 million; the reserve report in January 2026 showed total reserves of about $155.64 billion, including $47.47 billion in stablecoins; but by August, CryptoQuant analyst Darkfost pointed out that its stablecoin reserves had fallen below $42 billion, hitting a new low since October 2025. The dollars on the platform are draining away, and dollar liquidity is the lifeblood of an exchange.
Conclusion
In recent years, the competition among stablecoins has been understood as a war over reserve transparency and regulatory licenses. Circle secured the OCC license, a seat on the New York Stock Exchange, and the endorsement of BlackRock through this narrative. However, when the circulation of USDC has hovered between $73 billion and $77 billion for more than a year, and every rate cut by the Federal Reserve directly lowers reserve yields, Circle has to admit one thing: Compliance can get you in the door, but it can't sell your goods.
$100 million is not a valuation anchor; it is a channel fee. It cannot buy the growth of USDC circulation, only a priority position on Binance's shelf------and this position requires a monthly renewal fee.
There is only one true standard for testing: Circle's net take rate. If in the coming quarters, the USDC balance brought by Binance indeed rises, but the profit margin after deducting distribution costs continues to flatten or even decline, this transaction is Circle exchanging equity for expensive exposure. Conversely, if USDC truly settles as margin, savings, settlement balances, and the pricing layer for tokenized assets, then Binance will become the first piece of the puzzle for Circle's transition from "interest income tool" to "network."
For Binance, the calculations are much simpler: whether USDC can ultimately shake USDT or not, the promotion fees come in monthly, and the equity has two years left.
In this war of stablecoins, issuers are betting on the future, while channels have already collected the money.
 Risk warning