








Is there any meaning to tokenized stocks without DeFi?
 Core Viewpoint

 Tokens are just barcodes; the market that can withstand the crisis weekend is the core.
Author: Jesus Rodriguez, Co-founder of Sentora
Compiled by: Luffy, Foresight News
Discussions in the RWA industry often begin with a simple vision: take a treasury bond, a fund share, a stock, an invoice, a megawatt-hour, or an hour of GPU computing, and then mint a token that represents it.
Is it useful? Indeed, it is. But is it transformative? Not yet.
It's like putting a barcode on a shipping container and claiming that global trade issues have been resolved. The barcode gives the container identifiable, machine-readable capabilities, but it doesn't magically create ports, cranes, customs, insurance, financing, shipping routes, or distant buyers.
A token is merely an addressable proof of rights, while DeFi is a set of market operating systems. The real question worth discussing is not how many types of assets can be put on-chain, but how many assets can achieve valuation, financing, hedging, trading liquidity, and loss disposal under pressure without needing to hold offline meetings for every transaction.
Tokenization represents the manifestation of rights; DeFi brings actual utility.
Tokenization is just a barcode, not a supply chain
A similar scene has played out in the history of financial markets. The reason mortgages could scale was not simply that paper certificates became electronic records. The true scaling was achieved through the birth of a complete set of operational mechanisms around such assets: credit review, post-loan services, securitization, credit ratings, warehousing financing, repurchase, hedging, clearing and settlement, and loss-sharing rules.
RWA also needs to undergo the exact same evolutionary process.
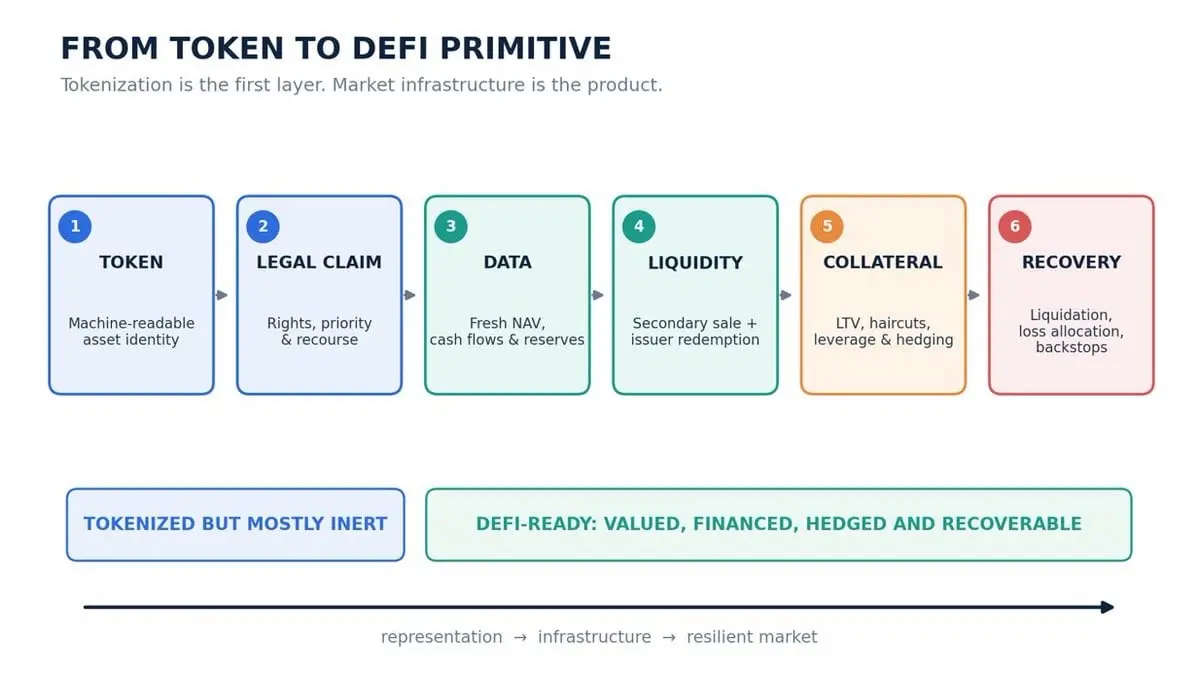
An asset that can adapt to DeFi needs to have six layers: legally enforceable rights, reliable data sources, clear transfer and redemption rules, executable secondary market liquidity, realistic collateral parameters, and trustworthy clearing and loss disposal pathways.
However, most tokenization projects often stop at the first five layers.
There is a simple test to check asset maturity, which requires answering three questions:
- What is the current value of this asset?
- Can the protocol complete an exit for liquidity right now?
- If the first two judgments are completely wrong, who bears the loss?
When smart contracts can deterministically answer these three questions, RWA can truly be considered a fundamental financial component. Until then, it is mostly just a layer of digital wrapping.
The Fourfold Time Clocks of RWA
The deepest technical contradiction lies in the fact that RWA operates under multiple different time clocks simultaneously.
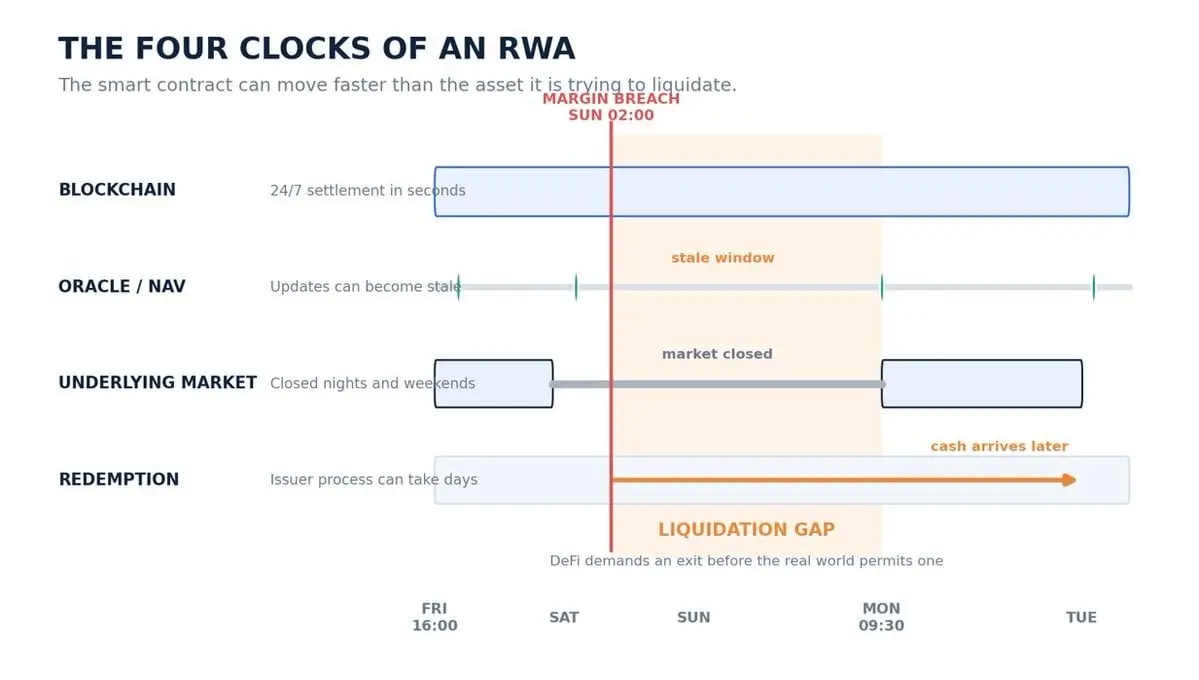
Blockchain can settle in seconds and runs 24/7; oracles may update prices every hour or daily; traditional exchanges close during evenings and weekends; custodians follow banking business hours; and asset redemption processes may take 1 day, 5 days, or even 30 days.
If such a slow-paced RWA asset is used to support the fast-maturing liabilities on the DeFi side, such as stablecoin lending.
This is term transformation, which has been the core model on which banks have operated for centuries: using short-term liabilities to fund long-term slow assets. This model has practical value, but risks must be reasonably priced.
Imagine a scenario: at 2 AM on a Sunday, the asset hits the liquidation threshold. The smart contract can immediately seize the tokens, but the underlying real-world market won't open until Monday, and the issuer's redemption business won't be processed until Tuesday. On-chain liquidation has been completed, while the asset disposal in the real world has just begun.
This creates a liquidation gap, where DeFi demands immediate exit for liquidity, but the real world does not allow it, leading to a time difference between the two.
This gap can lead to counterintuitive results; even if the volatility of treasury bond tokens is very low, the risk when used as collateral may be higher than that of more volatile native crypto assets. The price of ETH fluctuates wildly, but it can be traded around the clock; RWA assets may appear to have stable prices, which could simply be due to a lack of new price markings for several hours. Smooth prices sometimes represent safety, and sometimes just the disguise of outdated data.
Liquidity is an exit channel, not a TVL number
There is also a common misunderstanding about liquidity among the public.
Liquidity does not equal TVL, does not equal the existence of a trading pair, and does not equal the issuer's promise to redeem at net asset value. Liquidity refers to the ability to convert a position into the settlement asset you need at an acceptable discount within the time window allowed by your liabilities.
You can think of it like a crowded theater: the size of the hall cannot determine whether it is safe when a fire occurs; what really matters is the width of the exit channels.
An RWA should have at least three exit paths: selling to other market participants, applying for redemption from the issuer, or borrowing against the asset to delay selling. Each path has different delays, capacity limits, permission restrictions, and potential failure modes.
Market makers willing to take on RWA inventory over the weekend are essentially bridging the gap between two financial clocks. This balance sheet service should be clearly recognized and compensated accordingly.
Therefore, our strategy model should calculate exit value under stress scenarios, rather than the official net asset value on the books. This means the actual realizable price after spreads widen, market makers reduce inventory, redemption queues form, and stablecoin financing costs soar.
The truly important question is not "What was this asset worth yesterday?" but "How much cash can this position actually be exchanged for before the protocol loses tolerance?"
Leverage creates utility, but also sows vulnerability
Tokenization occupies the vast majority of media headlines, but the real economic utility comes from leverage.
Houses become high-value collateral through mortgages; treasury bonds rely on the repurchase market to become foundational market tools; stocks are fully valued only after supporting margin trading, lending, short selling, and hedging.
Once RWA can be used as collateral to borrow stablecoins, it is no longer just a tokenized object, but becomes infrastructure at the balance sheet level. However, leverage is also where hidden assumptions can turn into real losses.
Collateral ratios cannot only reference historical volatility. Discount factors must also consider legal enforceability, the freshness of oracle data, redemption delays, concentration of chips, market maker absorption capacity, custodian risks, governance permissions, and correlations with financing assets.
This leads to counterintuitive conclusions: in certain market environments, the collateral ratio for tokenized treasury bonds should even be lower than that for ETH. It is not that treasury bonds themselves carry higher economic risks, but that their liquidation disposal mechanisms are slower and lack sufficient real-world testing.
DeFi risks are not just the risks of the assets themselves, but the asset risks multiplied by market structure risks.
RWA risk is a relational map
Traditional finance relies on periodic reports and manual upgrade disposal processes to manage risk. DeFi needs something more like an airplane cockpit: continuous indicator monitoring, clear risk thresholds, and automatic responses before the engine bursts into flames.
RWA risk should not be compressed into a simple score, but modeled as a relational map.
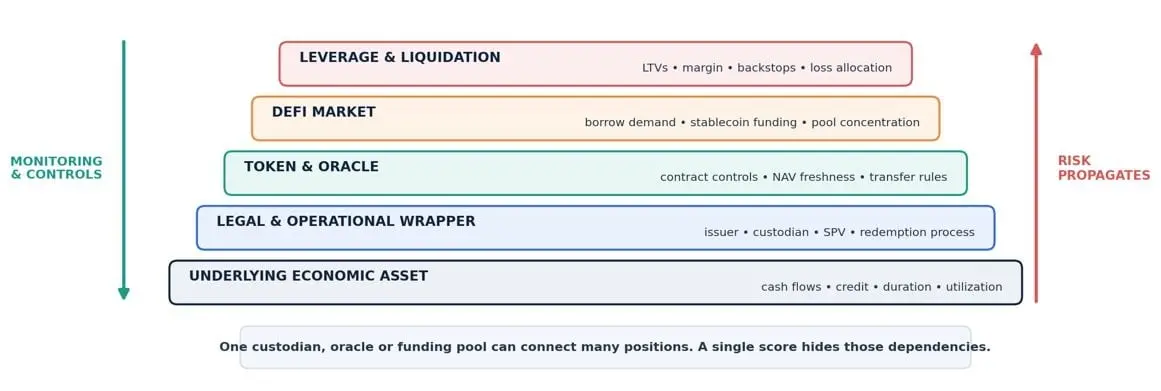
The nodes of the map include underlying cash flows, legal entities, issuers, custodians, oracles, secondary markets, redemption mechanisms, stablecoin liquidity pools, lending protocols, governance keys, and backstop capital; the lines between nodes represent their interdependencies.
Risk failures rarely occur in isolation. A custodian may serve multiple tokens, an oracle may price multiple liquidity pools, and a stablecoin may support a large number of leveraged positions. A small operational failure can propagate through the relational map and ultimately evolve into a liquidity crisis.
Our approach is to integrate asset research, strategy building, continuous monitoring, exposure management, and risk protection into a complete operational closed loop. The system needs to continuously monitor redemption queues, market depth, position concentration, borrowing utilization rates, oracle deviations, reserve changes, cash flow deterioration, and market maker behavior.
The first wave of risk signals often appears off-chain before reflecting in token prices. Waiting for prices to drop before acting is like waiting to see smoke before checking if the wiring is overheating.
Treasury bonds are just the beginning, not the final destination
Tokenized treasury bonds are a natural stepping stone. The product is standardized and easy for the public to understand. Using a metaphor from the internet domain, it is the ping test data packet of the RWA economy: used to check whether custody, minting, redemption, compliance, pricing, and the entire settlement chain can be connected.
However, a financial internet that can only circulate short-term treasury bonds has a very limited landscape. The more worthwhile frontier to explore is computing power and energy assets.
Computing power RWA can represent GPU devices, rental receivables, pre-purchased computing power, equipment utilization revenue, and data center operator revenue rights. It has a completely different set of risks, compounded by equipment financing leasing, commodity pricing, technological iteration depreciation, and actual operational performance. The advent of a new generation of chips can overnight change the revenue curve of GPUs, and its economic aging speed far exceeds that of physical buildings.
Energy assets also face identity definition challenges: does this token represent infrastructure? A power purchase agreement? Megawatt-hours of electricity? Grid capacity? Project revenue? Or green credit certificates? Each requires a dedicated oracle solution and liquidation disposal plan.
DeFi can package slow, locally limited assets from traditional markets, building programmable yield distribution, transparent collateral pools, global distribution channels, and dynamic financing tools. But tokens must accurately map the underlying economic logic. "Backed by energy assets" does not equate to a risk model.
Tokenized stocks and perpetual contracts
Tokenized stocks will become the largest practical test, connecting two massive systems: global stock ownership and native crypto leverage.
The primary question is not "Which stock has been put on-chain?" but "What exactly does the holder own?" Direct stock ownership, revenue rights, structured notes, synthetic tracking products may have similar price trends, but the corresponding voting rights, dividends, corporate actions, redemption rights, and bankruptcy disposal outcomes are entirely different.
This leads to perpetual contracts.
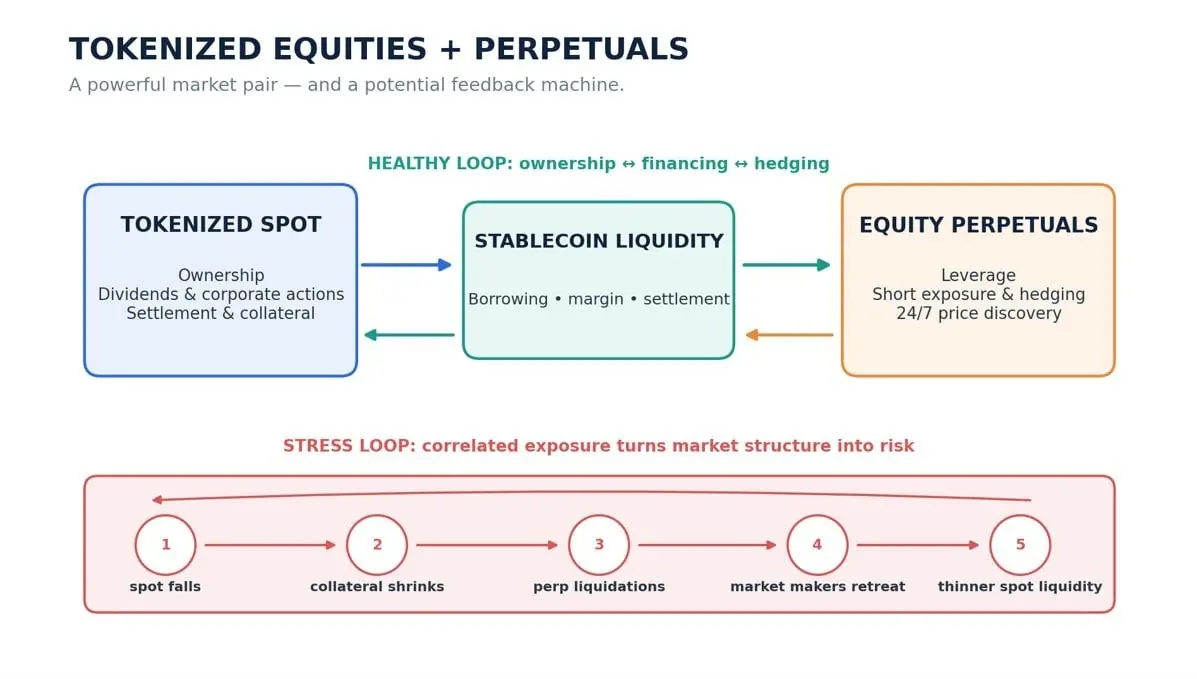
Tokenized spot stocks and stock perpetual contracts should complement each other, just like the spot and futures markets for commodities. Spot anchors ownership, dividends, settlement, and collateral; perpetual contracts provide leverage, short exposure, hedging, and continuous price discovery. The combination of the two can achieve rich market expressions that a single product cannot.
However, both will also generate highly correlated risks.
Imagine tokenized stocks being used as collateral to borrow stablecoins, and the funds obtained are used to open leveraged long positions in that stock's perpetual contract. The underlying US stock market is closed, the token price declines over the weekend, the collateral asset shrinks, triggering the perpetual contract liquidation, and market makers withdraw, further depressing the already thin spot liquidity and lowering prices.
The response plan comes from architectural design: isolating margin domains, setting position concentration limits, dynamic collateral discounts over the weekend, liquidity-sensing oracles, circuit breakers, cross-market monitoring, and clear backstop capital.
High efficiency does not mean no constraints; rather, it means placing constraints at the points in the system where failures are most likely to occur.
Market System Beyond Tokens
So, if there is no DeFi, does RWA still have significance?
Yes, but its value is limited. Tokenization can optimize distribution, settlement, transparency, and investment access. However, the truly significant opportunity occurs the moment assets enter an open programmable capital market: assets become collateral, can obtain financing, engage in hedging, and build various structured strategies.
A RWA truly compatible with DeFi is not at the moment of token minting, but rather when the entire market surrounding it can withstand a weekend of risk outbreak.
This is our core argument. The next phase is not to pile up more RWA token logos, but to build an operational layer that transforms legally effective rights certificates into resilient financial strategies.
The long-term vision is not "everything can be tokenized," but rather that physical production assets can be addressed and called by software, capital can flow continuously between various assets, and risks can be managed at the speed of the market itself.
Tokens are just barcodes. The market is the real operating machine.
 Risk warning
Popular articles





