








Storing "deleveraging," South Korean retail investors fall into "liquidation fear" again
 Core Viewpoint

 The South Korean stock market has significantly corrected, and the AI industry chain is facing multiple pressures such as the memory cycle peaking, poor revenue expectations for OpenAI, high capital expenditures, and retail investor margin calls.
Written by Su Yang Edited by Xu Qingyang
On October 12, the South Korean stock market experienced a significant pullback. The Korea Composite Stock Price Index (KOSPI) closed down 3.65%, at 6384.25 points. The semiconductor sector showed weak performance, with Samsung Electronics closing down 4.39%, at 250,500 Korean won; SK Hynix fell 4.52%, at 1,605,000 Korean won. On the following trading day, October 13, Korean stocks continued to decline, with a temporary halt to programmatic selling during the session.
Looking back, since reaching a high of 9385.59 points on June 22, the KOSPI has dropped nearly 32% over about four months.
This round of decline can be interpreted as a technical adjustment triggered by profit-taking at high levels. However, when the focus shifts from this grand capital feast to the micro-nodes of the AI industry chain, the pressures faced by the market may extend beyond short-term capital withdrawal.
This includes three hidden concerns: first, whether the continued expansion of AI infrastructure investment can smoothly translate into actual revenue and profit; second, the price squeeze of upstream equipment and components is rewriting the investment return expectations of the chip industry; third, whether the high growth rate of revenue from cutting-edge large model laboratories can be sustained.
Once profit expectations begin to loosen, adjustments in high valuations may reinforce the outflow of foreign capital. Coupled with financing transactions and leveraged funds amplifying market volatility in a downturn, this can easily trigger margin calls and lead to passive liquidation, with retail investors' "liquidation alarms" sounding once again.
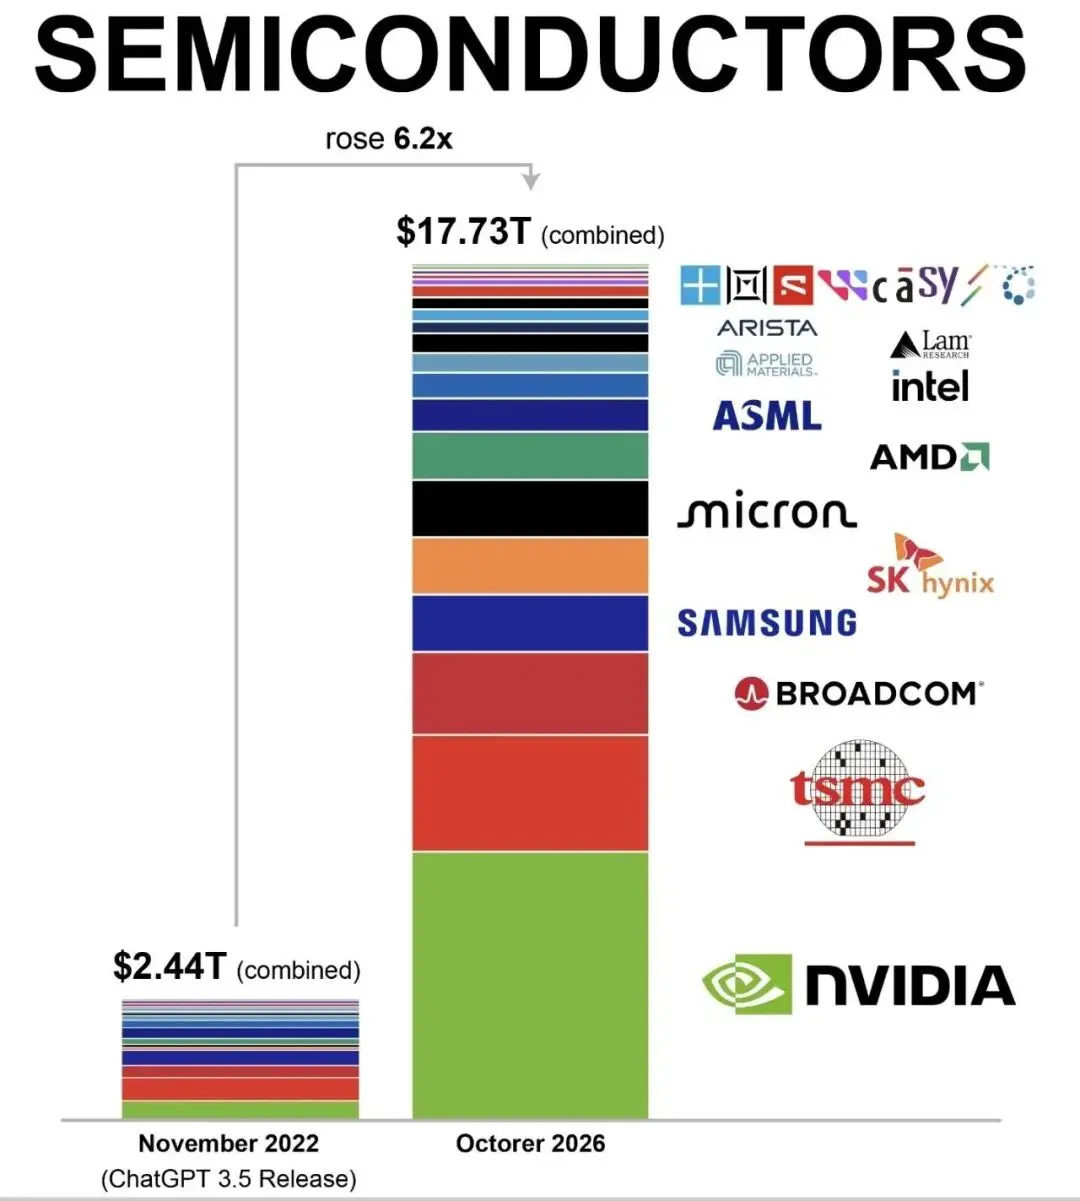
Since the release of ChatGPT 3.5, the total market value of the global semiconductor and AI industry chain has soared 6.2 times, with the chip sector becoming the core winner of this AI supercycle.
01 Anxiety of "Cycle Peaking"
Samsung Electronics' chip factory in South Korea
The recent weakness in the South Korean stock market and the memory sector was ignited by a "stunning" earnings forecast.
On October 8, Samsung Electronics announced its latest third-quarter earnings guidance: the company's consolidated sales for the third quarter are expected to be approximately 195 trillion Korean won (with an estimated range of 194 trillion to 196 trillion Korean won), and the consolidated operating profit is expected to be around 10.74 trillion Korean won (with an estimated range of 10.73 trillion to 10.75 trillion Korean won), showing significant growth compared to the same period last year and landing at the upper end of analysts' previous expectations.
The strong performance is mainly attributed to the sustained robust demand for AI-driven HBM and DRAM. Samsung Electronics and SK Hynix jointly dominate the HBM and DRAM markets, continuously enjoying the structural dividends brought by global AI infrastructure investment.
However, the market did not greet the anticipated cheers.
After the earnings forecast was released, Samsung Electronics' stock price fell in response, dragging down the KOSPI index and semiconductor heavyweights like SK Hynix.
Investors' restrained reaction to the record data, or even their choice to take profits at high levels, is primarily due to a reassessment of the sustainability of the memory boom cycle. Multiple institutions have analyzed that the profit growth rate for the third quarter may have approached a cyclical peak, with fourth-quarter sequential growth expectations slowing to about 8%.
As memory prices rise at a flattening rate and new industry capacity is gradually released, the core question for the market has become, "Will the supply shortage continue until 2028?"
In simpler terms, while everyone used to fear memory shortages, the concern has now shifted to the absence of shortages.
This can be seen as a form of anxiety regarding "cycle peaking," as storage is a highly cyclical industry.
02 "Chaotic" Billing
OpenAI CEO Sam Altman
The "chaotic" revenue calculation standards of cutting-edge laboratories have also been a key trigger for this round of adjustment.
According to reports from the Financial Times and several financial media, as of the end of September 2026, OpenAI's actual annualized revenue is close to $50 billion. This represents a discrepancy of about $20 billion compared to the $70 billion circulated among Wall Street and some media in previous weeks.
In other words, the market had previously overestimated the revenue-generating capacity of cutting-edge laboratories.
The key to this discrepancy lies in the calculation standards—competitors like Anthropic include total sales through cloud partners, while OpenAI only counts its own revenue, which is the net amount after excluding channel sharing. Some primary market investors adjusted OpenAI's data to seek direct comparisons with the two companies, resulting in the $70 billion figure.
After the news broke, on October 8, Eastern Time, U.S. stocks in the semiconductor and cloud service sectors generally declined: Nvidia fell 2.94%; Oracle, which has expectations of computational cooperation with OpenAI, dropped over 6%, closing down 5.48%; Micron Technology fell 4.79%, SanDisk fell 4.90%, and CoreWeave fell 7.77%. The Nasdaq Composite Index's decline widened to 1.25%.
As memory stocks are a core link in the AI hardware chain, the emotional transmission is particularly evident.
According to the Financial Times, as of the end of September this year, OpenAI's annualized revenue was about $50 billion, far below the widely expected $68 billion. Similar situations exist in other AI companies.
On October 9, another insider revealed to Bloomberg that OpenAI expects its annualized revenue to still reach or exceed $70 billion by the end of this year, mainly driven by growth in enterprise business. This "news" somewhat alleviated short-term panic, but the market has raised higher demands for the comparability of AI revenue narratives.
Analysts pointed out that this turbulence largely stems from information asymmetry.
OpenAI's revenue data, as a non-public company, is already sufficient to influence the stock prices of public companies like Microsoft, Oracle, and Nvidia, indicating that it has become an important reference for global AI asset pricing. Brokerage research shows that there are currently no signs of cloud infrastructure vendors reducing capital expenditures.
In other words, the recent brief pullback in the secondary market seems more like profit-taking at high levels and emotional stomping, rather than a complete collapse of the fundamentals.
Reports from institutions like Morgan Stanley and Goldman Sachs still expect that the total capital expenditure of global core cloud giants will reach between $1.2 trillion and $1.4 trillion by 2027. There is a natural "settling time difference" between the enormous capital expenditure for AI hardware infrastructure and the speed of monetization of upstream AI software applications.
Thus, some have summarized that the supercycle of storage is still ongoing, but the era of "buying with closed eyes" has ended.
03 Valuation Discount and High Capital Expenditure
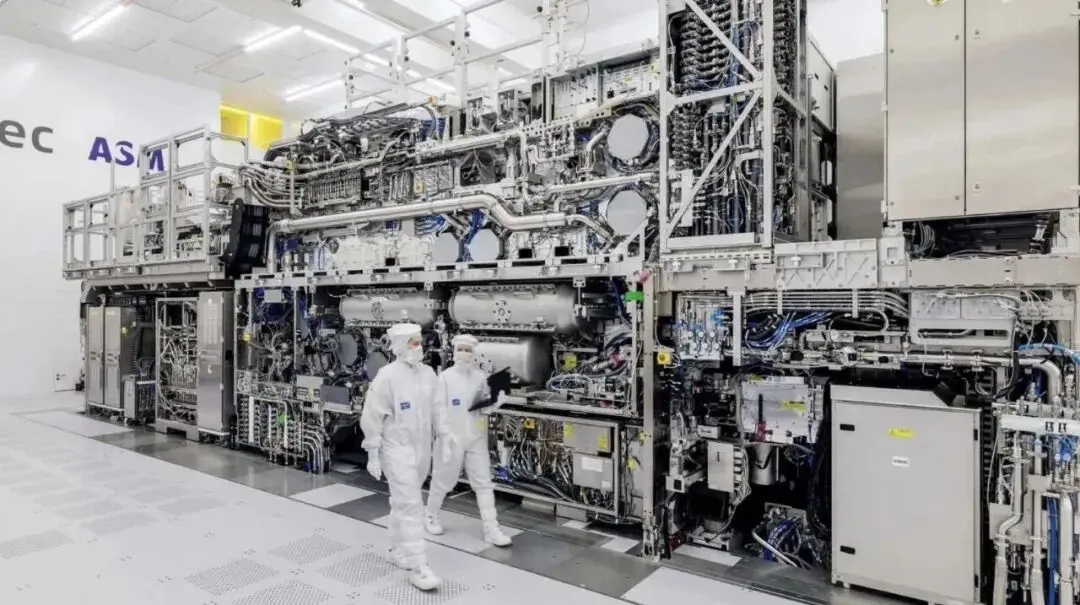
Despite short-term market sentiment being under pressure, the strong demand for high-performance memory driven by AI infrastructure construction still provides fundamental support for memory manufacturers. However, the paths to benefit and potential challenges for the three manufacturers vary.
Micron primarily benefits from the growth in HBM and server DRAM demand. SanDisk benefits from the growing demand for enterprise-grade SSDs in AI data centers. As an important player in the HBM market, SK Hynix has strong demand visibility due to its first-mover advantage and partnerships with leading customers.
However, strong AI demand is just the starting point for growth; the key is converting demand into sustained profits and cash flow.
As the earnings season approaches, the capital expenditures, advanced process investments, and advanced packaging expansion plans of memory manufacturers will also become important indicators for assessing the outlook for upstream semiconductor equipment demand.
Bearish voices and market concerns are equally evident, focusing on the extremely high pressure of capital expenditure and upstream cost squeeze—storage giants are caught in the most intense arms race for equipment and capacity in semiconductor history to compete for dominance in the HBM3e and next-generation HBM4 markets.
Samsung Electronics has committed to invest over 110 trillion Korean won (approximately $82.6 billion) in capital expenditures and R&D funding by 2026, setting a record for the company's annual budget; SK Hynix is fully expanding its Cheongju M15X plant specifically for HBM4 and has invested $3.87 billion to establish an advanced packaging base in Indiana, USA.
Industry data shows that to meet the squeezed demand for HBM, by the end of 2026, global storage giants will have up to 25% of DRAM wafer capacity forcibly locked for HBM production. The enormous capital expenditure significantly raises the subsequent depreciation and amortization costs for companies.
Even more severe is that the squeeze on the upstream cost side of the supply chain is further eroding profit expectations.
Previously, lithography machine giant ASML had clearly notified that starting from January 2027, it would uniformly raise the prices of replacement parts for EUV and DUV lithography machines supplied to Samsung Electronics and SK Hynix by 10%. Meanwhile, a price increase plan for lithography machines is also on the horizon.
Against this backdrop, SK Hynix's current dynamic price-to-earnings ratio is only 6.96 times, significantly lower than the semiconductor industry average. While there appears to be a valuation discount, whether this discount is reasonable largely depends on its ability to maintain the quality and sustainability of future profits under the dual pressures of high capital expenditure and rising operating expenses.
04 Retail Investors in Fear of Liquidation
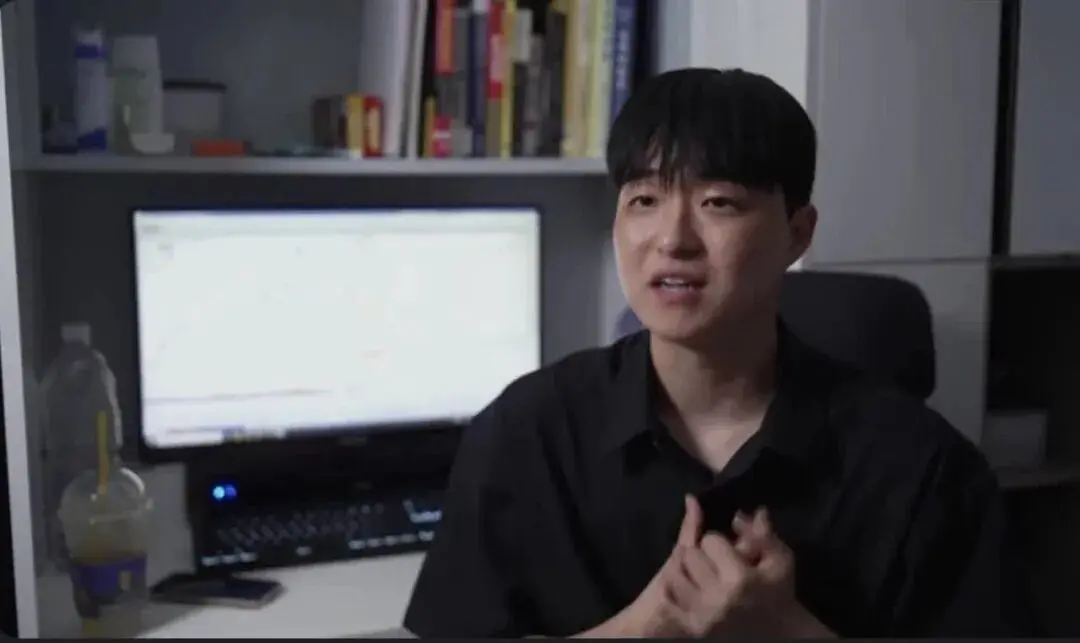
The risks of high-leverage trading among South Korean retail investors had already raised alarms earlier this summer.
Previously reported by Reuters, 24-year-old Seoul National University student Lee Seung-ho became a vivid early warning and typical example of such leverage risks.
Seoul National University student Lee Seung-ho facing liquidation
According to Reuters, Lee Seung-ho accumulated 20 million Korean won and participated in 5x leveraged trading through a trading app, with his account assets once soaring to 300 million Korean won (approximately 155,000 RMB). However, as market volatility intensified in May, margin calls and liquidations followed, and he lost all his gains and principal within just four weeks.
In the report, he described his physical and mental state at the time as "literally unable to breathe."
However, the risks accumulated from high-leverage trading have not been timely mitigated; instead, they have continued to decline and spread to the present as single-stock leveraged products have become popular among retail investors.
On October 12, the South Korean stock market suffered a brutal plunge, and this long-suppressed panic and anxiety erupted on social media platforms. After the close, South Korean investors flooded social media platform X with expressions of confusion and dissatisfaction.
Some retail investors compared the South Korean stock market with the trends of U.S. and Japanese stocks, questioning why the Korean market continued to be under pressure. Others pointed fingers at the continuous outflow of foreign capital, believing that the South Korean stock market failed to fully benefit during global market rises but bore greater pressure during adjustments.
These posts reflect retail investors' strong dissatisfaction with market performance, but behind the emotions, there are more concerning changes in capital.
According to recent trading data, on October 12, foreign capital net sold nearly 20 trillion Korean won in South Korean stocks in a single day, with a cumulative net sell of 29.7 trillion Korean won (approximately 1.56 billion RMB) over the past month. If this statistic is confirmed, it means that the outflow of foreign capital from Korean stocks has become an important source of pressure in this round of market adjustment.
If the outflow of foreign capital explains why the market is under pressure, leveraged trading relates to why the decline may further amplify.
The controversy surrounding Korean single-stock leveraged ETFs has recently continued to ferment in the investor community.
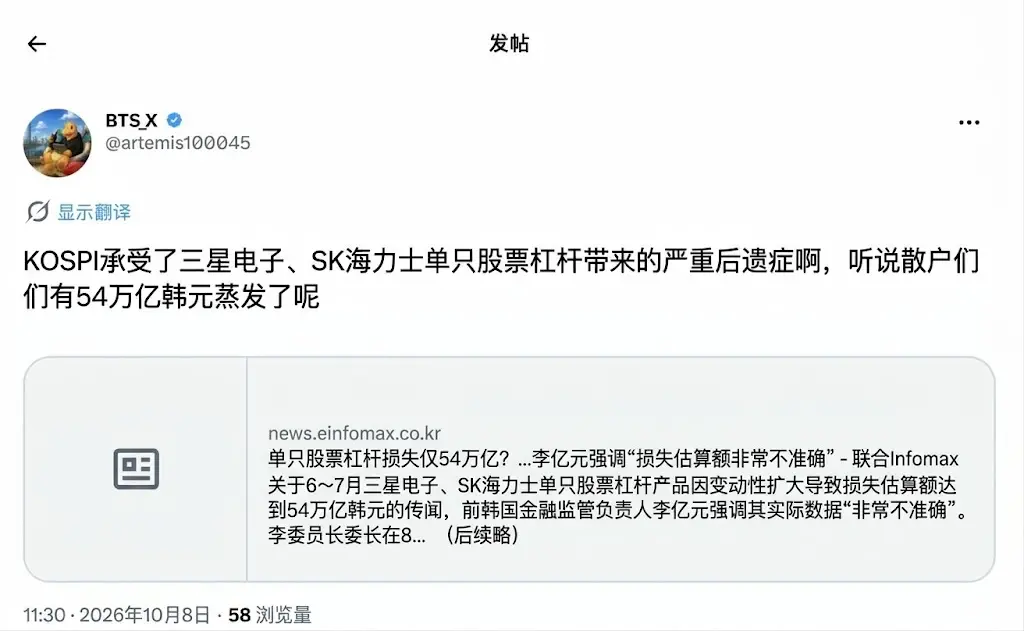
Some posts cite relevant estimates claiming that retail investors have incurred asset losses of 54 trillion won (approximately 283.5 billion yuan) in single-stock leveraged products. This figure reflects the tremendous destructive power of high-risk derivatives during market volatility, but it has also sparked numerous discussions about its statistical criteria and calculation samples.
Leveraged products significantly amplify stock price fluctuations.
When the market declines, a reduction in positions may trigger margin calls, forcing investors to close their positions passively and exacerbating downward pressure. Whether the daily rebalancing mechanism of single-stock leveraged ETFs will amplify the selling pressure of the underlying stocks on specific trading days requires a detailed analysis of the product structure and actual capital flows; it cannot be generalized.
From the liquidation of Lee Seung-ho's positions in July to the astonished reactions on social media regarding the 54 trillion won massive loss, it has exposed the extreme fragility of high-leverage trading during market reversals.
Thus, the recent adjustment in the Korean stock market reflects both a reassessment by investors of the growth prospects of the AI industry and the vulnerability of high-leverage trading during market reversals—when stock prices no longer continue to rise, the profit advantages brought by leverage can quickly turn into risks.
For some retail investors, the harsh reality is not the temporary losses but being forced to exit the market due to insufficient funds before a market rebound.
Leopold Aschenbrenner, a former OpenAI researcher who was hailed as the "new stock god of Wall Street" at the age of 25, is a typical example of the "tragedy" of being wiped out by four times leverage on the eve of a tech stock rebound at the end of July.
 Risk warning
Popular articles





