








Federal Reserve Meeting Minutes: All 19 decision-makers support a rate hike in September, with a "majority" expecting one more increase within the year, but suggesting there is no rush for October
 Core Viewpoint

 Most officials believe that the interest rate hike in September is an "insurance" measure to combat stubborn inflation; a minority of officials think it is a necessary action to curb inflation; overall, there is no indication of a willingness to push for multiple consecutive rate hikes. The New Federal Reserve Communications emphasized the content of the minutes: "Most participants believe that another rate increase before the end of the year may be appropriate." Almost all officials believe that inflation remains high, and the labor market is close to full employment.
Author: Yang Chen
The minutes from the Federal Reserve's September meeting show that the decision-making body exhibited a hawkish consensus on interest rate hikes, although there were differences in their reasons for supporting the increase.
According to the minutes of the Federal Open Market Committee (FOMC) meeting held from September 15 to 16, all 19 senior officials of the Federal Reserve supported raising the federal funds rate target range by 25 basis points to 3.75% to 4.00%. This marks the first interest rate hike by the Federal Reserve since July 2023.
The minutes indicate that "the majority of participants believe that further increases to the federal funds rate target range may be appropriate before the end of this year." However, participants emphasized that they maintain an open attitude towards each meeting, and future policy decisions will depend on the latest information available at that time.
Journalist Nick Timiraos, known as the "New Federal Reserve Correspondent," highlighted the contents of the Federal Reserve minutes: "Regarding the monetary policy outlook following the current meeting, the majority of participants believe that another increase to the federal funds rate target range may be appropriate before the end of this year."
With post-meeting employment data weaker than expected and several officials signaling "no rush to raise rates," the market currently expects the Federal Reserve is more likely to remain on hold at the October meeting and raise rates again in December.
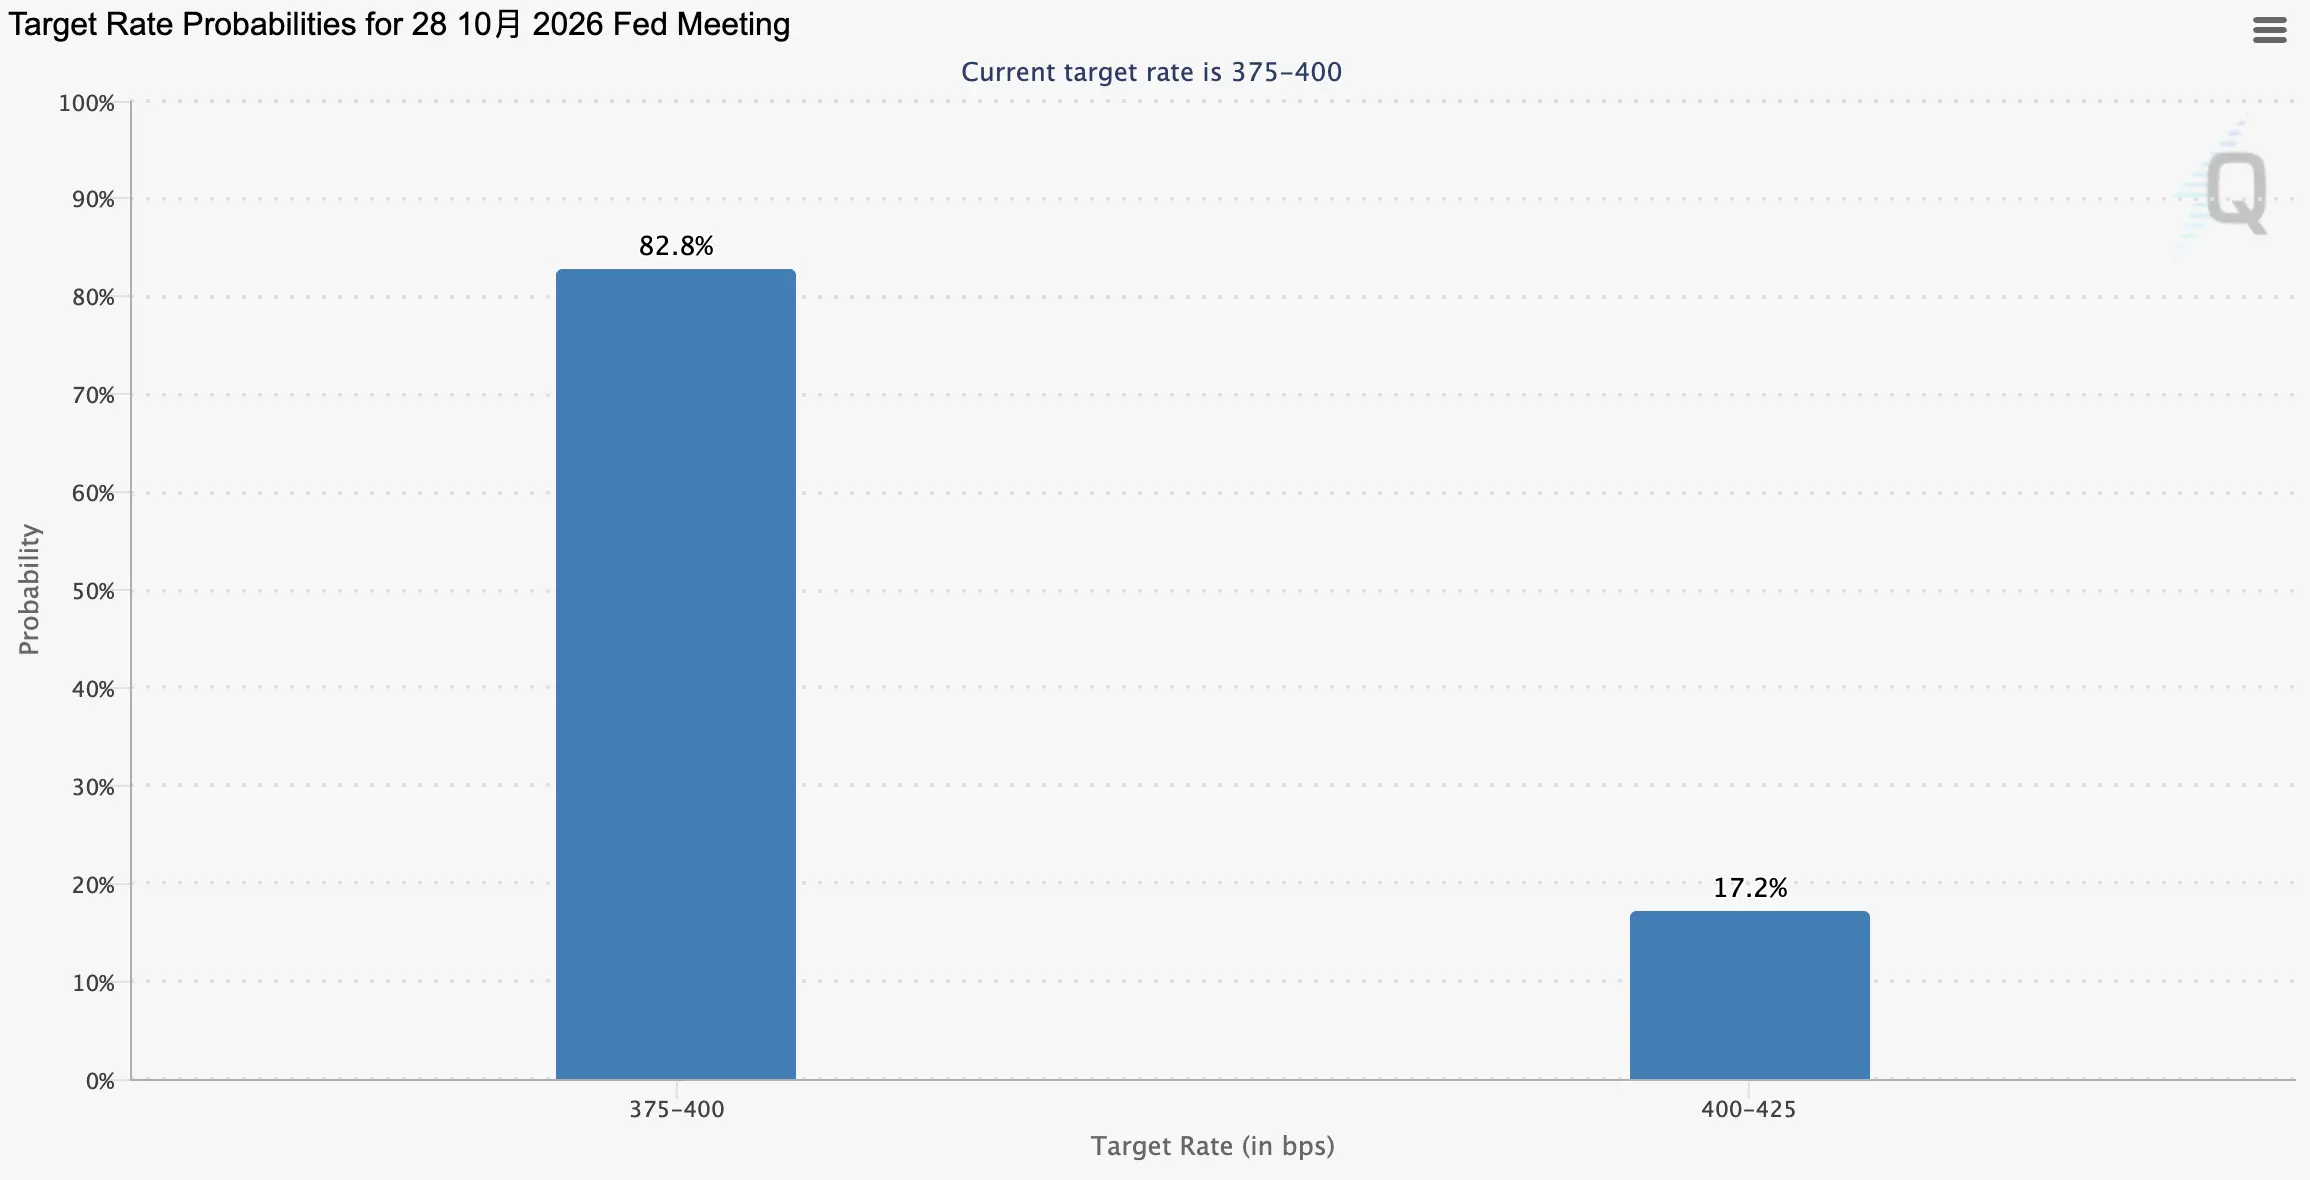
According to the CME FedWatch tool, investors are currently pricing in less than a 20% probability of a 25 basis point rate hike at the Federal Reserve's meeting on October 27-28, a significant drop from about 70% just days after the September decision was announced. The U.S. Consumer Price Index (CPI) to be released on October 14 may become an important data point influencing this expectation.
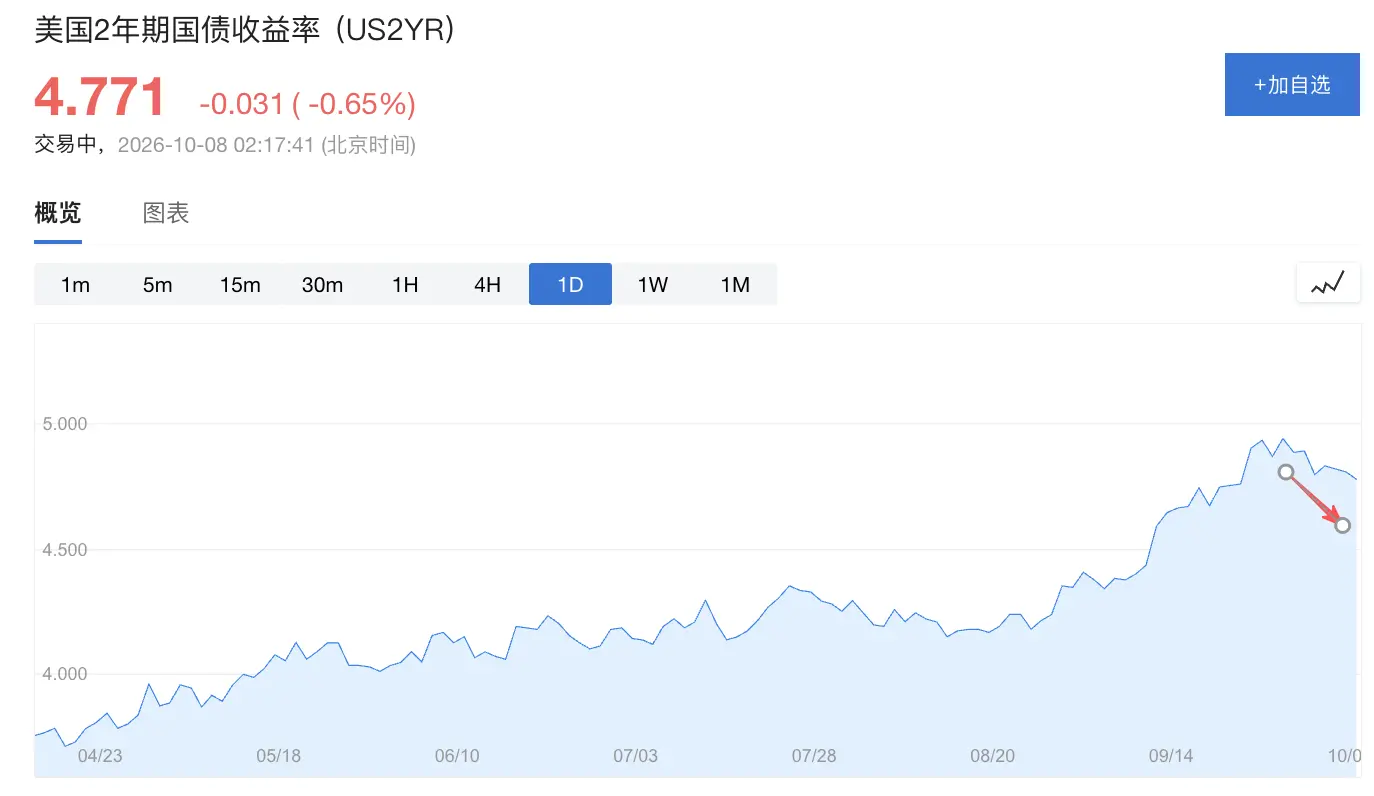
The yield on the two-year U.S. Treasury bond has fallen by more than 12 basis points over the past week and is currently close to 4.78%. As one of the maturities most sensitive to Federal Reserve policy expectations, the decline in the two-year yield reflects the market's belief that the necessity for the Federal Reserve to continuously tighten policy in the short term is decreasing.
19 Officials Unanimously Support September Rate Hike, But Differences Exist on Reasons
At the September meeting, Federal Reserve officials reached a consensus on the necessity of raising interest rates, but the minutes show that they had significant differences on whether the hike was for "insurance" or to address broader inflationary pressures.
"Many participants" believed that raising the target range for interest rates was a risk management consideration, providing insurance against inflation remaining persistently above the 2% target, especially in the event of stronger-than-expected demand or renewed supply shocks.
Meanwhile, another group of officials believed that a higher policy rate was necessary in itself to prevent recent shocks, such as energy prices, from spreading further to broader prices of goods and services. A few officials also believed that the rate hike aligned with their judgment of an increasing neutral interest rate level.
The minutes also indicated that some officials believed that the policy rate prior to the September hike was not sufficiently restrictive. "Several participants" stated that the then-current policy rate "was not restrictive or only slightly restrictive."
This means that while all officials supported the September rate hike, there was not a completely unified judgment that the Federal Reserve had entered a new phase requiring sustained significant tightening of monetary policy.
Most Officials Expect One More Rate Hike This Year, But No Urgency for October
Regarding the next steps in the policy path, the information released in the minutes leans hawkish but does not indicate that an October rate hike has become a predetermined plan.
The minutes state, "The majority of participants believe that further increases to the federal funds rate target range may be appropriate before the end of this year." This suggests that at the time of the September meeting, most officials still expected at least one more rate hike this year.
However, officials also emphasized that they would maintain an "open attitude" towards each meeting, and future policy decisions would depend on continuously received information.
This statement is consistent with recent public remarks by Federal Reserve officials.
New York Fed President John Williams and Federal Reserve Vice Chair Philip Jefferson have both recently stated that the Federal Reserve has time to further assess the economic situation and does not need to rush to raise rates again. Their remarks quickly prompted the market to reduce bets on an October rate hike.
Additionally, the weaker-than-expected U.S. employment report for September further lowered market expectations for a rate hike by the Federal Reserve this month. Investors currently lean towards the belief that the Federal Reserve will pause action in October, waiting for more inflation and employment data, and consider a second rate hike in December.
Inflation Remains Above Target, Energy Prices and AI Investment Increase Upside Risks
Although the Federal Reserve believes inflation is gradually cooling, officials still lack sufficient confidence in the pace of inflation decline.
The minutes show that almost all participants believe that inflation risks are skewed to the upside, with some officials noting that this upward tendency has strengthened in recent months. Officials pointed out that recent increases in energy prices, geopolitical risks, and tariffs could cause inflation to persist longer than expected.
The AI investment boom has also become an important source of inflation risk discussed at this meeting.
Some officials believe that AI is driving investment and enhancing productivity prospects, but it could also push inflation higher through increased demand, rising input costs, and heightened financing needs. At the same time, the strong demand for skilled labor in AI-related industries could also drive up wages for related positions.
The minutes state that AI development is driving corporate investment, and its scale and speed "continue to exceed expectations."
Additionally, some officials pointed out that core commodity price increases remain high. As the impact of AI development continues to expand, the resulting demand and cost pressures could offset some of the inflation relief from the weakening effects of tariffs.
U.S. Economy Remains Resilient, Financial Environment Still Supports Growth
The resilience of economic growth is also an important backdrop for the Federal Reserve's decision to raise rates in September.
The minutes show that several officials believe that the underlying momentum of the U.S. economy has strengthened. Consumer spending remains resilient, and corporate investment is supported by AI infrastructure development, with the overall economy still expanding at a relatively robust pace.
At the same time, the labor market is considered to be close to full employment levels.
The financial environment has also not imposed a sufficiently strong constraint on the economy. Although long-term U.S. Treasury yields have risen significantly recently, many officials believe that the overall financial environment still supports economic growth, due to factors including a substantial rise in stock prices this year and narrow credit spreads in corporate bonds.
The minutes indicate that the yield on two- to ten-year U.S. Treasury bonds has cumulatively risen by about 35 basis points during the relevant period. Officials believe that changes in real interest rates are one of the main reasons for the rise in long-term U.S. Treasury yields.
Market participants also view geopolitical situations, uncertainties surrounding the U.S. Treasury's repurchase plan, and the issuance of substantial private debt to finance AI infrastructure development as important factors pushing up term premiums and U.S. Treasury yields.
July Joint Intervention Supports Yen, No Federal Reserve Funds Used
The joint intervention in the foreign exchange market by the U.S. and Japan at the end of July to support the yen was an action taken by the U.S. Treasury and did not involve the use of Federal Reserve funds.
The minutes show that the New York Fed "fully acted as the fiscal agent of the U.S. Treasury" in implementing the intervention, using Treasury funds. The Federal Reserve's so-called System Open Market Account (SOMA) investment portfolio did not participate in this action. This account holds U.S. government bonds and other securities owned by the Federal Reserve.
The meeting minutes did not disclose the exact timing or scale of the intervention action. U.S. Treasury Secretary Janet Yellen stated last month that the U.S. only used "insignificant" funds in this action, and described it as being in line with U.S. interests.
The weakness of the yen has become an increasing concern for Japanese policymakers, as it raises import prices and household living costs. Meanwhile, former President Trump criticized the weak yen, arguing that it gives Japanese manufacturers an unfair trade advantage.
The action at the end of July marked the first joint intervention in the foreign exchange market to support the yen by Tokyo and Washington in nearly 30 years. According to data from the Japanese Ministry of Finance, Japan invested a record 15.4 trillion yen (approximately $97.5 billion) in the foreign exchange market for intervention within a month as of August 26.
Japanese Finance Minister Shunichi Suzuki and U.S. Treasury Secretary Janet Yellen have both signaled that the two countries are willing to intervene again if necessary.
 Risk warning
Popular articles





