








HIP-3: An expensive ticket, an unbuyable moat
 Core Viewpoint

 The money earned from operating these exchanges is about one-fifth of what would be earned by staking the same amount of funds in place.
Author: Mario Chow, IOSG
Ten teams have registered their perpetual markets on Hyperliquid, locking approximately $40M of HYPE in total. One of these teams accounted for 97.8% of the trading volume and has just seen a 44% drop in a single month. This article aims to answer what the other nine teams have acquired, with all figures sourced from on-chain data rather than announcements.
All numbers in this article are directly sourced from Hyperliquid's public API: perpDexs, metaAndAssetCtxs, daily candleSnapshot covering all 519 registered assets, delegatorSummary, userNonFundingLedgerUpdates, and clearinghouseState{dex}. "30 days" refers to the complete UTC calendar days from August 15, 2026, to September 13, "the previous 30 days" refers to July 16 to August 14, and "7 days" refers to September 7 to 13. HYPE is calculated at $79.73. The routing data in Section 7 is sourced from Flowscan, as the trading volume from the builder code cannot be aggregated from the public API.
Summary
HIP-3 has once again become a minority on Hyperliquid. The markets deployed by builders accounted for 25.8% of perpetual trading volume in the last 30 days, down from 57.1% last month. This change primarily stems from the denominator: core trading volume has more than doubled, while HIP-3 itself is declining.
The leader is contracting. Trade[XYZ] had a trading volume of $64.60B in the last 30 days, down 44.2% month-over-month, with the 7-day average dropping from a peak of $5.36B/day in early August to $2.01B/day. This decline corresponds roughly half to the drop in trading volume in the storage and AI sectors in the real market, and the other half is due to this venue itself. Since August 18, it has not outperformed the core order book on any single day.
Entropy (io) led in a confrontational market for a full week before giving it back. Its share on Nebius has shown a trajectory of 8.7%, 53.1%, 20.4% over three weeks, and its own trading volume has also declined for three consecutive weeks. The reverse signal is in the positions: open interest has risen against the trend by 37%, reaching $51.4M.
Settlement assets remain a lifeline, with records still at 6 to 6. All venues that settle with non-USDC stablecoins have ceased trading; those that are still active all use USDC.
Asset listings cannot be maintained. At the current auction floor price, an asset is approximately $39,900, and buying all of Paragon's online markets would cost around $1.04M, equivalent to two weeks of fee income for Trade[XYZ].
No one is competing on price. All stock venues are running on deployerFeeScale = 1.0 with Growth Mode, with actual rates of Trade[XYZ] at 0.427 bp and Entropy at 0.400 bp. All venues outside the leader, regardless of survival, have collectively earned only $747,000 in deployment shares over their lifetime.
I. The Ten Deployers Present
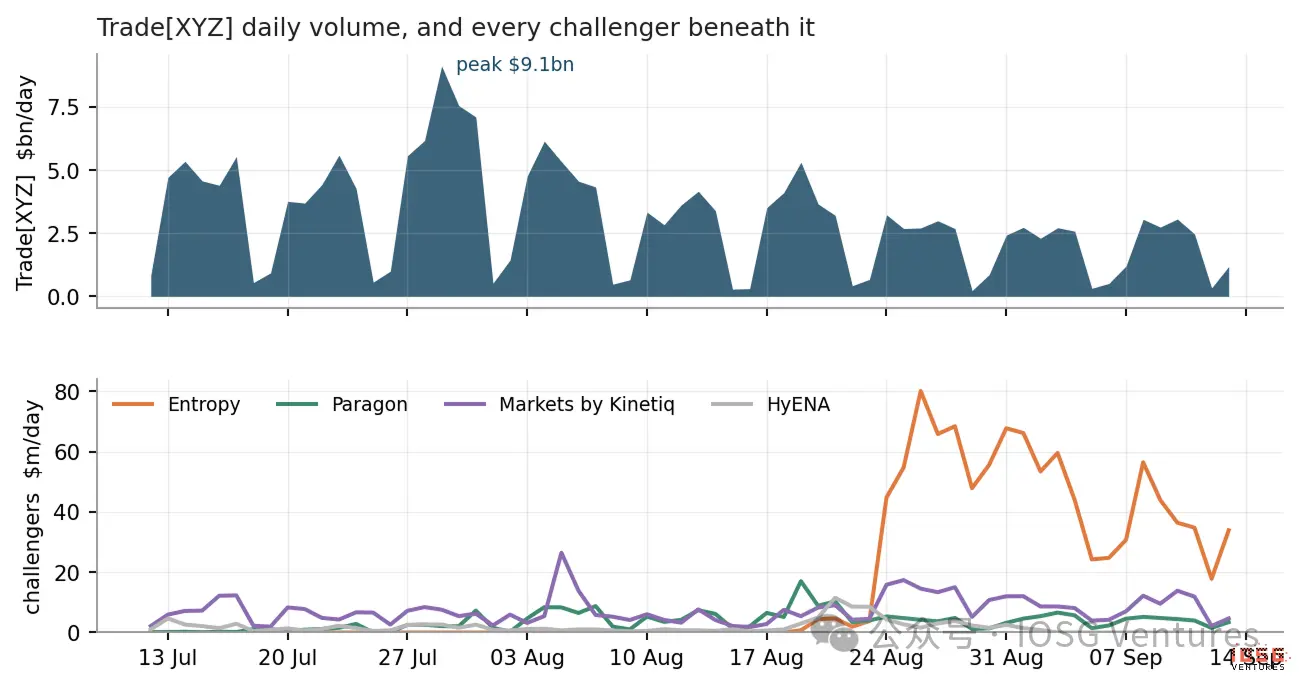
▲ Daily trading volume of Trade[XYZ] and all its challengers below. The vertical axis scale of the two charts differs by about 100 times.
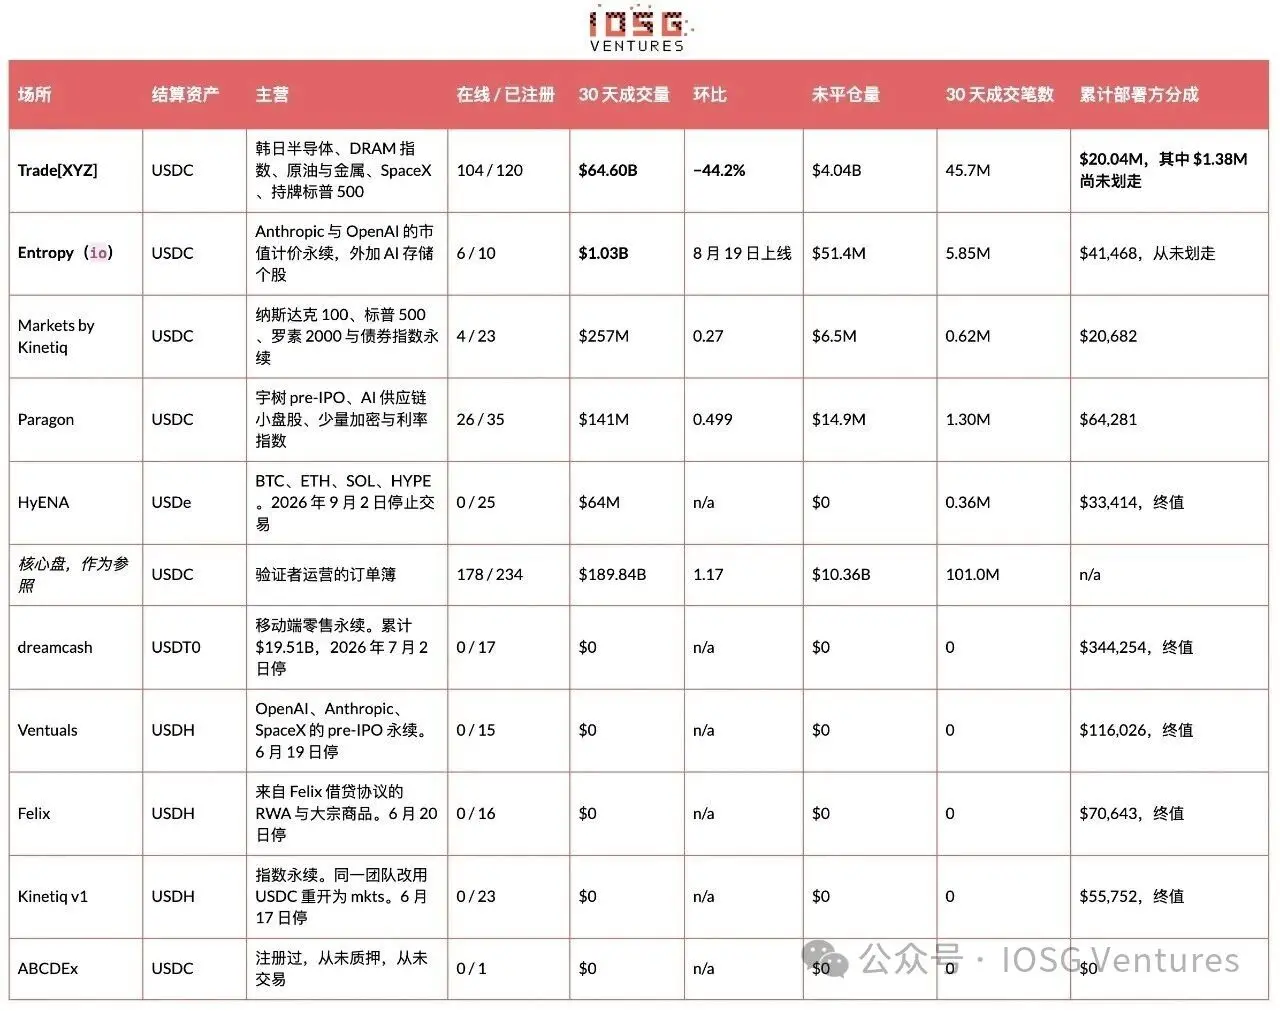 "Transaction count" is the sum of the n field in the daily K-line within the window. The public API cannot provide the number of independent traders.
Historically, only ten have registered perpetual DEXs, and there has yet to be an eleventh. Four are trading, five have stopped, and one has never opened. Trade[XYZ] accounted for 97.8% of HIP-3's trading volume in the last 30 days and 97.6% in the last 7 days.
The situation of the challengers can be summarized in a few sentences. Entropy made $1.03B over 26 days, with six online markets, relying on its own oracle rather than an asset list. It is the only venue that has truly led in a market that also quotes the leader. Paragon is the only challenger whose order book resembles an order book, with 26 online markets and a tail distribution that is open; in the case where Trade[XYZ] entered five of its targets at once, it still increased by 49.9% that month. Markets by Kinetiq purchased 23 targets, with 95% of the volume concentrated in two index perpetuals. HyENA has ended: the market has been delisted, open interest has gone to zero, and it earned $33,414 over its lifetime.
II. The Share of HIP-3 and Why It Is Easily Misinterpreted
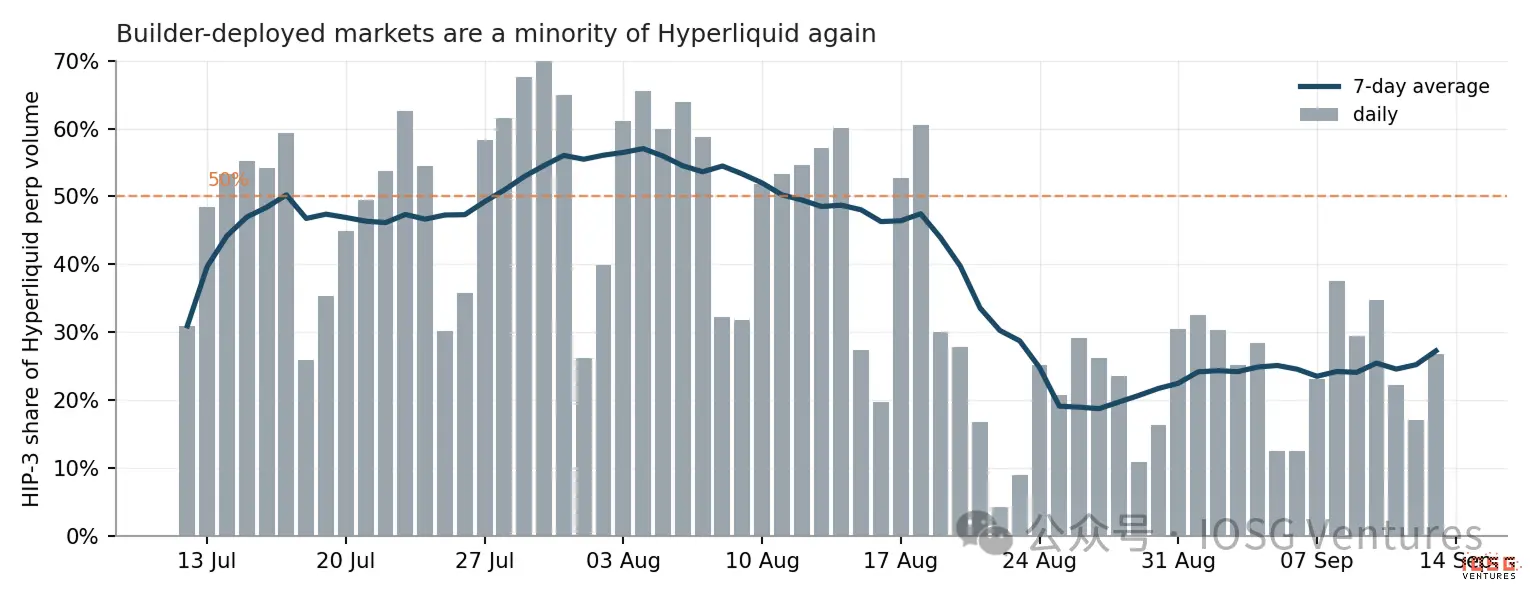
▲ The share of HIP-3 in Hyperliquid's perpetual trading volume, calculated daily.
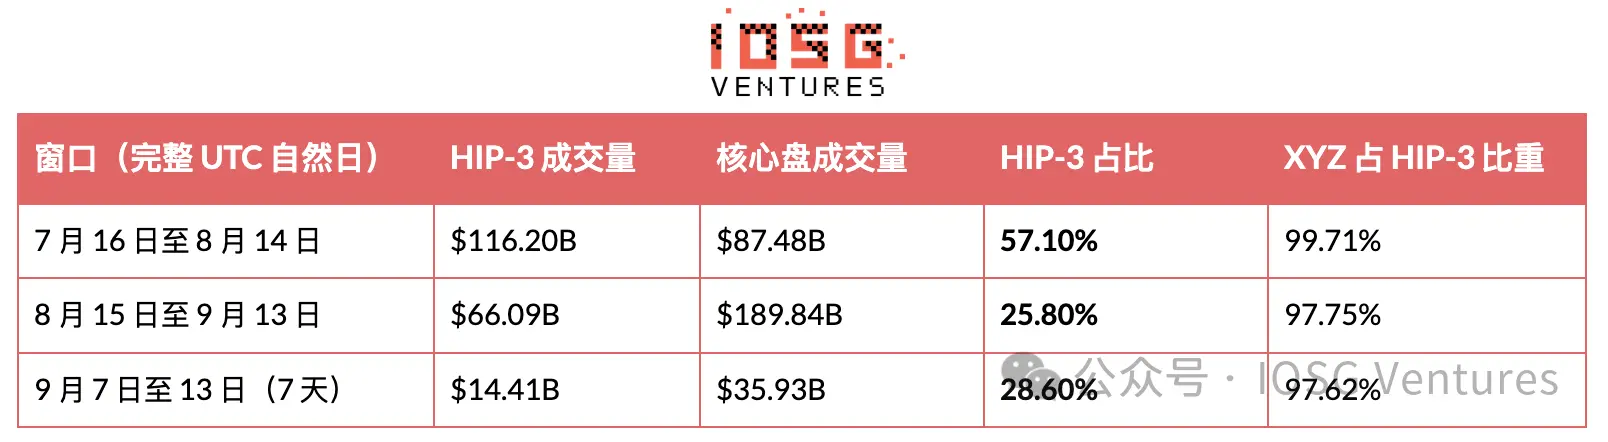
The 7-day average crossed 50% in mid-July, peaked close to 57% in early August, then fell below 30%, and has not risen since August 20. On August 18, the trading volume of one builder surpassed the entire validator set of Hyperliquid. It has not achieved that since.
This ratio actually speaks to its denominator. The numerator is a stock order book, while the denominator is a crypto order book, and the fluctuating leg is on the crypto side. The 57% was read during a quiet crypto period, while the 26% was read when the same stock order book encountered market conditions, during which the core perpetual volume increased by 117%. The share in the last seven days even returned to 28.6%, while Trade[XYZ] continued to shrink. Before citing any HIP-3 share, it is crucial to clarify what crypto was doing during that time. What truly matters is the absolute volume, and the absolute volume is deteriorating. Trade[XYZ] had a trading volume of $64.60B in the last 30 days, down 44.2% from the previous month, with the 7-day average dropping from $5.36B/day in early August to $2.01B/day, and its own order book retracting by 62%. The largest market, SK Hynix, dropped to $8.50B. Both legs of the declining share are real. The following section will explain that most of HIP-3's leg is not a competition issue. The primary reason for the decline in trading volume is the storage sector turning quiet, not a loss of share. Interpreting the 44% drop directly as "the leader is losing" is the easiest explanation, but the data does not support it. The verification method is straightforward: if the decline were due to competition, we should see the targets themselves trading as usual, with only the portion captured by Trade[XYZ] decreasing. What actually happened is that the targets themselves have quieted down.
There has been no sell-off. Using early August, when trading volume peaked, as a benchmark, the price of every major market in the order book today is higher.
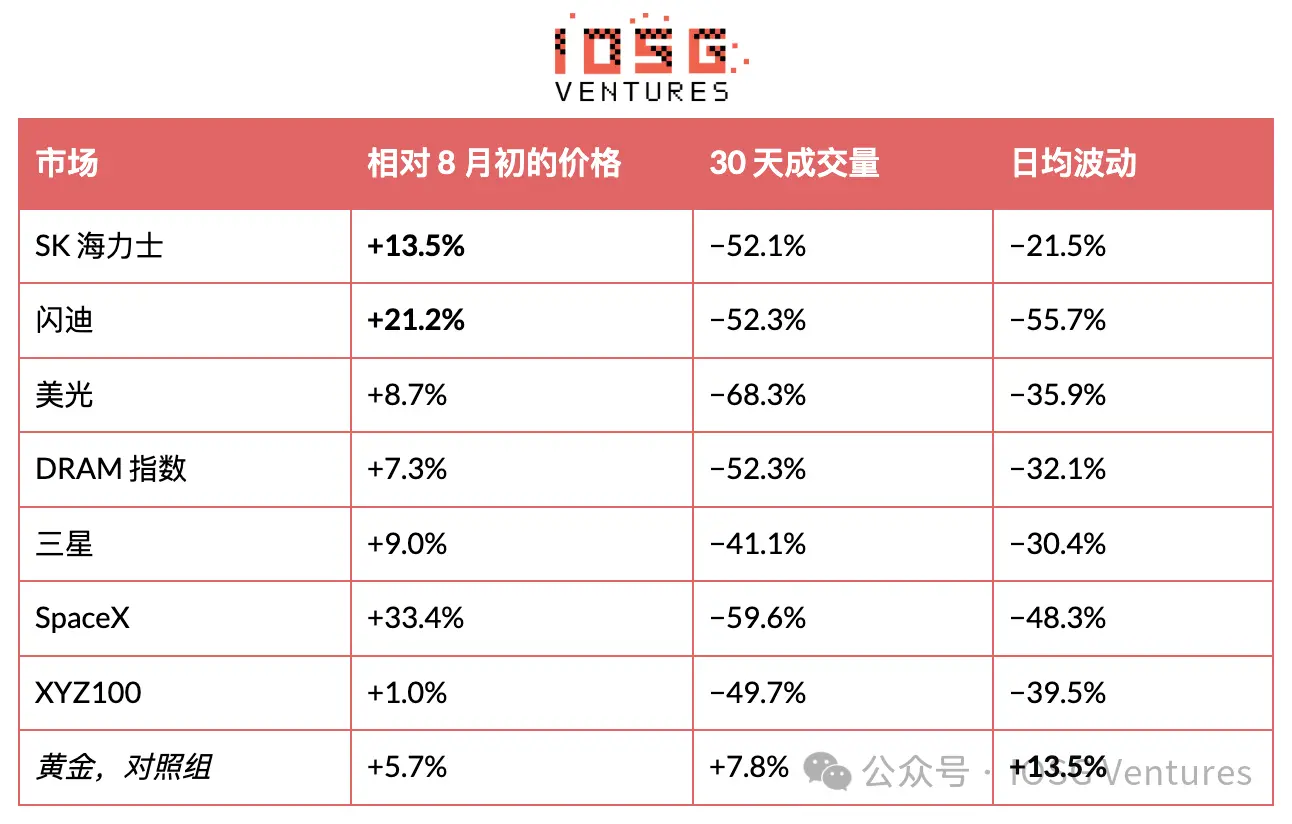
What has truly collapsed is how far these targets can move in a day, while the venue's trading volume has almost followed suit. 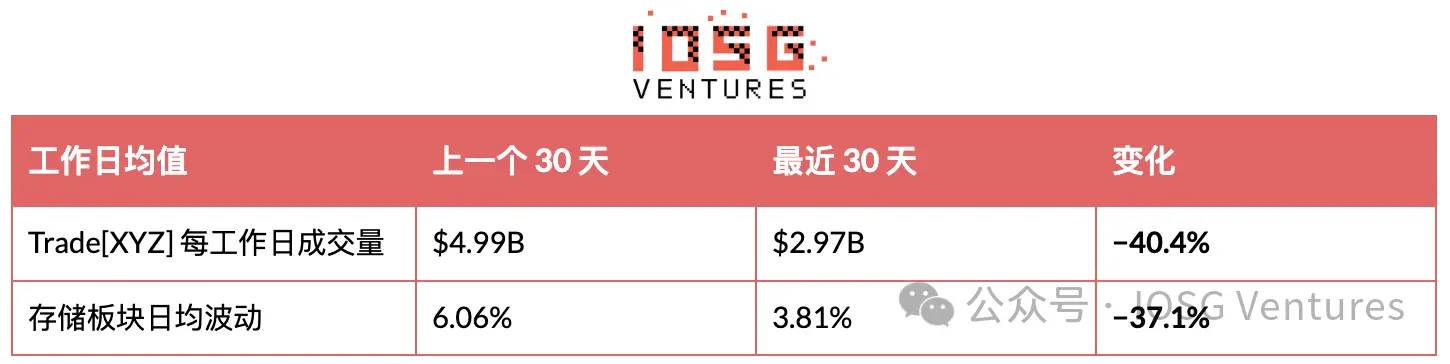
The above is all based on weekday metrics, as the stock market is closed on weekends while Trade[XYZ] continues to trade, including weekends would significantly exaggerate this relationship. Looking only at weekdays, the correlation coefficient between the daily average volatility of the storage sector and the daily trading volume of the venue is +0.47, with a sample of 45 days. Gold serves as a natural control group: it is the only major market with increased intraday volatility this month, and its trading volume has also risen. Silver is an exception that does not fit this pattern.
However, volatility is merely a proxy variable. A more direct test is to compare the actual stock trading volume of the same nine targets, and the answer is: the traditional market only explains about half.
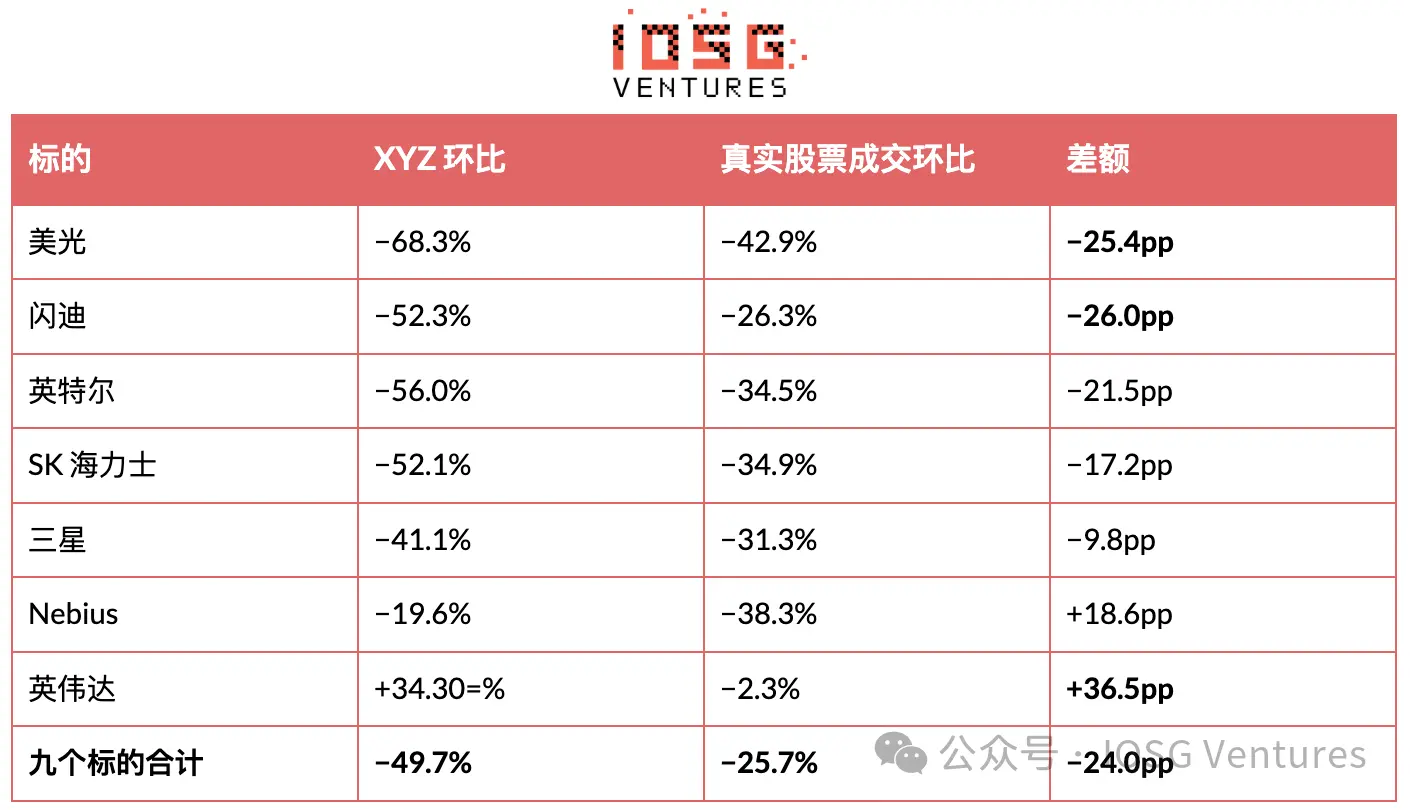
The actual trading volume in the storage and AI sectors indeed collapsed by 25.7%, and that half is real. But XYZ dropped by 49.7%, nearly double. The extra 24 percentage points are not provided by the industry.
Moreover, the largest gaps are precisely in its core: SanDisk −26.0pp, Micron −25.4pp, Intel −21.5pp, SK Hynix −17.2pp. It actually outperformed the real market on Nvidia (+36.5pp) and Nebius (+18.6pp), but those two order books are quite small.
Competition also cannot explain this gap. Entropy's total trading volume for SanDisk over 30 days was $523M, while XYZ's own SanDisk order book was down $6.14B, so the challenger could only capture about 8% of that.
The remaining portion resembles capital rotation. During the same period, the core perpetual trading volume on Hyperliquid increased by 117%, while HIP-3 declined, and the total volume from both sides still increased by 26%. Money has not left Hyperliquid; it has merely rotated from the stock order book back to the crypto order book.
Scale anchor points. During the same 30 days, these nine targets traded $2,004.7B across their respective exchanges, while XYZ traded $23.5B on them, accounting for 1.2%. The total of XYZ's 104 markets at $64.60B only corresponds to 3.2% of the actual trading volume of these nine names. The highest penetration rate is 9.1% for SK Hynix, while the lowest is 0.1% for Broadcom, and this curve itself illustrates what this business is about: assets that crypto-native traders cannot reach have high penetration rates, while widely available US large-cap stocks have low penetration rates.
Thus, this decline is due to both factors: about half is the sector's beta, and the other half is its own. The calculations in Section 6 only consider actual trading volume, regardless of where the volume comes from, so the fee income is unaffected. However, it is important to view these two halves separately: the sector's half will return, while the venue's own half may not.
III. Reshuffling and the Only Predictive Variable
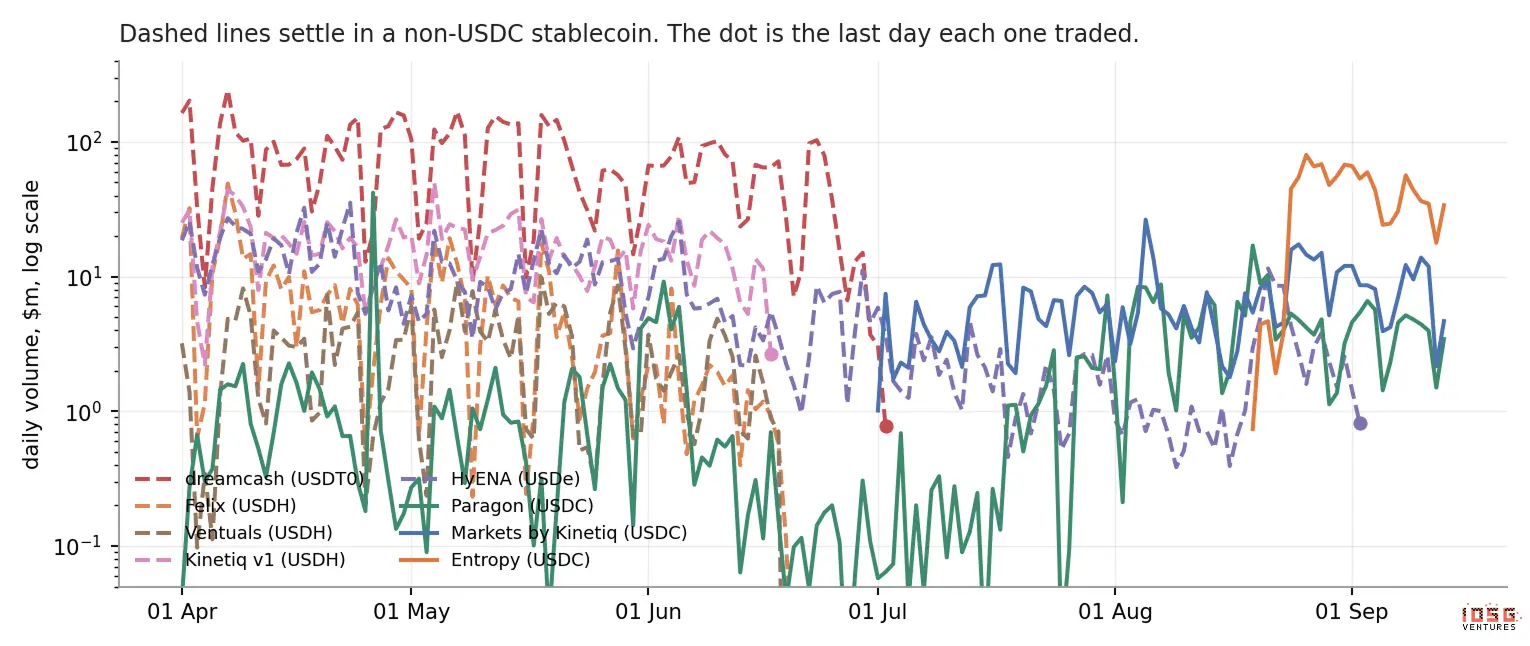 ▲ Daily trading volume of each HIP-3 venue, on a logarithmic scale. The dashed line represents settlements using non-USDC stablecoins, and the dots indicate the last day they had trades.
As of today, six venues have stopped trading, and the variable that separates them is not asset selection, team level, or historical trading volume, but the stablecoin used for settlement.
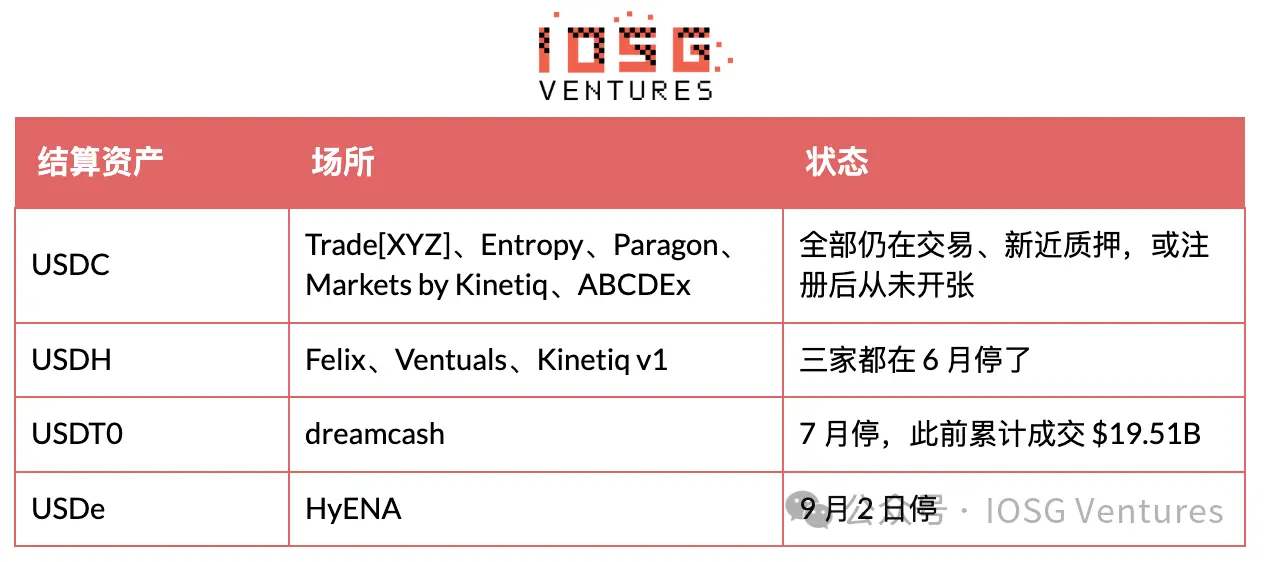 The mechanism itself is quite simple: traders must first exchange for a specific stablecoin to place their first order, and they are reluctant to do so. Felix is the clearest example. The small fee discount that supported USDH was wiped out as soon as Growth Mode launched, leaving this settlement asset with only friction.
Kinetiq serves as a control experiment. The only operator that survived after shutting down did so by eliminating the USDH venue and reopening an identical index product on USDC. Historical trading volume predicts nothing: dreamcash had $19.51B, more than the entire batch from June combined, yet it still stopped. Entropy entered in August with more funds than any previous entrant, and there was no hesitation when choosing USDC. What truly determines the settlement asset is not what it is not Reading USDC's sweep as an arrangement of the protocol is quite natural, but Hyperliquid's own documentation states the opposite. Under Aligned Quote Assets v2 (activated on USDC in late August, with Coinbase as the treasury deployer and Circle as the technical deployer), approximately 90% of the adjusted reserve earnings from USDC on Hyperliquid are allocated to the protocol and enter the Assistance Fund. Interest is calculated over 30-day periods, with payments made on the 8th day after each period ends, so the first payment will not arrive until early October, and not a penny has been received yet.
AQAv2 explicitly does not favor HIP-3. The documentation states clearly: there are no preferential treatments regarding trading fees or trading volume, and other priced assets continue to be supported on HIP-3 perpetual. The benefits in fees belong to AQAv1, which offers lower taker fees for collateral assets at venues, higher maker rebates, and higher trading volume counts, while USDC is not included in AQAv1 and structurally cannot enter because that tier requires stablecoins to be exclusive to Hyperliquid. The real privileges offered by AQAv2 point to event contracts and validator-operated perpetuals, and they must wait for subsequent upgrades, which are not measured in this article.
Thus, the matter of settlement assets is determined by liquidity and a one-time corporate-level action, not by fee design. USDH ceased operations on July 17, 2026, and holders redeemed it for USDC at a 1:1 ratio, with Coinbase acquiring its brand assets while also becoming the treasury deployer for USDC. Today, in the stablecoin supply on Hyperliquid, USDC accounts for 98.3%, USDT 1.2%, and the remnants of feUSD, USDe, and USDH each about one thousandth. A venue settling with other assets has not suffered in terms of fees. It is demanding its traders to leave the only pool with depth.
Estimating the scale of AQAv2, on the premise that the official has never disclosed any numbers. USDC on Hyperliquid is $6.77bn, SOFR is about 3.6%, and based on a 90% revenue share, this line roughly points to around $200M annually. Third-party estimates based on a $5bn base fall between $135M and $160M. What cannot be determined externally is the cost adjustment in AQA rates, which is reported by a validator oracle whose level is not public, so every number here is an estimate rather than a measurement.
HyENA fills in a second mechanism. Because it listed crypto assets, it was blocked from Growth Mode, and thus quoted about 5 basis points on the same underlying, while its core market quoted about 3 basis points, resulting in poorer trade quality. It spent about $0.88M on asset positions, earning a lifetime total of $33,414.
Stopping operations does not equal exiting. HyENA has delisted all 25 markets, with open positions reduced to zero, but its staking remains at 508,915 HYPE, about $40.6M, and twelve days have passed without initiating any withdrawals. Felix and dreamcash have fully reclaimed their stakes, now reading zero, while Ventuals only has 7,967 left. A venue that has delisted all markets but retains $40M staked on-chain is either slow to liquidate or is occupying this deployment position for something else.
What Ventuals died from is worth discussing separately, as the next generation of products is designed around this issue. Insufficient liquidity is merely a symptom; the mechanism lies in funding rates: pre-IPO perpetuals did not converge to an anchor, and funding rates once soared to an annualized rate of about 8,700%. Regardless of whether the marked price is correct, longs will be liquidated. Entropy caps the annualized funding rate around 10% and settles to its marked price's TWAP, rather than chasing an external price. Its contract design can be read as a checklist for addressing the specific causes of Ventuals' demise. When looking at any pre-IPO market, first check the funding rate and settlement design, then look at the asset list.
IV. The Market Composition of Trade[XYZ] and Why It Does Not List OpenAI
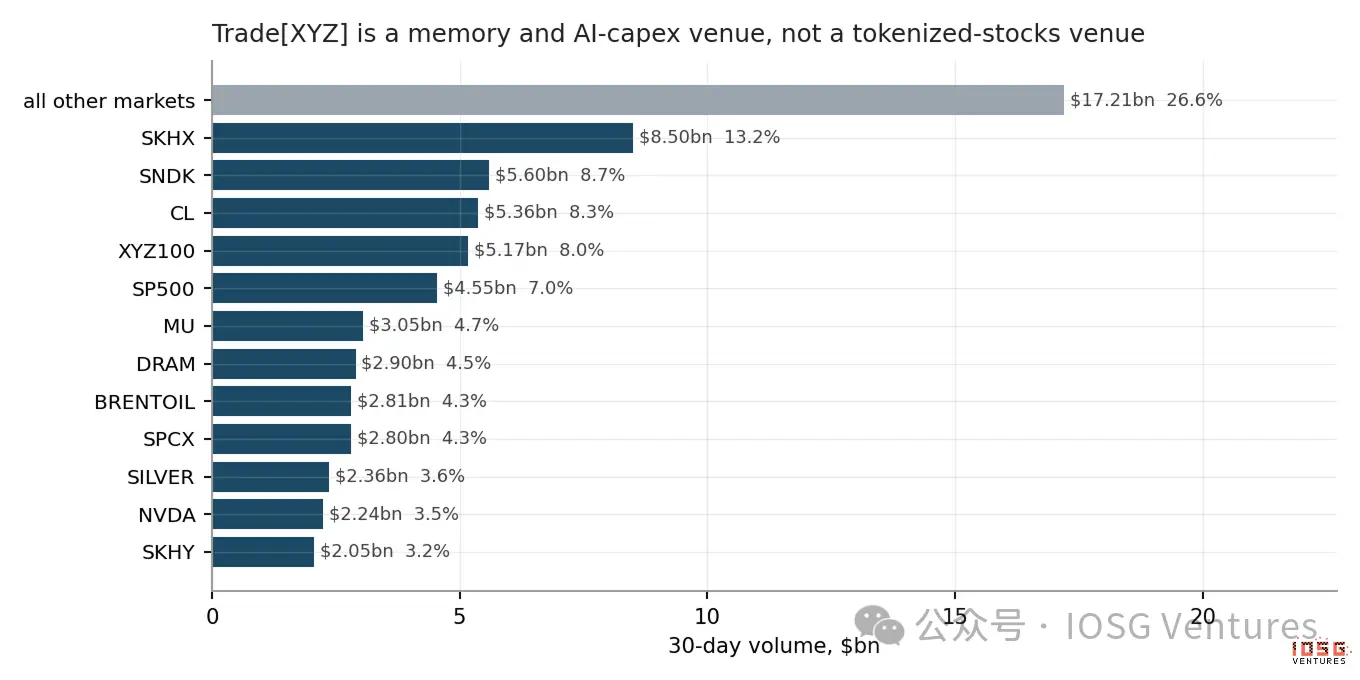 ▲ The markets with the largest trading volume on Trade[XYZ] over the past 30 days.
The top ten markets account for 66.7% of the market share, and the tail outside the top six alone has $32.4B. NVIDIA accounts for 3.5%. Apple, Tesla, Alphabet, and Microsoft together account for 3.3%, only a quarter of SK Hynix. The standard narrative for tokenized US stocks loves to talk about these American giants, but they are not the business here. Trade[XYZ] actually operates a 24/7 venue focused on storage and AI capital expenditure trading, along with crude oil, metals, and index products: Korean and Japanese semiconductors, a synthetic DRAM index, SpaceX, its own XYZ100 basket, and a licensed S&P 500. Its territory consists of assets that crypto-native traders cannot find elsewhere at three in the morning. And this is precisely the territory that Entropy chose to attack, with entry points being SanDisk and Nebius, not Apple. Why Not List OpenAI The most intuitive answer that it avoids unlisted companies is incorrect. Pre-IPO is actually one of its better-performing businesses. SpaceX alone had $2.80B in trading volume over 30 days, accounting for 4.3% of the market, ranking ninth. Following that are Yushu at $511M, Changxin Storage at $317M, Zhipu at $156M, MiniMax at $92M, and SHEIN at $27M, with Yangtze Memory Technologies already registered and pending release.
These names share a common point: they all have observable secondary trading prices and known equity numbers. SpaceX regularly conducts tender offers, providing a clear price per share; these Chinese companies have active pre-IPO gray markets in mainland China, and equity numbers can be obtained from business records and financing rounds. Therefore, this venue can quote per share like it does for other assets.
OpenAI and Anthropic have neither. Their secondary trades are wrapped in SPVs, and what is traded is a claim on a fund share, discussing an overall negotiated valuation rather than a specific price per share. Forcing a per-share quote would be equivalent to creating a denominator out of thin air. The bottleneck lies here; it is a matter of quoting convention, not willingness. Entropy's solution is simply not to quote per share but to report the company itself, with 1 contract = $1bn market cap, calculating to approximately $2.17tn for Anthropic and $1.53tn for OpenAI at the current midpoint price.
But this does not constitute a moat. The leader can add a market cap-priced asset at any time for about $39,900. Moreover, its own roadmap points elsewhere: it has 16 registered but unused assets, including uranium, aluminum, the US dollar index, VIX, corn, wheat, TTF, Korean won, Indian Nifty, Brazilian Ibovespa, Ibiden, and KSTR, along with Yangtze Memory Technologies and H100. This is macro and commodities, not cutting-edge AI laboratories.
There is a structural detail worth noting. Trade[XYZ] has not set up an oracleUpdater, meaning it does not push marked prices using its deployment key; instead, both Entropy and Felix point to the same third-party updater 0x94757f8d…. Entropy has publicly stated that RedStone is the source of price data for its Anthropic market, which explains why these two unrelated venues share an update address, although there is no label for this address on-chain. Self-built oracles are fine for assets with reference prices, but when marked prices must be "constructed," the nature changes, and constructing marked prices is precisely the business that Entropy chose.
V. Direct Confrontation and the Week When Entropy Led
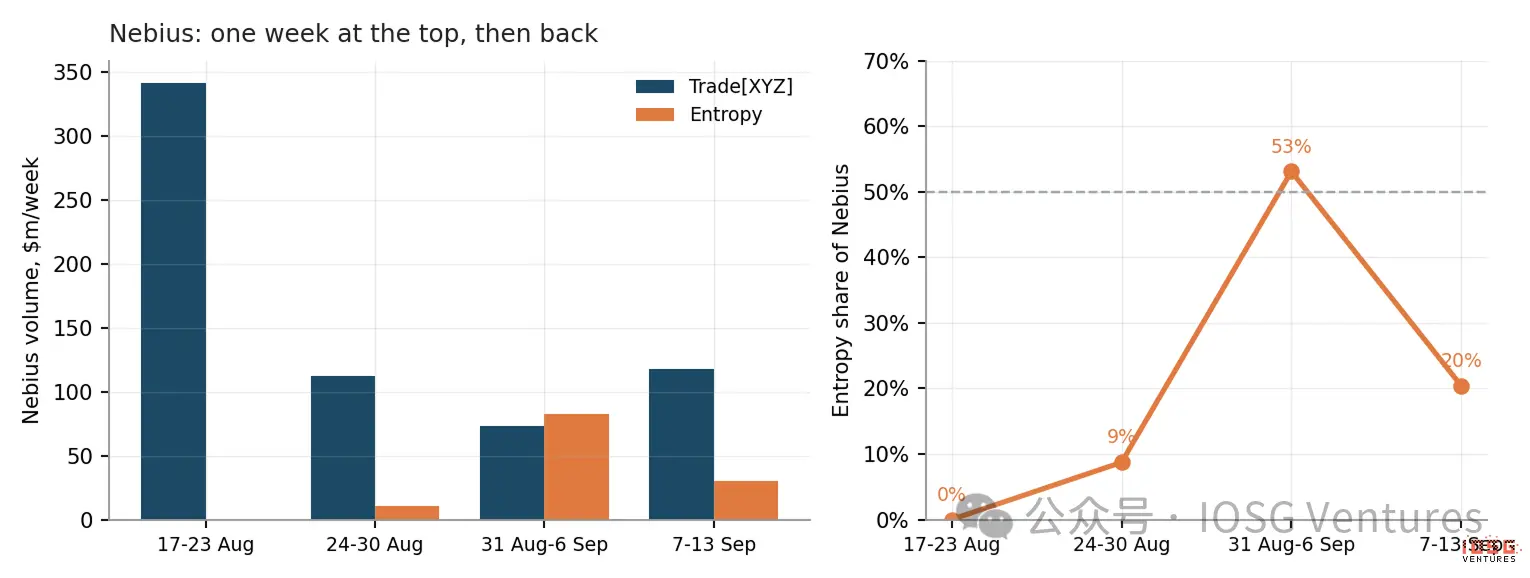 ▲ Weekly trading volume of Nebius and Entropy's share in it.
Currently, there are nine assets simultaneously active on both HIP-3 venues. Each venue no longer occupies a separate, non-overlapping market; any name worth listing twice has become the norm.
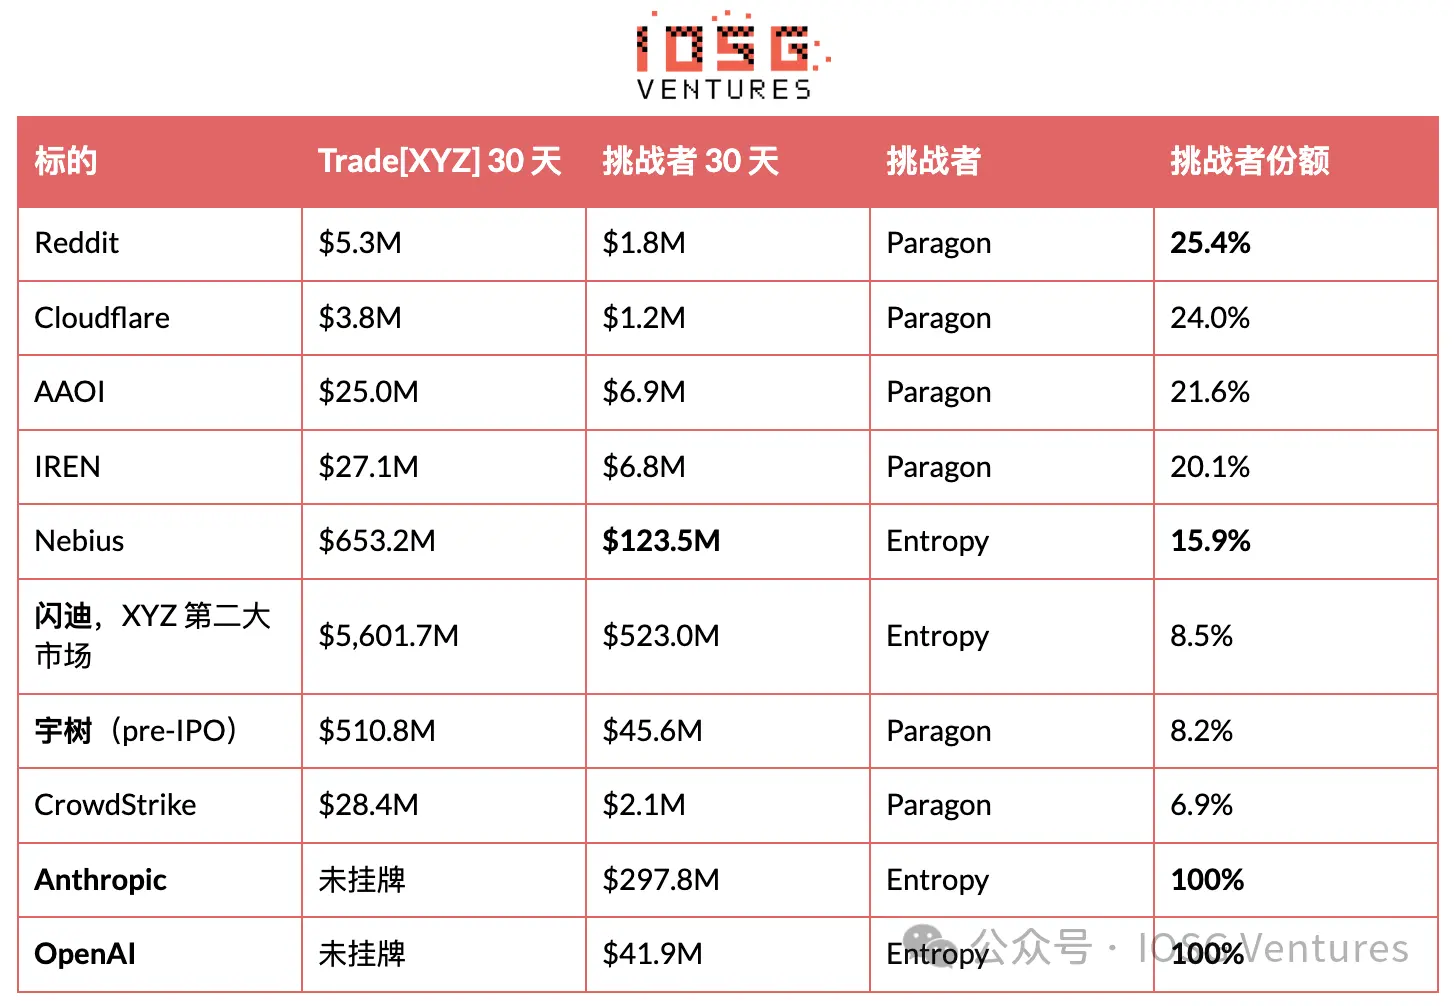
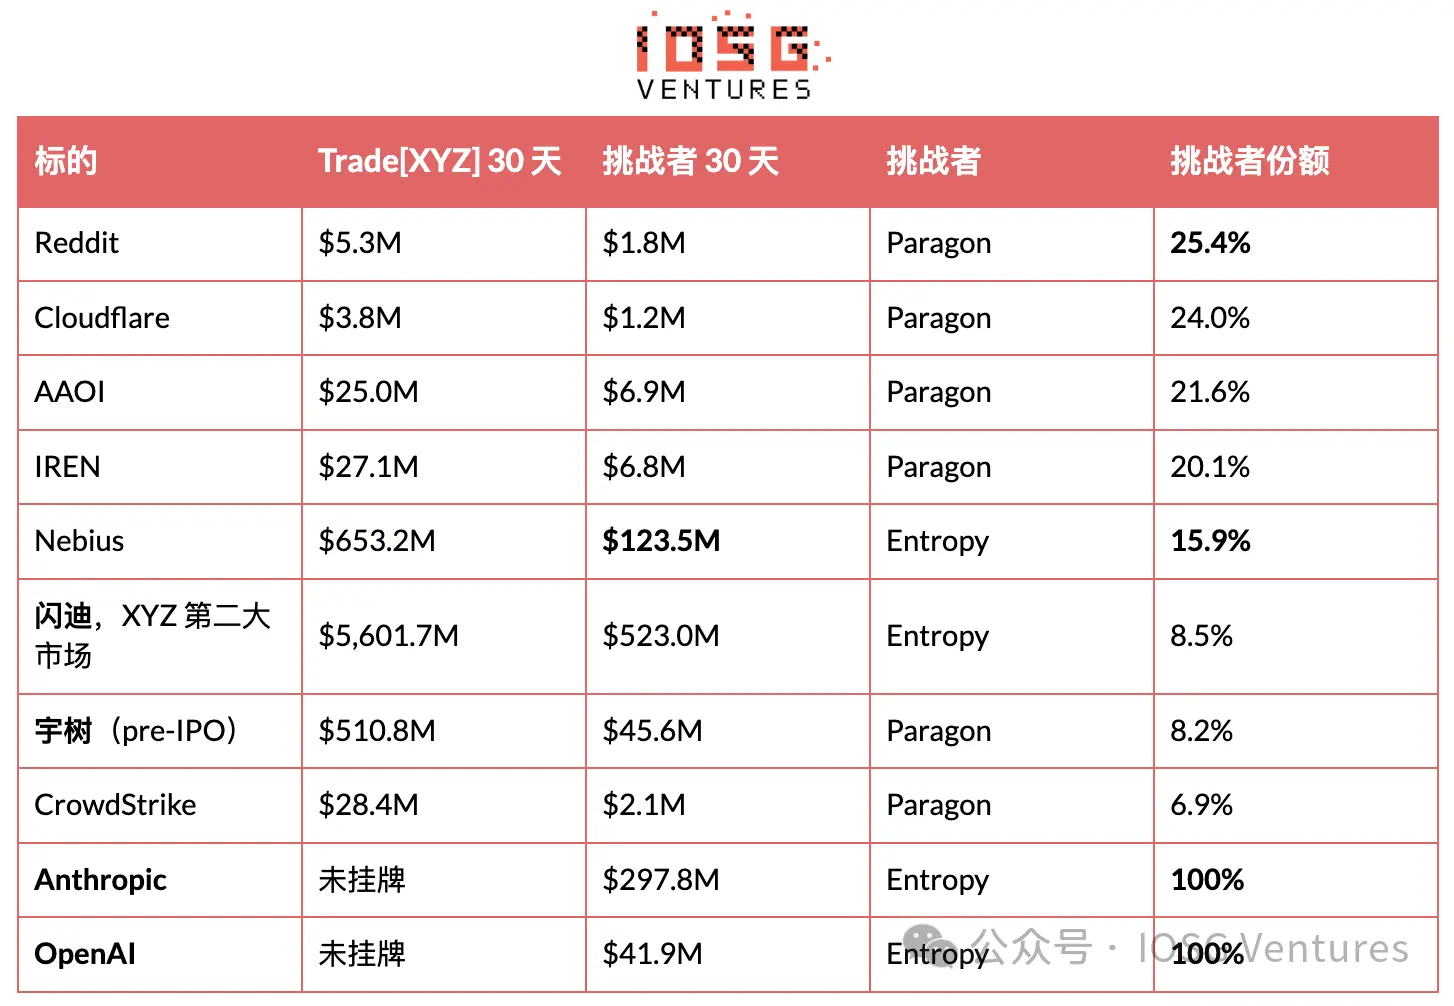 The positions taken away are shares, not the market depth
Trade[XYZ] once registered all five core targets of Paragon but did not activate them. On August 18, all were opened in one day, and today it leads in all five. Filling this gap cost about three days of fee income, completed in one afternoon. Whether that batch of targets was a deterrent or originally queued for launch cannot be determined from on-chain data.
What can be determined is the result. After four weeks, Paragon still holds 20% to 25% of four out of the five, and the overall trading volume increased by 49.9% that month. The mechanism is best illustrated by Yushu: Trade[XYZ]'s Yushu market depth is about 11 times that of Paragon, which only accounts for 8.2% of this pair, yet Paragon's own Yushu trading volume nearly doubled during the same period. The leader did not take volume away from the challengers; it expanded the market around the challengers. Entering a market and owning a market are two different things. Entropy led on Nebius for a week, then handed it back
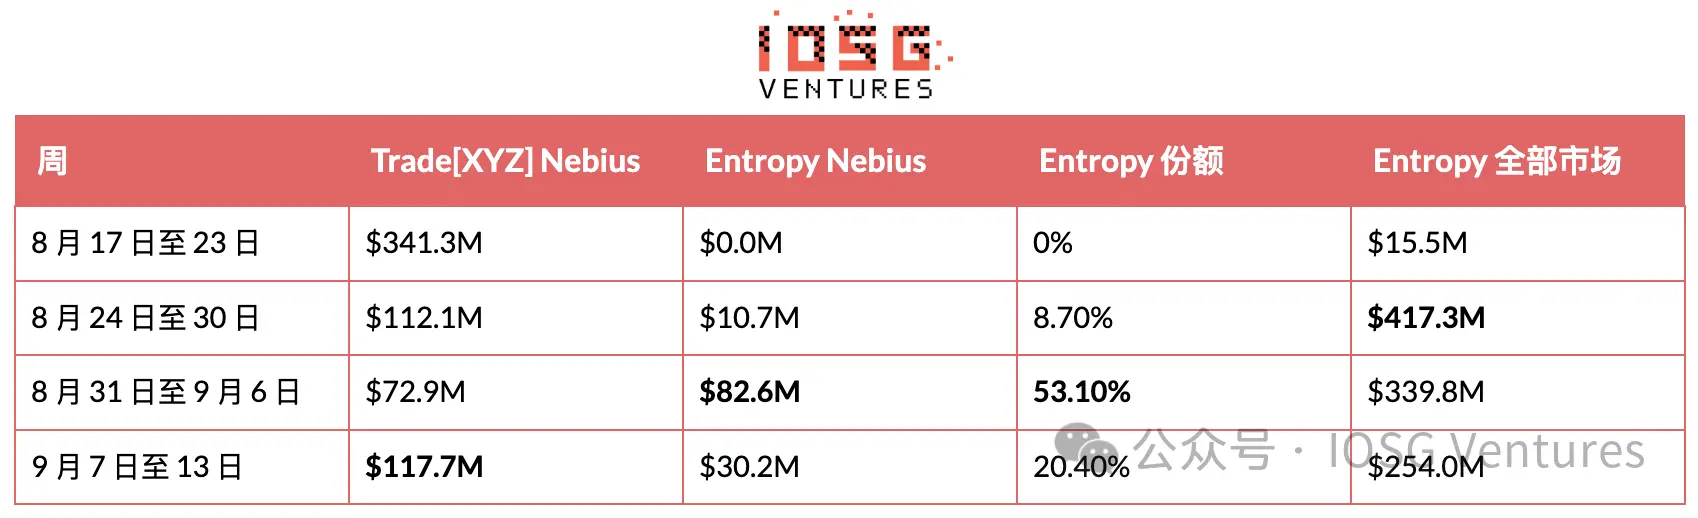
For one week, Entropy's Nebius trading volume indeed surpassed Trade[XYZ], something that HIP-3 challengers had never achieved. In the following week, the leader's Nebius market depth increased by 61%, while Entropy dropped by 63%, and the challengers returned to one-fifth of this pair. SanDisk tells the same story, just quieter: Entropy's market share has roughly hovered around 13% in recent weeks, averaging 8.5% over the entire 30 days.
So this lead was real, but it only lasted a week. The honest interpretation is: Entropy proved it could penetrate a market where a leader was actively quoting, but it has not yet proven it can hold its ground. Its total trading volume has fallen for three consecutive weeks, from $417M to $254M.
The reverse signal comes from inventory. While weekly trading volume fell 39% from its peak, Entropy's open interest actually increased by 37% to $51.4M, with one target from Anthropic accounting for $29.9M. The trading volume generated from wash trading will cancel out and leave no inventory, so while the trading share declines, open interest continues to accumulate, indicating real holdings rather than churn. These two facts point in opposite directions; the real focus should be on this tension itself, not on any single number.
The volume here needs to be discounted. Entropy has no tokens and has not confirmed any airdrops, but it can already see the pointsMultiplier parameter in the backend, and its leaderboard page states "coming soon," so part of the traffic is driven by expectations rather than product use, and the two cannot be separated externally. The scale also needs to be highlighted: Entropy's volume is about $1.0B in a month, while Trade[XYZ] is $64.6B, making it 1.6% of the leader. It wins specific battles, not this category.
The targets it has registered for upcoming launches reveal the next steps. Entropy holds EWY, SBE, TCNT, and a DRAM index. The DRAM index is Trade[XYZ]'s fourth-largest product, while EWY is from South Korea. The next confrontation seems to be directly aimed at the leader's core territory, rather than looking for another uncompetitive pre-IPO name.
Two counting rules
Only count online market depths. HIP-3 deployers often register targets long before activation; these targets will return oracle markPx, but midPx is null, isDelisted is true, open interest is zero, and there is no K-line history. Trade[XYZ] has 16, mkts has 19, Paragon has 9, and Entropy has 4. HyENA's 25 are a different matter, as they have been activated and then shut down.
Code strings do not equal targets. para:STX is Seagate, with a midpoint of 799; the core market's STX is Stacks, with a midpoint of 0.27. Relying solely on code would create a tenth confrontation market that does not exist. Verify the midpoint before pairing.
VI. Economic Account: The cost of one venue versus the income of the entire layer
No one is competing on price because the rates have hit rock bottom Everything hinges on two parameters for each asset, both publicly available in metaAndAssetCtxs: growthMode and deployerFeeScale. The all-inclusive fee rate is base × (1 + s), where base is the standard perpetual fee rate table, and s is the deployer coefficient, which can be set from 0 to 3.00, capped at 1.00 in Growth Mode. The deployer takes s / (1 + s), so when s = 1.00, they split it in half. Growth Mode then cuts at least 90% off the all-inclusive figure, provided the market does not overlap with the perpetual operations of validators, which excludes crypto assets and crypto indices.
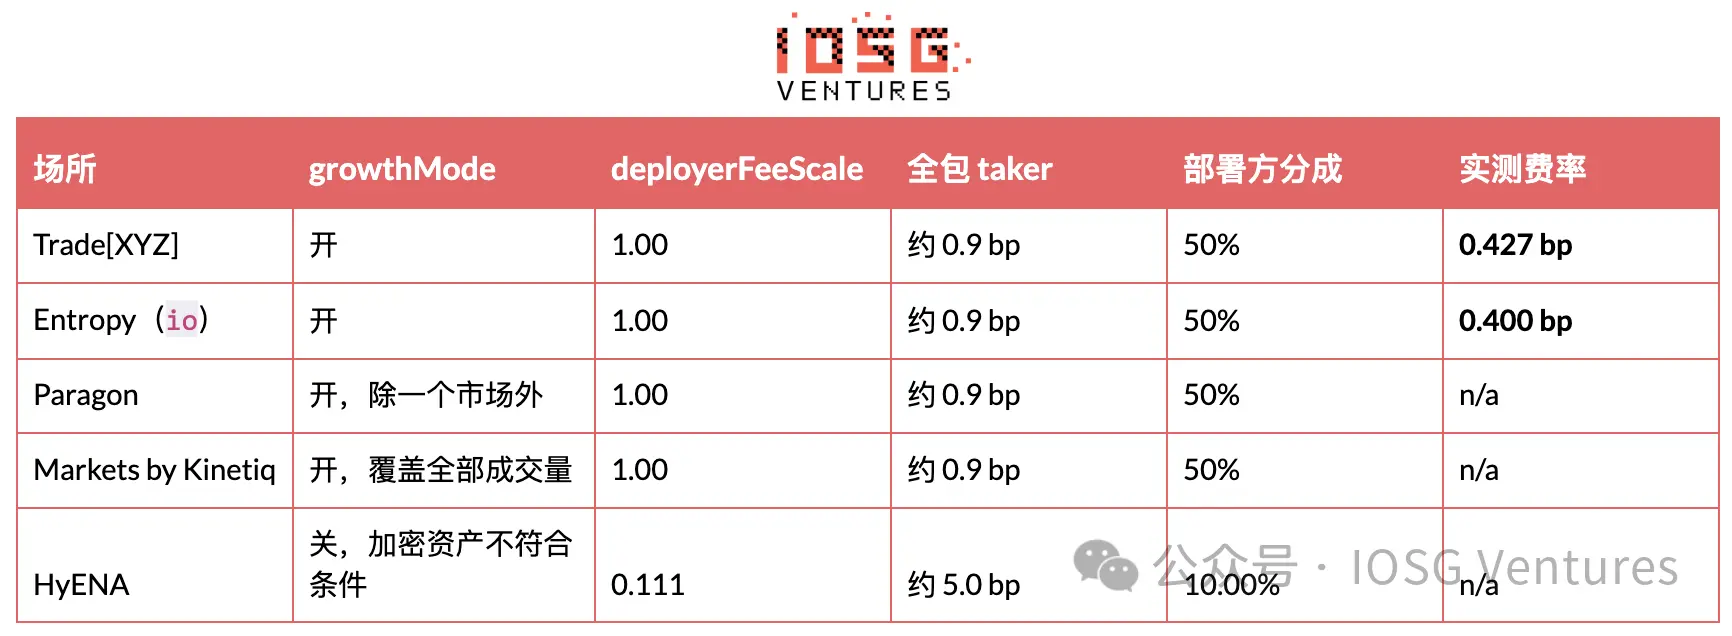
All stock venues have independently converged to the same configuration: deployer revenue maximized, Growth Mode activated. Entropy entered with differentiated products and venture capital, without pushing prices down. The only venue not in this configuration is the one that just stopped trading.
Without relying on any aggregator, deployer revenue can still be accurately calculated. Fee income accumulates in the sub-account of the fee receiving address: clearinghouseState with the dex field can read the unallocated balance, while transfers appear in userNonFundingLedgerUpdates, with the form being sourceDex equal to the venue name's send. Transfers are very irregular, so measurements must be taken between two transfers. Since the transfer on August 27, Trade[XYZ] has accumulated $1,380,592, corresponding to a trading volume of $32.30B, or 0.427 bp, approximately $79,000 per day. Entropy has never made a transfer, so its accumulated fees can be read directly: $1.036B in trading corresponds to $41,468, or 0.400 bp.
Two expenditures, completely different in nature
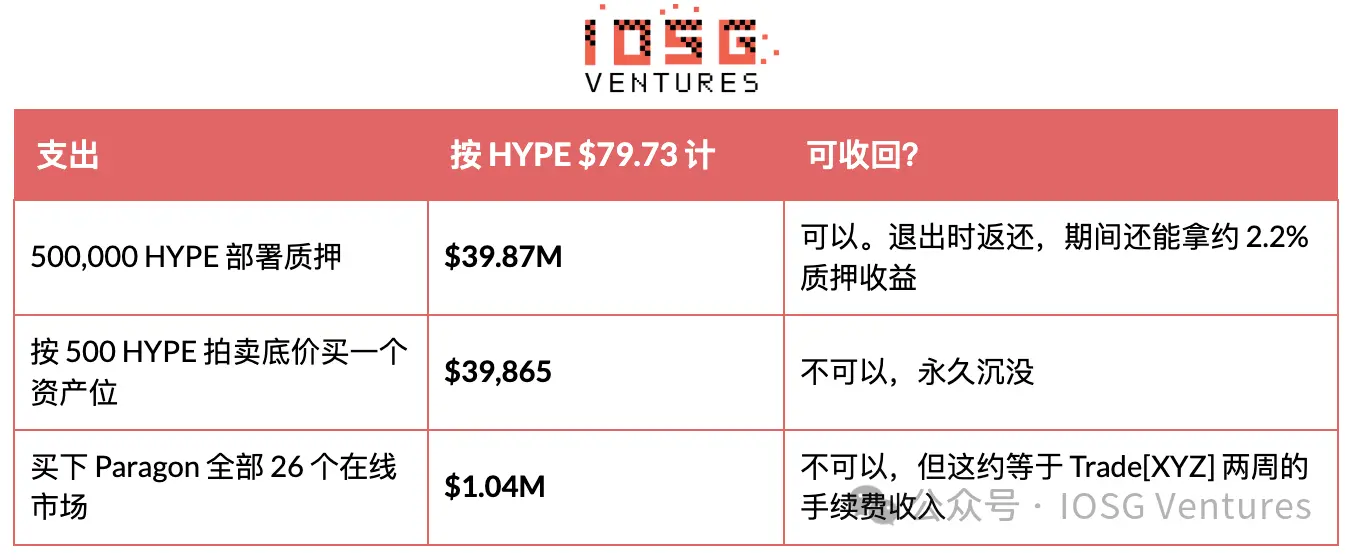
Staking is the scariest number, but it will come back. No one takes this money away. It is entrusted to validators, continuously generating staking rewards, and returned in the same form upon exit. It locks for at least 183 days from deployment and can be penalized by weighted validators for malicious market operations (such as pushing bad oracle prices), and can still be penalized during the 7-day unstaking queue, so a clean exit takes at least about 190 days. Felix and dreamcash both fully withdrew, and the current reading is zero.
Current staked amounts: Entropy 500,973, Paragon 500,712, HyENA 508,915 (stopped trading but not unstaked), Kinetiq 588,489 (one stake covering both km and mkts), Trade[XYZ] 500,488 plus another 500,269 at a different address. ABCDEx has only 1,004 HYPE, which has never been staked.
The money for asset positions is the one that no one mentions and truly cannot be returned. Any perpetual DEX's first three assets are free; thereafter, each additional market must be purchased using HYPE in a Dutch auction lasting 31 hours, with the opening price being twice the last transaction price, linearly decreasing to a bottom price of 500 HYPE. The auction entering on September 14 started at a bottom price of 500 and ended at 500, so one asset position is about $39,900, and the demand for asset positions has fallen compared to a week ago when the transaction price was 582 HYPE.
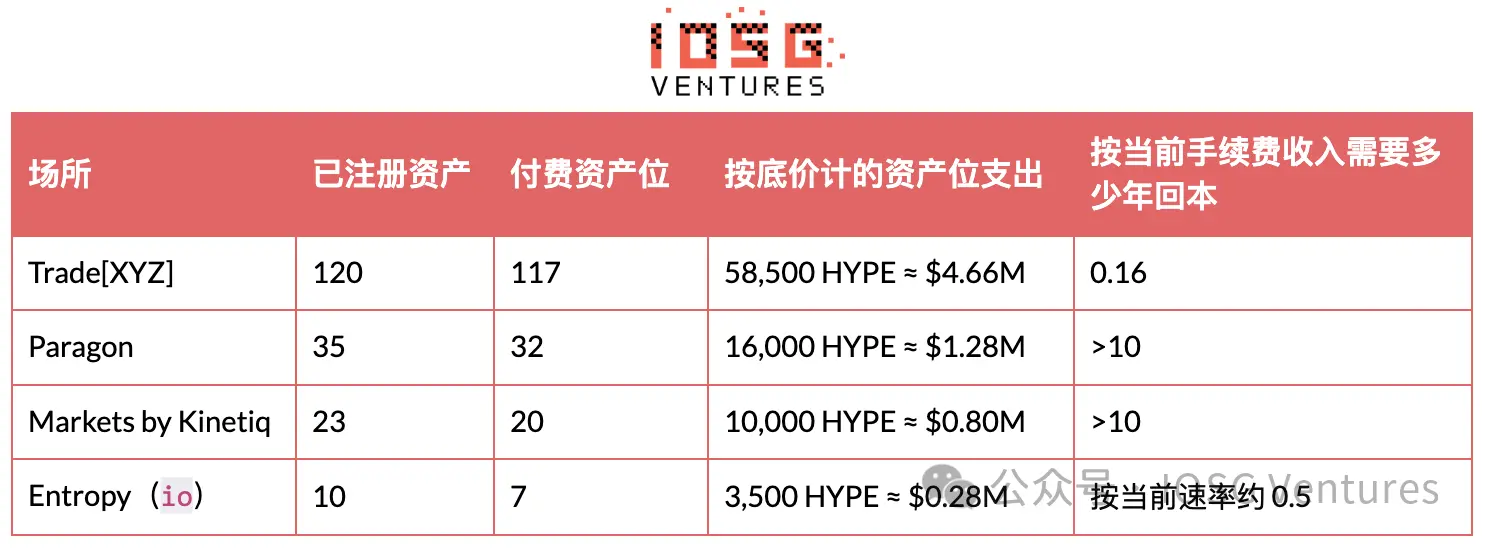 The last column is the key. Trade[XYZ]'s fees for about eight weeks could cover all target bills. Every challenger except Entropy requires more time than HIP-3 has existed; Entropy can pass only because it bought seven asset positions instead of thirty.
Time will continue to amplify this asymmetry. Pausing a market is free and reversible; paid asset positions can be sealed and reopened, and those "targets waiting to be launched" come from this. Reserve positions accumulate based on historical deployment numbers, with the formula being 7 + 0.2 × past auction deployment numbers, so Trade[XYZ] has about 30 that can be used immediately, while new entrants only have 7. A venue opening today, planning to create 20 markets, can list 10 at once, while the rest must queue in auctions, the fastest being one every 31 hours. Entropy's answer is not to play along with this rhythm: it only launched five markets and made each one count. Staking yield trap Except for Entropy, every challenger that earns money from passive staking entry tickets makes more than from operating exchanges. Paragon's lifetime deployer revenue is $64,281, while $39.87M in staking at about 2.2% yields approximately $877,000 per year, a ratio of about 14 times.
This is not a consolation. That yield is newly issued HYPE from the protocol's future emission reserves, essentially inflation rather than income, a dilution return on a position that is held involuntarily, with the valuation unit being the asset that the operator is already passively long on. HYPE dropped 30%, resulting in a loss of $12.0M on this stake, exceeding ten years of earnings. In the past eight days, HYPE has fallen from $88.37 to $79.73, thus reducing each staked amount by $4.3M. How large of a business can this fee pool support Growth Mode pins the actual fee rate around 0.4 bp, with the deployer taking half. Trade[XYZ] holds 97.8% of the market share, with an annualized trading volume of about $786B, leading to an annual deployer revenue of about $29M. Rather than being the ceiling for the leader, this is essentially the total bonus for the entire venue layer under the current trading volume and current fee floor.
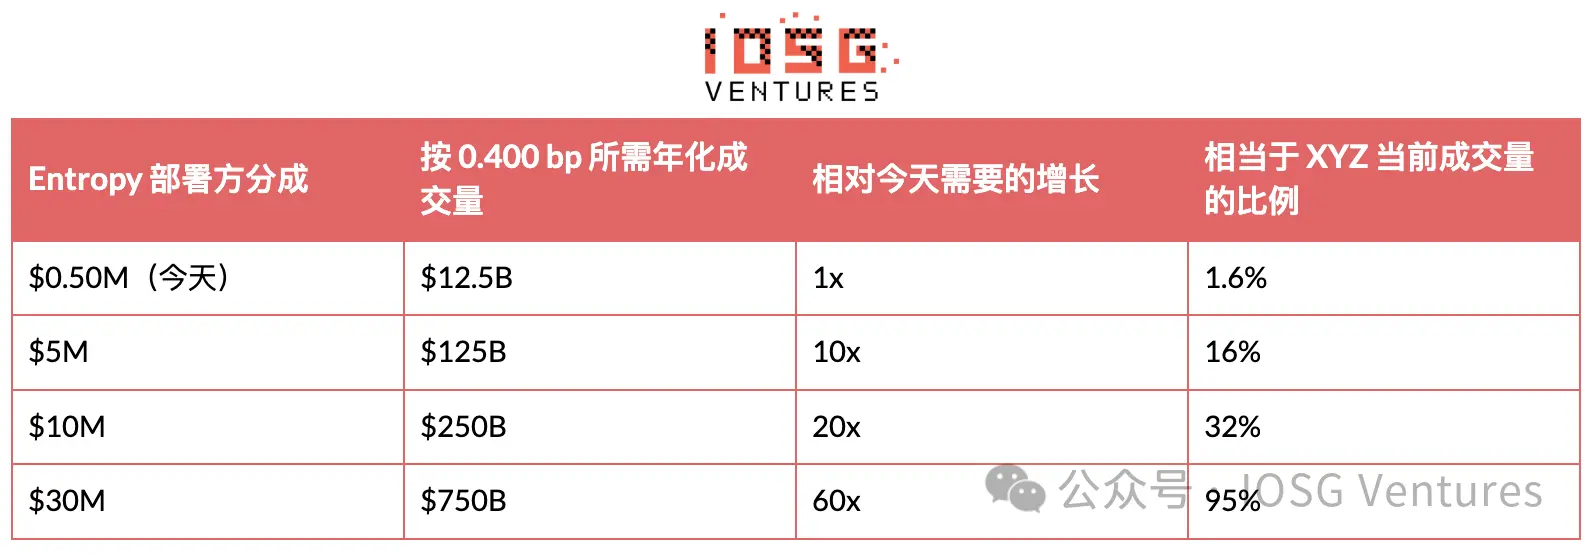
Outside of the leading venues, there is currently about $167M of HYPE at stake, and each of these venues, regardless of their fate, has collectively earned only $747,000 in deployment fees over their lifetime. When compared to a seed round of $14M, this arithmetic illustrates that under the current trading volume and fee floor, the operators of HIP-3 cannot rely on transaction fees for valuation. The value for challengers must come from elsewhere: tokens, front-end, customer relationships, or some product that the protocol has yet to price.
7. What Can Truly Be Held
HIP-3 intentionally commoditized most of what a venue could originally hold. Staking can be bought, the underlying can be bought, the fee floor is shared, and even distribution is shared, as every HIP-3 market can be accessed from the same front end.
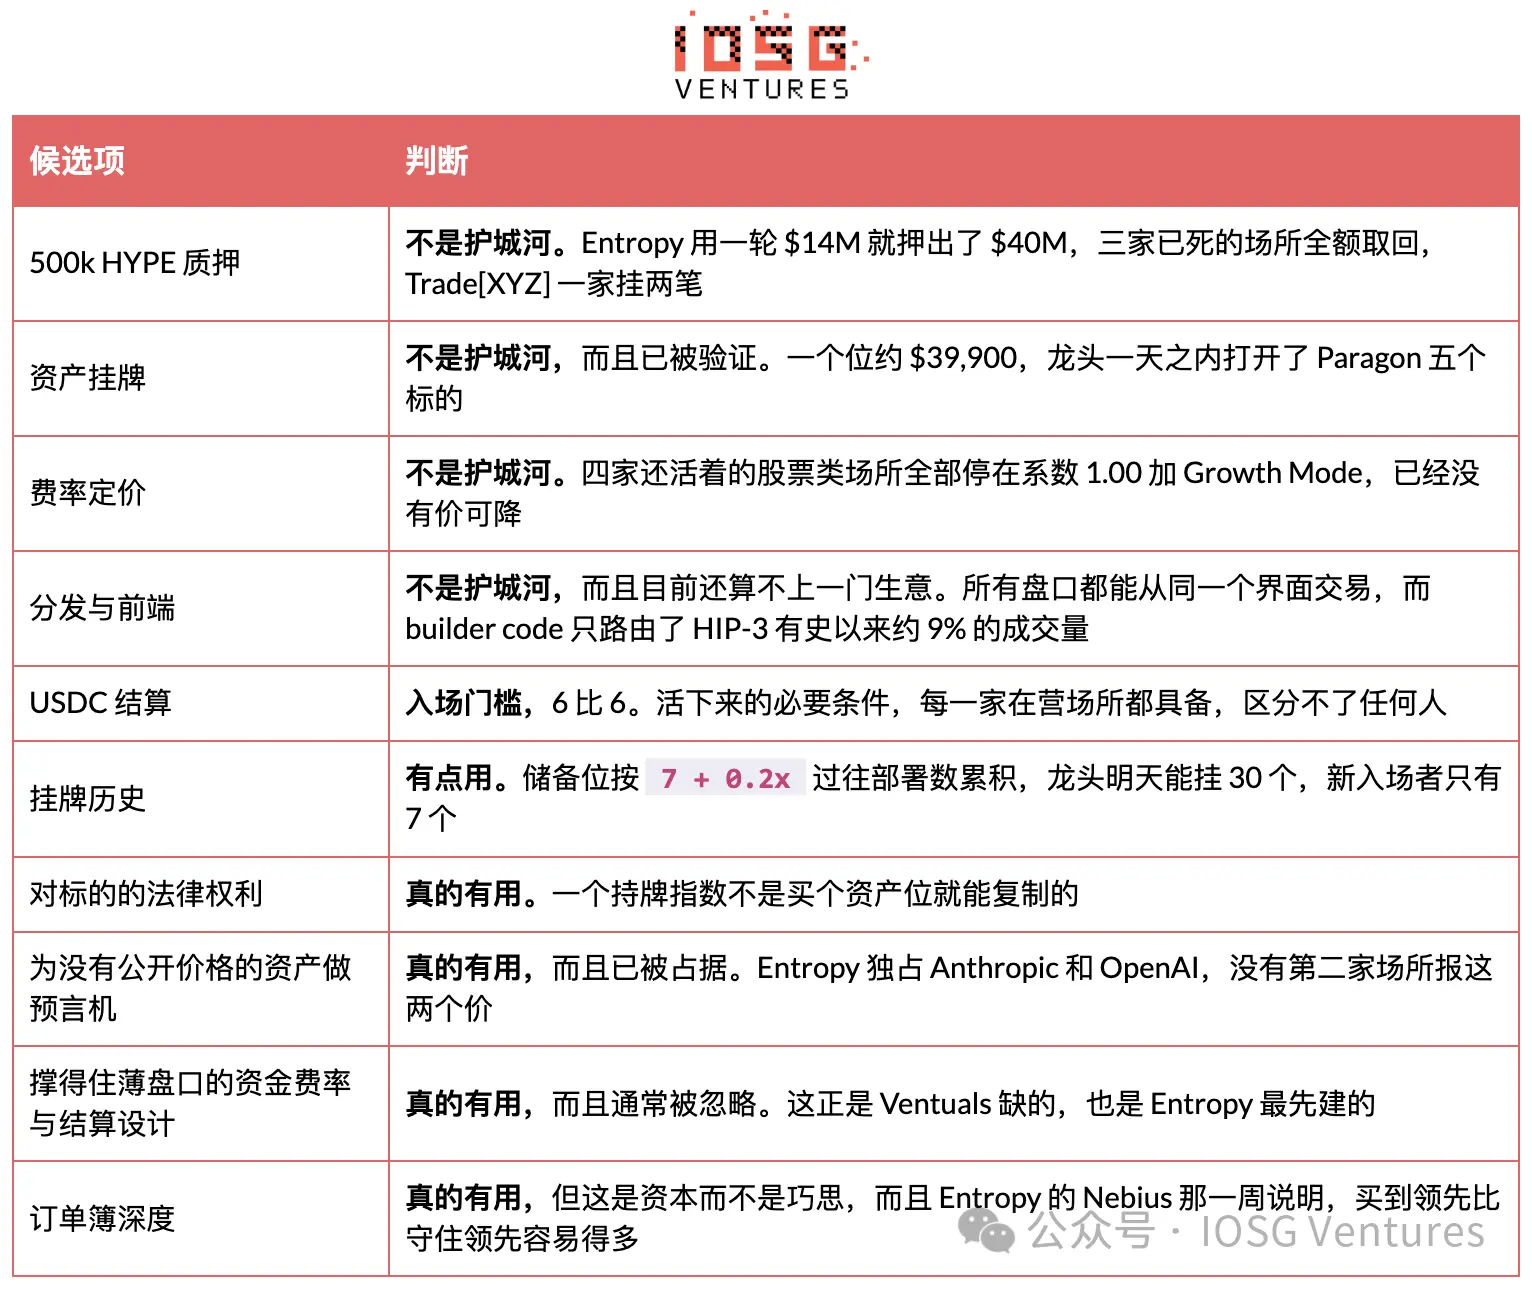 The useful filtering question is not "which assets do you want to list," because assets can be bought. Rather, it is "what do you have that the leader cannot buy with one asset position." Among all the venues that have operated on HIP-3, only one has a clear answer to this question, and its answer is a set of oracles combined with a settlement design, not a list of assets.
Entropy is the exception worth mentioning accurately because the answer does not lie in the underlying. It was founded by researchers and traders from Citadel Securities, Optiver, Millennium, and Polymarket, and this foundation is reflected in two aspects. One is the depth of orders available from day one, which truly impressed Nebius. The other is the funding rate and settlement design, which reads like a direct response to the demise of Ventuals. Its $14M seed round was led by Ribbit Capital, whose main focus is on retail brokerage and fintech distribution, not DeFi, indicating an ambition to hold onto customers rather than just exploit a protocol. It is important to note that Entropy Advisors, which is deeply tied to Arbitrum DAO, and the custody startup named Entropy backed by a16z are completely different companies, and no relationship with Hyper Foundation should be inferred from the name.
Putting all this together, this sector still appears thin. A shrinking company accounts for 97.8% of the trading volume. A circle of challengers holds $167M of HYPE, which has returned a total of $747,000 in historical fees among themselves. The only team that can truly quote prices has just demonstrated that it can capture a market for a week but cannot hold it.
A more straightforward alternative is to take the protocol's half of the transaction fees instead of the operator's half; it has no lock-up, no risk of forfeiture, and no operational burden. However, it is also not the mainstay of Hyperliquid's perpetual fee base, and it has been proven that HIP-3's share exceeding 50% is an illusion during periods of low crypto activity, not a trend. Routing Layer and Its Actual Traffic Impact Builder code is the closest thing to "shared business" on HIP-3. Orders sent from the front end are tagged, earning a builder fee without needing to post collateral. Flowscan counted 819 such tags.
The traffic they encounter is indeed not much. The routed trading volume is about $52.6B, accounting for roughly 9% of HIP-3's all-time $587B; in the last 30 days, it was about $5.3B, corresponding to $66.09B, approximately 8%. Over 90% of the traffic does not have front-end tags, which is exactly how a market dominated by market makers and API traders should look.
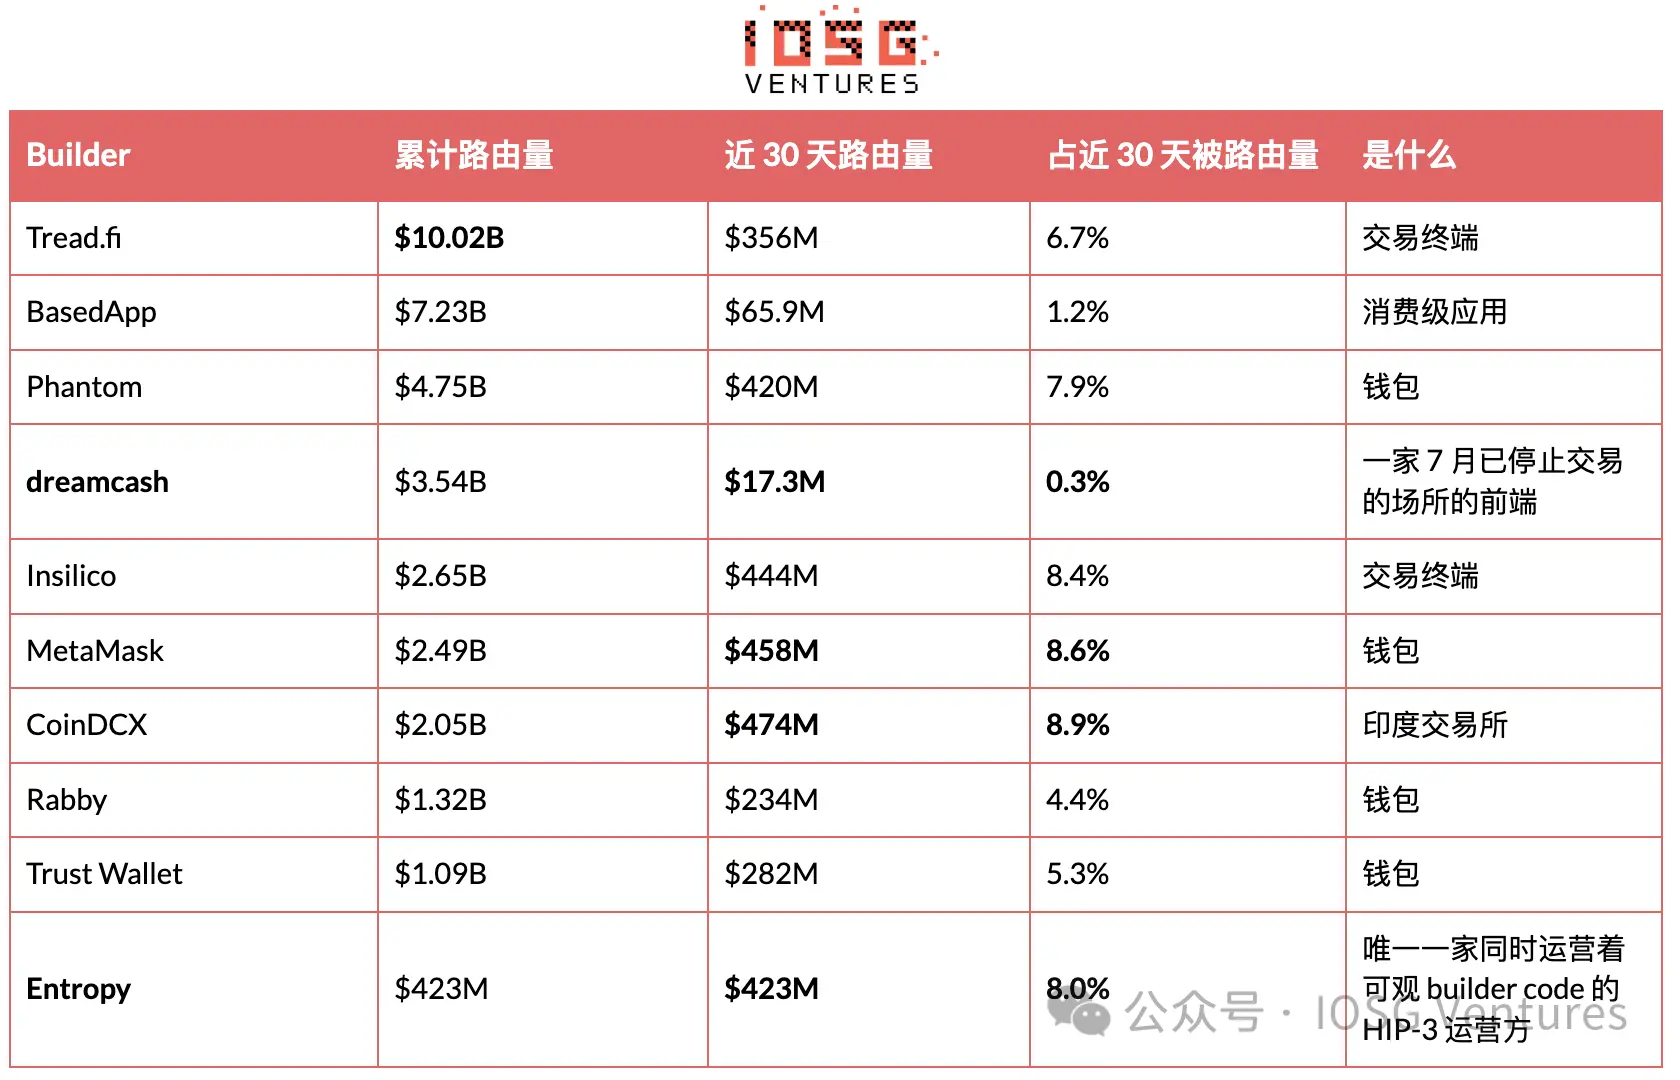 The denominator in the fourth column is the total $5.30B routed by builder code over the past 30 days, not HIP-3's $66.09B trading volume. If it were the latter, the largest, CoinDCX, would only account for 0.7%. The ten companies in the table collectively account for 59.7% of the routed volume, while Flowscan counted a total of 819 builder codes, meaning the remaining 809 share the other 40%.
There are two notable points in this table. Entropy's $423M routed volume all occurred in the last 30 days, while during the same period, its own venue traded $1.03B, meaning about 40% of the market came from its own controlled front end. The ambition of Ribbit behind that round is reflected in the data, rather than just remaining in press releases, and this is a business distinct from "being the deployment party."
The other point is dreamcash, which provides a cleaner lesson. Its venue has been dead since July 2, with its own market readings at zero, yet its builder code still routed $17.3M in the last 30 days, totaling $3.54B. The deployment business and front-end business can be cleanly separated, and only one of them requires $40M to enter.
There is an easily overlooked counting pit on third-party dashboards. Venue rankings typically default to cumulative trading volume, so a venue that stopped operating months ago may still appear to have a significant share. Dreamcash shows a 3.3% share of HIP-3 trading volume in the all-time view, but in any recent window, it is $0. Before citing any share, confirm which window it is calculated from. Thus, the front end worth monitoring is mostly not the deployment party. Coinbase announced a simplified perpetual interface within wallets on September 12, powered by Hyperliquid, covering crypto, tokenized stocks, and prediction markets, aimed at markets outside the U.S. Kraken's parent company is also discussing integrating Hyperliquid-related perpetuals into a regulated U.S. venue. Neither will stake that 500,000 HYPE. Conclusion: It Is Hard to Be Optimistic About Another HIP-3 Deployment Party Putting all the previous information together, a new HIP-3 venue faces the following set of numbers.
All HIP-3 trading volume outside of the leader totals $1.49B over 30 days, annualizing to about $18.1B. Based on the measured 0.400 bp, that amounts to $725,000 in deployment fees per year, to be shared among four venues. These four are currently holding about $167M of HYPE. The same amount of money staked passively at 2.2% yields $3.67M per year.
In other words, the money earned from operating these exchanges is about one-fifth of what the same funds would earn if staked in place.
This is not an undeveloped market but one that has already been priced close to zero, as reasons outlined in the previous sections are measurable. The asset position is $39,900, making it impossible to hold anything; the fee floor is shared, with no price to lower; distribution is also shared, and builder code only encounters 9% of the traffic; settlement assets have already converged to 6:6 with USDC, and AQAv2 explicitly does not provide any fee bias to HIP-3, so the protocol does not plan to subsidize this layer.
A more challenging aspect is the ceiling. XYZ, with a 97.8% share and every structural advantage, has only achieved a real transaction of 1.2% on the nine names it quotes, and its relative share on core storage assets is still declining. A new entrant faces not "the leader is too big," but "the leader is already very small and still getting smaller."
There is still only one exception, which has been clearly stated before: a right that others cannot buy, a set of oracles that others cannot produce, or a funding rate and settlement design that can survive in a thin market. Entropy is the only one that fits, and it was pushed back after just one week of leading. A list of assets is not the answer, and this point is now supported by two sets of independent data saying the same thing. What Could Change This Judgment
Entropy can hold a confrontation market for a month instead of a week and maintain its share against Shandi rather than drifting around 13%. Accumulating open interest while trading volume declines is the most noteworthy signal because it is more reliable than trading volume.
The launch of Entropy's DRAM index and Korean assets. These two directly target the core territory of the leader, rather than another uncompetitive pre-IPO name, and the result will be a much cleaner test than Nebius.
The terms of the tokens can make the equity calculations work. The fee calculations do not work, and the tokens do not exist today.
The pre-IPO sector can continue. Anthropic's market declined after the first week, and OpenAI opened at $5.3M a day, now around $4M. As long as one stabilizes, this becomes a category rather than a one-time launch trend.
The first payment of AQAv2 lands in early October. That will be the first time to observe the real scale of the protocol's USDC revenue line, to compare with the current third-party estimates ranging from $135M to $200M.
The fee floor loosens. Hyperliquid signaled in early August that subsequent upgrades would allow HIP-3 deployment parties to raise fees by up to 3 times per individual asset, effectively reversing the discounts of Growth Mode. No timeline has been given, and every number in Section 6 is built on the current floor.
The implementation of a licensed market. HIP-3* was announced on September 3, which is an optional on-chain whitelist allowing deployment parties to restrict which wallets can trade a certain market, aimed at compliance and institutional access, currently only on the testnet. This is the first mechanism that could make "access rights" rather than "assets" a scarce item.
The emergence of a team holding exclusive data or index authorization, with assets that indeed have 24/7 native crypto demand. This remains the only configuration where the logic of seizing positions completely fails.
Evidence shows that the leader's trading volume cannot sustain after the end of Growth Mode. Its measured 0.427 bp is only about one-tenth of what the same market should receive at standard rates; if this exemption is burdensome, then the stability of the leader is not as high as the share suggests.
HyENA unstakes its 508,915 HYPE, confirming that this venue has ended rather than gone dormant.
Some Limitations
The argument for seizing positions is based on measured shares, but the motivation belongs to inference. Five assets launched on the same day can also be interpreted as a launch pipeline that just happened to finish that day.
The judgment on Entropy is based only on 26 days of data. Nebius's lead and subsequent reversal are readings from a single week and a single medium-sized asset, neither of which should be taken as established conclusions moving forward.
The team background and financing rounds come from company announcements and media reports, not verifiable on-chain information.
The volatility conclusion in Section 2 is based on correlations from a sample of 45 working days, not causal decomposition. Trading volume and actual volatility may also be driven by the same factor, with the most direct candidate being the cooling off of overall AI capital expenditure transactions.
The number of transactions does not equate to the number of traders; the public API cannot produce independent traders.
The capital return-related figures are calculated based on HYPE $79.73 and a 2.2% annualized staking rate, the latter being a protocol parameter rather than a contractual commitment, and it will decrease as the total network staking amount increases.
 Risk warning
Popular articles





